




Anthropic Lost $80.7 Billion in the First Half of 2026: What Caused the AI Giant's Losses?
TradingKey - Anthropic's S-1 prospectus filed on October 26 showed that the company recorded a net loss of $80.748 billion in the first half of 2026.
Of that, $72.388 billion came from the "Change in fair value of convertible notes, derivative liabilities, and SAFEs", accounting for approximately 89.6% of the net loss. This loss was mainly driven by a significant increase in the value of conversion rights attached to early financing instruments following a surge in the company's valuation.
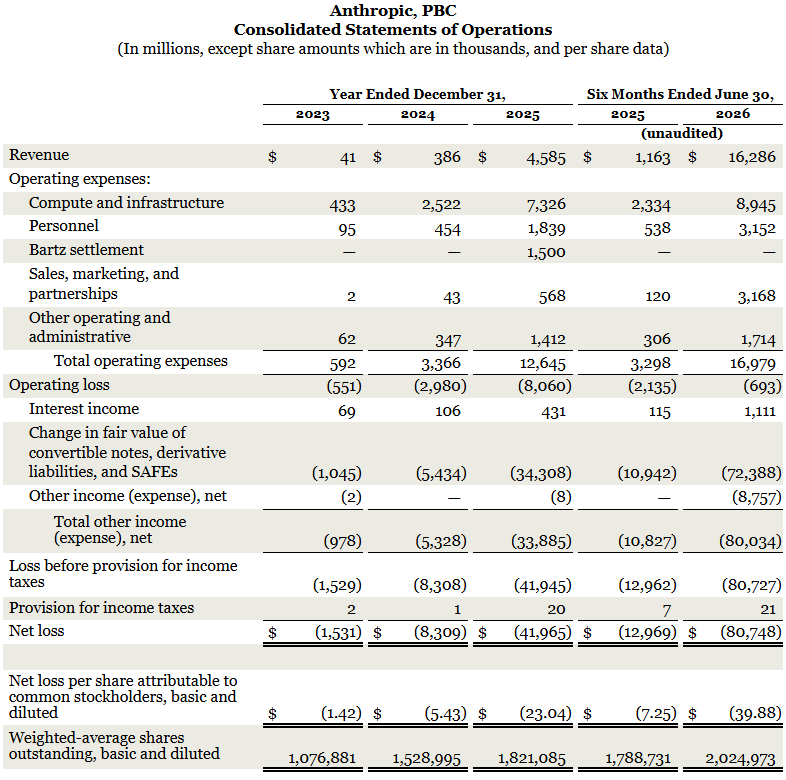
[Anthropic Consolidated Statement of Operations, Source: Anthropic, PBC - S-1]
It is worth noting that this $72.388 billion loss came entirely from convertible notes. The other two items in the line item name did not incur losses during the period: all SAFEs had long been converted into shares, and the separately listed derivative liabilities generated no losses during the period.
Convertible notes can be understood as "borrowing money first, to be converted into shares later at an agreed price." Anthropic chose to revalue these notes each reporting period and recognize the changes in value in earnings. The higher the company's valuation, the more valuable investors' rights to convert into shares at earlier lower prices become; for Anthropic, this means recognizing higher financing liabilities, with the increase forming a paper loss.
Amazon's investment terms help explain this process. As of the end of June, all unconverted notes were held by Amazon, with a total principal of $6.203 billion. The fixed conversion prices agreed upon for the two sets of notes were $2.0928 and $5.0478 per share, respectively. Calculated at these prices and temporarily disregarding ownership caps, they could be converted into approximately 1.84 billion shares. As Anthropic's shares become increasingly valuable, the value of these conversion rights could far exceed the initial principal invested.
However, Amazon is subject to a contractual 12% ownership cap. Unless it chooses to waive this cap, the portion exceeding the cap that cannot be converted will remain in the form of non-interest-bearing notes. As long as these notes remain unconverted or unsettled, Anthropic must continue to revalue them and record the value changes in profit and loss.
The accounting breakdown is as follows: at the end of 2025, these notes were valued at $41.677 billion; in the first half of the year, a portion of the notes was converted into shares, reducing the value by $5.499 billion; and the revaluation of the remaining and pre-conversion notes added another $72.388 billion in appreciation, ultimately bringing the carrying value of the notes to $108.566 billion at the end of June. The specific valuation also needs to consider conditions such as when conversion occurs, whether conversion is possible, and whether cash repayment is required, rather than relying on a simple calculation using principal or stock price.
Therefore, this loss does not represent an actual cash payment of $72.388 billion by Anthropic in the first half of the year. However, it still carries real economic implications: future share conversions will dilute existing shareholders' ownership percentages, and under contractual terms, a portion of the unconverted notes may also require cash settlement.
Recommended Articles


