


Not Micron, Not Sandisk. This Is My Top Memory Stock for 2027.
Key Points
SK Hynix recently reported a massive increase in revenue and earnings.
The company's dominant position in the memory market, especially high-bandwidth memory, should allow it to sustain solid growth next year.
SK Hynix stock trades at an extremely attractive valuation, and it is expected to clock stronger earnings growth than Sandisk and Micron in the long run.
- 10 stocks we like better than SK Hynix ›
Micron Technology and Sandisk have sizzled on the stock market in 2026. Both stocks have delivered impressive gains this year, despite witnessing a significant pullback in recent months amid the broader correction in tech stocks.
Micron stock, for instance, has gained 128% in 2026, as of this writing. Sandisk's gains are even bigger at 194%. Importantly, both memory companies can step on the gas once again in 2027, driven by the artificial intelligence (AI)-fueled demand for compute and storage.
Missed AI’s "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our analysts, we’re only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
However, I think that Micron and Sandisk could be overshadowed by South Korean memory giant SK Hynix (NASDAQ:SKHY) next year. Let's look at the reasons why.

Image source: Getty Images.
SK Hynix's strong market share puts it in a solid position to capitalize on the memory market's growth
SK Hynix sells both dynamic random-access memory (DRAM) and NAND flash memory. Counterpoint Research points out that the company controlled 29% of the DRAM market in the third quarter of 2026. It is second only to Samsung in this market. Micron, for comparison, has a 21% share of the DRAM market.
Meanwhile, SK Hynix's 19% share of NAND flash puts it ahead of both Micron and Sandisk, which have market shares of 15% and 11%, respectively. The South Korean company's healthy market shares in both DRAM and NAND flash explain why it reported phenomenal growth in Q3. SK Hynix's revenue surged 328% year over year to $79 billion, easily beating the consensus estimate.
The company's operating profit jumped 632% from the year-ago period and exceeded analysts' expectations. SK Hynix is well-placed to sustain such impressive growth. That's because the company has already sold more than half of its production capacity for 2027 and 2028 under long-term agreements with 14 customers.
Moreover, SK Hynix anticipates that memory demand will outstrip supply through 2030, indicating that the favorable environment fueling the company's stunning growth is sustainable. Also, SK Hynix is ramping up production of its next-generation high-bandwidth memory (HBM) chips, known as HBM4.
It points out that HBM4 has twice the bandwidth of the previous-generation HBM3E chips and 40% higher power efficiency. SK Hynix notes that HBM4 revenue and shipments will surpass those of HBM3E in the current quarter, which should bode well for the company's margins. That's because HBM4 reportedly carries a 24% premium per gigabyte (GB) over the previous generation, HBM3E.
What's more, SK Hynix controls a third of the global HBM market, higher than Micron's 18% share. This is another reason to buy SK Hynix, considering that the global HBM market's revenue could surge to a whopping $641 billion in 2030, according to Bloomberg Intelligence. The firm has significantly upgraded this guidance from its earlier estimate of $260 billion, noting that the average price of HBM will more than double over the next four years.
So, there is a strong likelihood that SK Hynix's revenue growth will outpace Wall Street's expectations.
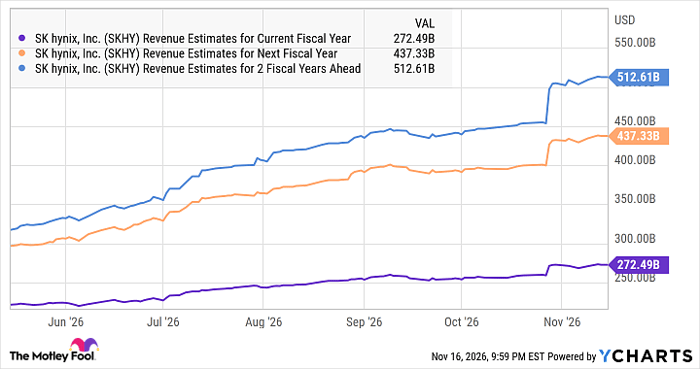
SKHY Revenue Estimates for Current Fiscal Year data by YCharts
Here's why SK Hynix is clearly a better bet than Sandisk and Micron
SK Hynix's lead over Micron and Sandisk in DRAM and NAND flash should ideally give it greater pricing power over its rivals. This probably explains why analysts expect SK Hynix's earnings per share to increase at a much faster pace in the long run.
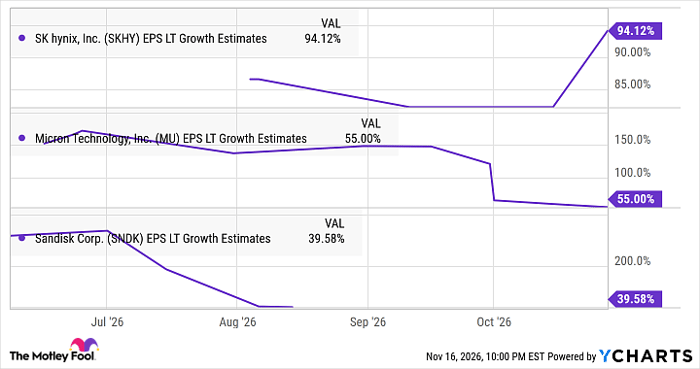
SKHY EPS LT Growth Estimates data by YCharts
Also, SK Hynix's valuation is in line with Micron and Sandisk's multiples.
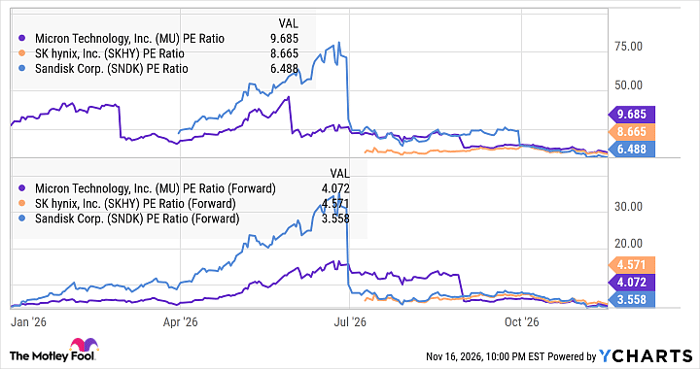
MU PE Ratio data by YCharts
So, even though SK Hynix stock hasn't made a bright start on the U.S. stock market following its listing on the Nasdaq this year, it remains worth buying on account of its red-hot growth, cheap valuation, and the ability to outperform Micron and Sandisk. In the end, I won't be surprised to see this AI stock's fortunes turn around in the New Year, and buying it while it trades at cheap multiples seems prudent.
Should you buy stock in SK Hynix right now?
Before you buy stock in SK Hynix, consider this:
The Motley Fool Stock Advisor analyst team just identified what they believe are the 10 best stocks for investors to buy now… and SK Hynix wasn’t one of them. The 10 stocks that made the cut could produce monster returns in the coming years.
Consider when Netflix made this list on December 17, 2004... if you invested $1,000 at the time of our recommendation, you’d have $321,850!* Or when Nvidia made this list on April 15, 2005... if you invested $1,000 at the time of our recommendation, you’d have $955,232!*
Now, it’s worth noting Stock Advisor’s total average return is 793% — a market-crushing outperformance compared to 203% for the S&P 500. Don't miss the latest top 10 list, available with Stock Advisor, and join an investing community built by individual investors for individual investors.
See the 10 stocks »
*Stock Advisor returns as of November 18, 2026.
Harsh Chauhan has no position in any of the stocks mentioned. The Motley Fool has positions in and recommends Micron Technology. The Motley Fool has a disclosure policy.
Recommended Articles


