


Japanese Yen remains subdued as Fed’s Powell says 50 bps cuts are not a new pace
- The Japanese Yen depreciated as Fed Chair Powell emphasized that 50 basis points cuts are not the "new pace.”
- The JPY’s downside could be restrained due to hawkish sentiment surrounding the Bank of Japan.
- Fed policymakers raised their long-term projection for the federal funds rate from 2.8% to 2.9%.
The Japanese Yen (JPY) has trimmed its intraday losses but remains weaker against the US Dollar (USD) on Thursday. Despite the US Federal Reserve’s (Fed) aggressive 50 basis point (bps) interest rate cut on Wednesday, the risk-sensitive JPY continued to depreciate.
Traders are now focusing on the Bank of Japan (BoJ) policy decision scheduled for Friday, with expectations that rates will be kept unchanged while leaving room for potential future rate hikes. Additionally, Japan’s National Consumer Price Index (CPI) data will be closely watched, as the inflation report could provide new insights into the BoJ’s future interest rate path.
The USD/JPY pair's upside could be attributed to remarks made by Fed Chair Jerome Powell. In the post-meeting press conference, Powell stated that the Fed is not in a hurry to ease policy and emphasized that half-percentage point rate cuts are not the "new pace."
Fed policymakers updated their quarterly economic forecasts, increasing the median projection for unemployment to 4.4% by the end of 2024, up from the 4.0% estimate made in June. They also raised their long-term projection for the federal funds rate from 2.8% to 2.9%.
Daily Digest Market Movers: Japanese Yen depreciates as Fed raises long-term projection for rates
- The Federal Open Market Committee (FOMC) lowered the federal funds rate to a range of 4.75% to 5.0%, marking the Fed’s first rate cut in over four years.
- Federal Reserve Chair Jerome Powell commented on the aggressive 50 basis point rate cut, saying, “This decision reflects our increased confidence that, with the right adjustments to our policy approach, we can maintain a strong labor market, achieve moderate economic growth, and bring inflation down to a sustainable 2% level.”
- Japan’s Merchandise Trade Balance Total recorded a larger trade deficit of ¥695.30 billion in August, up from ¥628.70 billion the previous month, but well below market expectations of a ¥1,380.0 billion shortfall. Exports increased by 5.6% year-over-year, marking the ninth consecutive month of growth, but fell short of the anticipated 10.0%. Imports rose by just 2.3%, the slowest pace in five months, significantly underperforming the projected 13.4% rise.
- JP Morgan CEO Jamie Dimon stated on Tuesday that whether the Federal Reserve cuts interest rates by 25 or 50 basis points, the impact will be “not earth-shattering.” Dimon emphasized, “They need to do it,” but noted that such moves are relatively minor in the grand scheme of things, as "there's a real economy" operating beneath the Fed’s rate changes, according to Bloomberg.
- US Retail Sales rose by 0.1% month-over-month in August, following a revised 1.1% increase in July, surpassing expectations of a 0.2% decline and indicating resilient consumer spending. Meanwhile, the Retail Sales Control Group increased by 0.3%, slightly below the previous month's 0.4% rise.
- Japanese Finance Minister Shunichi Suzuki stated on Tuesday that rapid foreign exchange (FX) fluctuations are undesirable. Suzuki emphasized that officials will closely monitor how FX movements affect the Japanese economy and people's livelihoods. The government will continue to assess the impact of a stronger Japanese Yen and respond accordingly, according to Reuters.
- Commerzbank FX analyst Volkmar Baur anticipated that the Bank of Japan will remain on the sidelines this week. Baur noted that the Federal Reserve's actions are likely to have a greater impact on the USD/JPY pair, suggesting that the JPY could have a strong chance of falling below 140.00 per USD even without a rate hike from the BoJ.
- On Friday, Fitch Ratings' latest report on the Bank of Japan's policy outlook suggests that the BoJ might raise rates to 0.5% by the end of 2024, 0.75% in 2025, and 1.0% by the end of 2026.
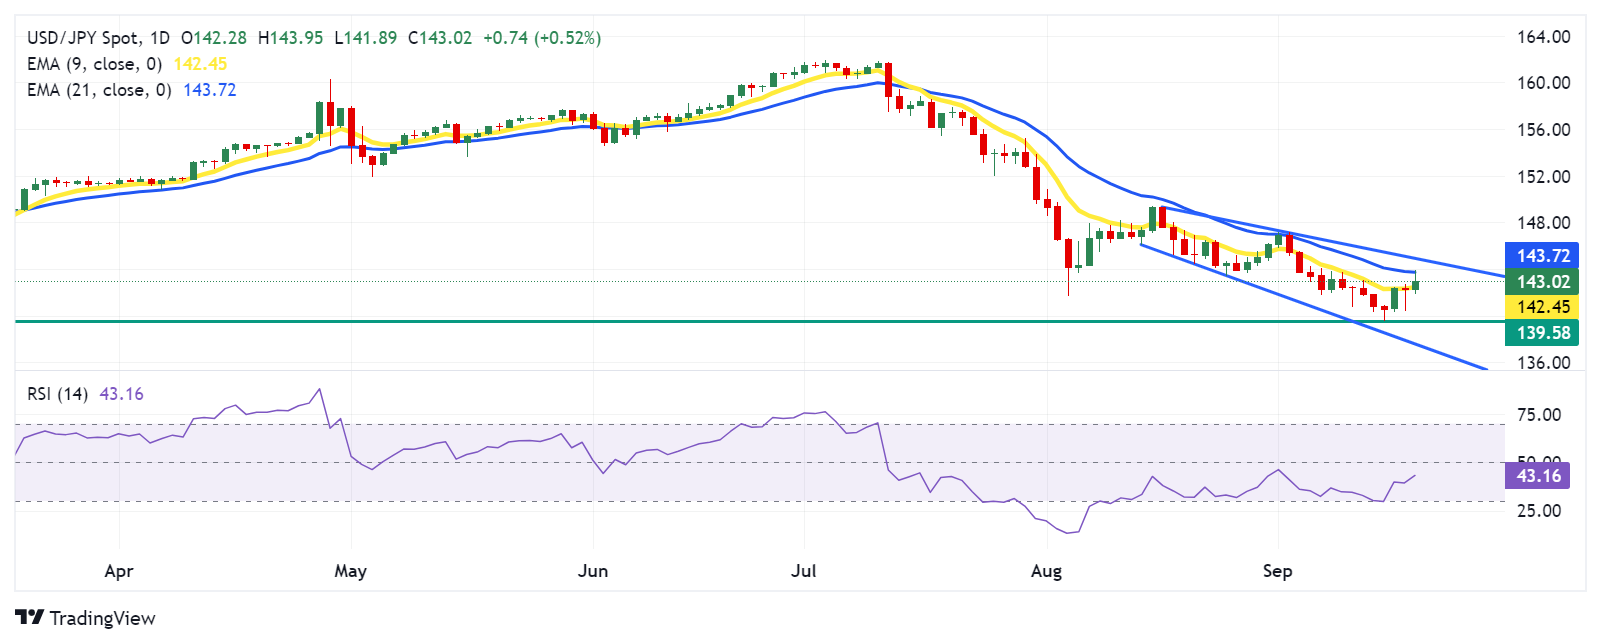
Technical Analysis: USD/JPY advances to near 143.00; next barrier at 21-day EMA
USD/JPY trades around 143.00 on Thursday. Analysis of the daily chart indicates that the pair is consolidating within a descending channel, which supports a bearish outlook. However, the 14-day Relative Strength Index (RSI) is rising toward the 50 level, and the price has moved above the nine-day Exponential Moving Average (EMA), suggesting a potential upward correction.
On the upside, the USD/JPY pair may initially face resistance at the 21-day EMA, located at the 143.73 level, and then at the upper boundary of the descending channel around 145.00.
For support, the USD/JPY pair might find immediate support at 139.58, which is the lowest level since June 2023, followed by the lower boundary of the descending channel near 137.75.
USD/JPY: Daily Chart
Japanese Yen PRICE Today
The table below shows the percentage change of Japanese Yen (JPY) against listed major currencies today. Japanese Yen was the weakest against the Australian Dollar.
| USD | EUR | GBP | JPY | CAD | AUD | NZD | CHF | |
|---|---|---|---|---|---|---|---|---|
| USD | 0.02% | 0.07% | 0.67% | -0.01% | -0.37% | -0.05% | 0.31% | |
| EUR | -0.02% | 0.04% | 0.67% | -0.02% | -0.36% | -0.06% | 0.32% | |
| GBP | -0.07% | -0.04% | 0.62% | -0.08% | -0.43% | -0.11% | 0.24% | |
| JPY | -0.67% | -0.67% | -0.62% | -0.67% | -1.04% | -0.76% | -0.38% | |
| CAD | 0.01% | 0.02% | 0.08% | 0.67% | -0.35% | -0.03% | 0.31% | |
| AUD | 0.37% | 0.36% | 0.43% | 1.04% | 0.35% | 0.32% | 0.67% | |
| NZD | 0.05% | 0.06% | 0.11% | 0.76% | 0.03% | -0.32% | 0.36% | |
| CHF | -0.31% | -0.32% | -0.24% | 0.38% | -0.31% | -0.67% | -0.36% |
The heat map shows percentage changes of major currencies against each other. The base currency is picked from the left column, while the quote currency is picked from the top row. For example, if you pick the Japanese Yen from the left column and move along the horizontal line to the US Dollar, the percentage change displayed in the box will represent JPY (base)/USD (quote).
Japanese Yen FAQs
The Japanese Yen (JPY) is one of the world’s most traded currencies. Its value is broadly determined by the performance of the Japanese economy, but more specifically by the Bank of Japan’s policy, the differential between Japanese and US bond yields, or risk sentiment among traders, among other factors.
One of the Bank of Japan’s mandates is currency control, so its moves are key for the Yen. The BoJ has directly intervened in currency markets sometimes, generally to lower the value of the Yen, although it refrains from doing it often due to political concerns of its main trading partners. The current BoJ ultra-loose monetary policy, based on massive stimulus to the economy, has caused the Yen to depreciate against its main currency peers. This process has exacerbated more recently due to an increasing policy divergence between the Bank of Japan and other main central banks, which have opted to increase interest rates sharply to fight decades-high levels of inflation.
The BoJ’s stance of sticking to ultra-loose monetary policy has led to a widening policy divergence with other central banks, particularly with the US Federal Reserve. This supports a widening of the differential between the 10-year US and Japanese bonds, which favors the US Dollar against the Japanese Yen.
The Japanese Yen is often seen as a safe-haven investment. This means that in times of market stress, investors are more likely to put their money in the Japanese currency due to its supposed reliability and stability. Turbulent times are likely to strengthen the Yen’s value against other currencies seen as more risky to invest in.
Recommended Articles


