


Pound Sterling remains on backfoot amid Middle East tensions, upbeat US Dollar
- The Pound Sterling faces pressure as geopolitical tensions improve the appeal for safe-haven assets.
- UK’s employment and inflation data will influence speculation over BoE rate cuts.
- The UK economy is on track to come out of a technical recession.
The Pound Sterling (GBP) shows a modest recovery against the US Dollar in Monday’s London session. However, the near-term demand of the GBP/USD pair remains downbeat due to deepening Middle East tensions and speculation that the Bank of England (BoE) will start reducing interest rates sooner than the Federal Reserve (Fed).
Currently, financial markets anticipate that the BoE will begin lowering borrowing costs from August while the Fed is expected to follow the same from the September meeting.
This week, the United Kingdom’s employment and inflation data will freshly guide market expectations for the BoE as markets wonder when it could start its much-awaited rate-cut cycle. Investors will keenly focus on the wage growth data for three months ending February, which will be released on Tuesday, as it remains a key driver to the UK’s stubborn price pressures.
Daily digest market movers: Pound Sterling eyes downside, focus shifts to UK Employment
- The Pound Sterling finds interim support after diving to a more than four-month low near 1.2430. Escalating Middle East tensions and receded bets that the Federal Reserve (Fed) will pivot to rate cuts in the June meeting have dented the appeal of risk-sensitive currencies.
- Hundreds of air strikes from Iran on Israel in retaliation to its attack on the Iranian embassy in Syria near Damascus, in which seven members of its Islamic Revolutionary Guard Corps (IRGC), including two generals, were killed, have spooked demand for risk-perceived currencies.
- Both scenarios—escalation in geopolitical tensions and faded Fed rate cut hopes—are favorable for the US Dollar, which is considered a safe-haven asset. The US Dollar Index (DXY), which tracks the US Dollar’s value against six major currencies, hovers near a fresh five-month high at 106.10.
- In Monday’s session, investors will focus on the United States monthly Retail Sales data for March, which will be published at 12:30 GMT. The Retail Sales data, representing households’ spending is forecasted to have grown by 0.3%, half the pace of February’s 0.6%.
- On the United Kingdom’s front, improved monthly Gross Domestic Product (GDP) numbers have relieved Bank of England (BoE) policymakers. As expected, the monthly GDP for February rose by 0.1%, confirming that the economy is on course to come out of a technical recession registered in the second half of 2023. The economy also expanded by 0.3% in January, revised higher from 0.2%.
- Due to the improving economic outlook, the BoE could maintain a restrictive policy until they gain confidence that inflation will sustainably return to the 2% target.
Technical Analysis: Pound Sterling remains below 1.2500
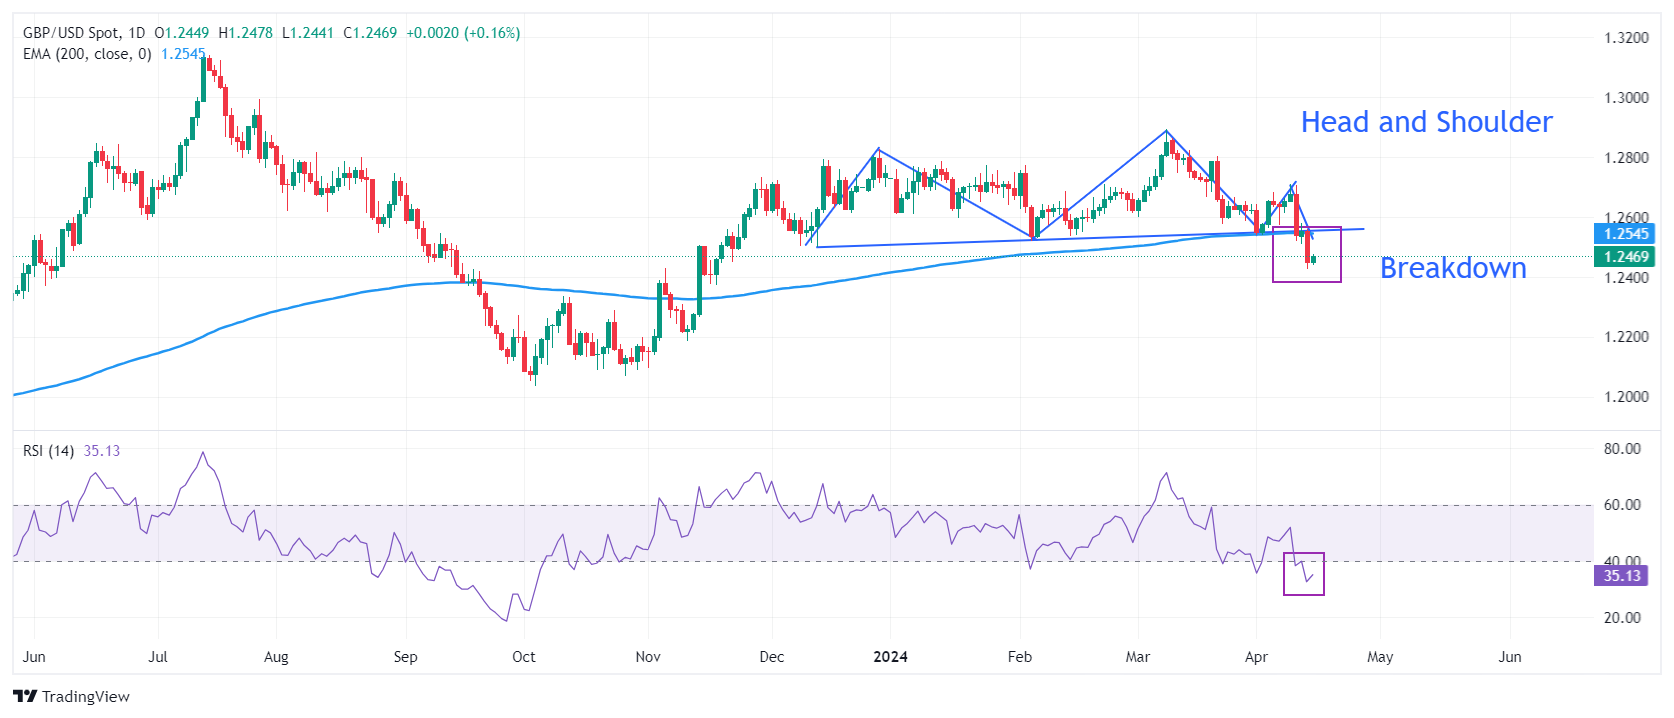
The Pound Sterling experiences a sharp sell-off after a breakdown of the psychological support at1.2500. The long-term trend of the GBP/USD pair has turned bearish as it has dropped below the 200-day Exponential Moving Average (EMA), which trades around 1.2570.
A breakdown of the Head and Shoulder chart pattern on a daily timeframe has indicated a bearish reversal. The neckline of the aforementioned chart pattern is plotted from December 8 low near 1.2500.
The 14-period Relative Strength Index (RSI) slips sharply below 40.00, indicating that a fresh bearish momentum has been triggered.
Pound Sterling FAQs
The Pound Sterling (GBP) is the oldest currency in the world (886 AD) and the official currency of the United Kingdom. It is the fourth most traded unit for foreign exchange (FX) in the world, accounting for 12% of all transactions, averaging $630 billion a day, according to 2022 data. Its key trading pairs are GBP/USD, aka ‘Cable’, which accounts for 11% of FX, GBP/JPY, or the ‘Dragon’ as it is known by traders (3%), and EUR/GBP (2%). The Pound Sterling is issued by the Bank of England (BoE).
The single most important factor influencing the value of the Pound Sterling is monetary policy decided by the Bank of England. The BoE bases its decisions on whether it has achieved its primary goal of “price stability” – a steady inflation rate of around 2%. Its primary tool for achieving this is the adjustment of interest rates. When inflation is too high, the BoE will try to rein it in by raising interest rates, making it more expensive for people and businesses to access credit. This is generally positive for GBP, as higher interest rates make the UK a more attractive place for global investors to park their money. When inflation falls too low it is a sign economic growth is slowing. In this scenario, the BoE will consider lowering interest rates to cheapen credit so businesses will borrow more to invest in growth-generating projects.
Data releases gauge the health of the economy and can impact the value of the Pound Sterling. Indicators such as GDP, Manufacturing and Services PMIs, and employment can all influence the direction of the GBP. A strong economy is good for Sterling. Not only does it attract more foreign investment but it may encourage the BoE to put up interest rates, which will directly strengthen GBP. Otherwise, if economic data is weak, the Pound Sterling is likely to fall.
Another significant data release for the Pound Sterling is the Trade Balance. This indicator measures the difference between what a country earns from its exports and what it spends on imports over a given period. If a country produces highly sought-after exports, its currency will benefit purely from the extra demand created from foreign buyers seeking to purchase these goods. Therefore, a positive net Trade Balance strengthens a currency and vice versa for a negative balance.
Recommended Articles


