

SanDisk Drops Over 9% Pre-Market: Quarterly Revenue Surges 378% to Beat Estimates Amid Growth Sustainability Concerns

Source Tradingkey

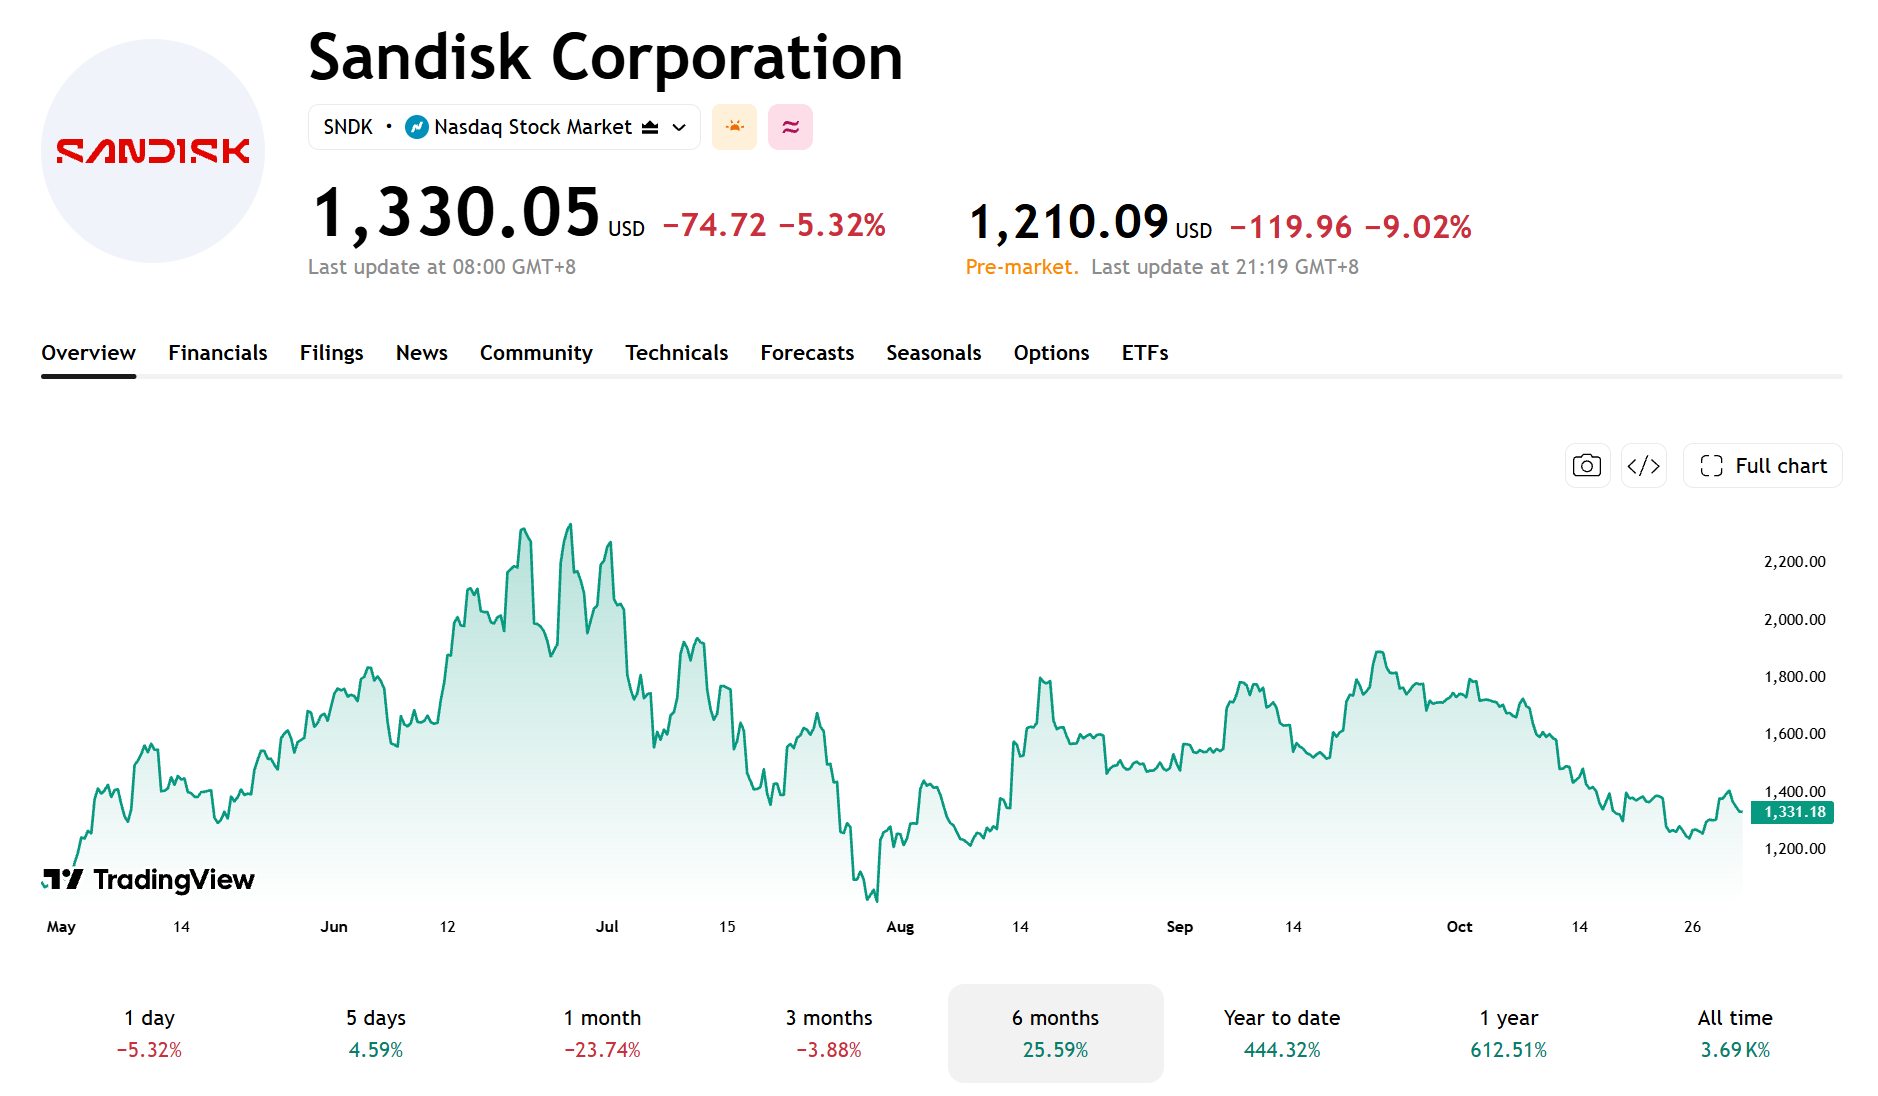
TradingKey - On October 30 EST, as of press time, SanDisk (SNDK) fell 9.02% in pre-market trading to $1,210.09.

The company's latest quarterly revenue and adjusted earnings per share both exceeded market expectations, but its stock price still moved lower following the earnings release. Slower quarter-over-quarter revenue growth, declining revenue in the consumer business, and market doubts about the sustainability of high gross margins emerged as key concerns for investors.
sndk-030-5a127bbb4b624eee9beaac46207b0826

[Source: TradingView]

Q1 Revenue Up 378% YoY, Data Center Revenue Up 61% QoQ

SanDisk reported its first-quarter fiscal 2027 financial results on October 29. For the period ended October 2, the company generated revenue of $11.031 billion, up 23% quarter-over-quarter and 378% year-over-year, exceeding market expectations of approximately $10.7 billion; non-GAAP earnings per share was $49.51, higher than market expectations of approximately $47.15. Non-GAAP gross margin was 85.1%, up 0.5 percentage points from the previous quarter.

By business segment, Data Center revenue was $4.802 billion, up 61% quarter-over-quarter; Edge revenue was $5.832 billion, up 7% quarter-over-quarter; Consumer revenue was $397 million, down 29% quarter-over-quarter and 39% year-over-year.

In terms of quarter-over-quarter growth rate, the Data Center business was the fastest-growing segment this quarter; meanwhile, the Consumer business continued to decline, with revenue falling below the levels of both the previous quarter and the same period last year.

Revenue Growth Slows as High Gross Margin Sustainability Draws Focus

Despite SanDisk's strong performance this quarter, quarter-over-quarter revenue growth slowed to 23% from 51% in the previous quarter. Meanwhile, revenue from the consumer segment continued to decline, while data center revenue's share of total revenue rose from approximately 33% in the previous quarter to about 44%, further increasing its reliance on the data center market for business growth.

In addition, the company's non-GAAP gross margin reached a high level of 85.1% this quarter. SanDisk projects a non-GAAP gross margin of 84.5% to 85.5% for the second quarter of fiscal 2027, indicating that management expects to maintain a similar level in the near term.

However, NAND average selling prices, market supply and demand, and shifts in product mix will continue to influence future gross margin performance. If memory price increases slow or shipment growth weakens, the company's revenue and profit growth could face pressure.

Q2 Guidance Tops Estimates, Announces 8-for-1 Stock Split

SanDisk expects fiscal second-quarter 2027 revenue to be $12.2 billion to $12.6 billion and non-GAAP EPS to be $55 to $57, with the guidance midpoints above market expectations of approximately $12.31 billion and $53.60, respectively. Note that the above EPS figures are on a pre-stock-split basis.

The company also announced an 8-for-1 stock split. For shareholders of record as of the close on November 9, the company plans to issue seven additional shares for every share held after the close on November 19, with split-adjusted trading expected to begin at the market open on November 20. This stock split will not change the company's total market capitalization or shareholders' ownership percentages.

Overall, SanDisk's data center business grew strongly, and its performance guidance for the next quarter also exceeded expectations. However, revenue growth, NAND price trends, and whether high gross margins can be maintained remain key focuses for investors.

Meanwhile, Intel (INTC) saw its stock price plunge 25% after earnings, and overall weakness in the semiconductor sector also put SanDisk under greater pressure from sector volatility.

Disclaimer: For information purposes only. Past performance is not indicative of future results.
placeholder
Tesla jumps 5% as Barclays puts a $450 target on the SpaceX merger — the chart was already pointing to 431Tesla closed at $391.62 on October 26, up 5.21%, after Barclays upgraded the stock to Overweight and lifted its target to $450 from $370, citing a sharp inflection in Robotaxi miles and a potential SpaceX merger. The move also completed a double bottom at $345.88 and $349.33, with a neckline at $388.56 and a measured target of $431.24. Here is what the upgrade actually says, why the chart and the analyst now point the same way, and what would break the target.
Author  Irene Q.
Oct 27, Tue
Tesla closed at $391.62 on October 26, up 5.21%, after Barclays upgraded the stock to Overweight and lifted its target to $450 from $370, citing a sharp inflection in Robotaxi miles and a potential SpaceX merger. The move also completed a double bottom at $345.88 and $349.33, with a neckline at $388.56 and a measured target of $431.24. Here is what the upgrade actually says, why the chart and the analyst now point the same way, and what would break the target.
placeholder
Anthropic files for a $2 trillion IPO — the $80.7 billion loss is the decoy, the $450 billion compute bill is the riskAnthropic publicly filed its S-1 on October 26, revealing $16.29 billion of first-half revenue (+1,304% year over year) and a $80.7 billion net loss — of which $72.4 billion is a non-cash convertible-note charge. The real number is the $450 billion of signed, mostly non-cancelable compute commitments. Here is what the filing says, why NVDA, ARM and MU are the tradeable read-through, and the conditions that decide whether the AI trade passes its first public valuation test.
Author  Irene Q.
Oct 27, Tue
Anthropic publicly filed its S-1 on October 26, revealing $16.29 billion of first-half revenue (+1,304% year over year) and a $80.7 billion net loss — of which $72.4 billion is a non-cash convertible-note charge. The real number is the $450 billion of signed, mostly non-cancelable compute commitments. Here is what the filing says, why NVDA, ARM and MU are the tradeable read-through, and the conditions that decide whether the AI trade passes its first public valuation test.
placeholder
Brent's $115 front month sits $4.6 above January — the $14 spread to WTI is the supply-risk premiumDecember Brent trades at $115.29 while January is $110.71, a $4.58 backwardation. The December Brent-WTI spread is $14.2, versus a $3-5 normal. That gap, not the headline, is where the Middle East supply risk is priced. Here is what the curve says, why the December contract's expiry on October 30 will mechanically cut the headline by $4.6, and the 108.81 neckline that decides the next move.
Author  Irene Q.
Oct 28, Wed
December Brent trades at $115.29 while January is $110.71, a $4.58 backwardation. The December Brent-WTI spread is $14.2, versus a $3-5 normal. That gap, not the headline, is where the Middle East supply risk is priced. Here is what the curve says, why the December contract's expiry on October 30 will mechanically cut the headline by $4.6, and the 108.81 neckline that decides the next move.
placeholder
Gold Price Analysis Today | Forex Gold Analysis | XAU/USD Analysis - October 29, 2026Get the latest gold price analysis, forex gold insights, and XAU/USD analysis for October 29, 2026. Read on for the details.
Author  Mitrade
Yesterday 02: 06
Get the latest gold price analysis, forex gold insights, and XAU/USD analysis for October 29, 2026. Read on for the details.
placeholder
Gold Price Analysis Today | Forex Gold Analysis | XAU/USD Analysis - October 30, 2026Get the latest gold price analysis, forex gold insights, and XAU/USD analysis for October 30, 2026. Read on for the details.
Author  Mitrade
13 hours ago
Get the latest gold price analysis, forex gold insights, and XAU/USD analysis for October 30, 2026. Read on for the details.
goTop
quote