The Fed held at 3.75%–4.00% — and two officials voted to hike. December is now 85% priced
coverImg
Source: DepositPhotos

Mitrade Insights — The Federal Reserve kept its target range at 3.75%–4.00% on Wednesday, but the vote was 10–2 and both dissenters wanted a 25 basis point hike. Governor Lisa Cook and Cleveland Fed President Beth Hammack broke with the majority. Chair Kevin Warsh refused to offer forward guidance or a dot plot, and the market did something that looks contradictory: it raised the odds of a December hike to 85%–87% while the 2-year Treasury yield fell 8 basis points to 4.70% and the dollar slipped to 101.84.
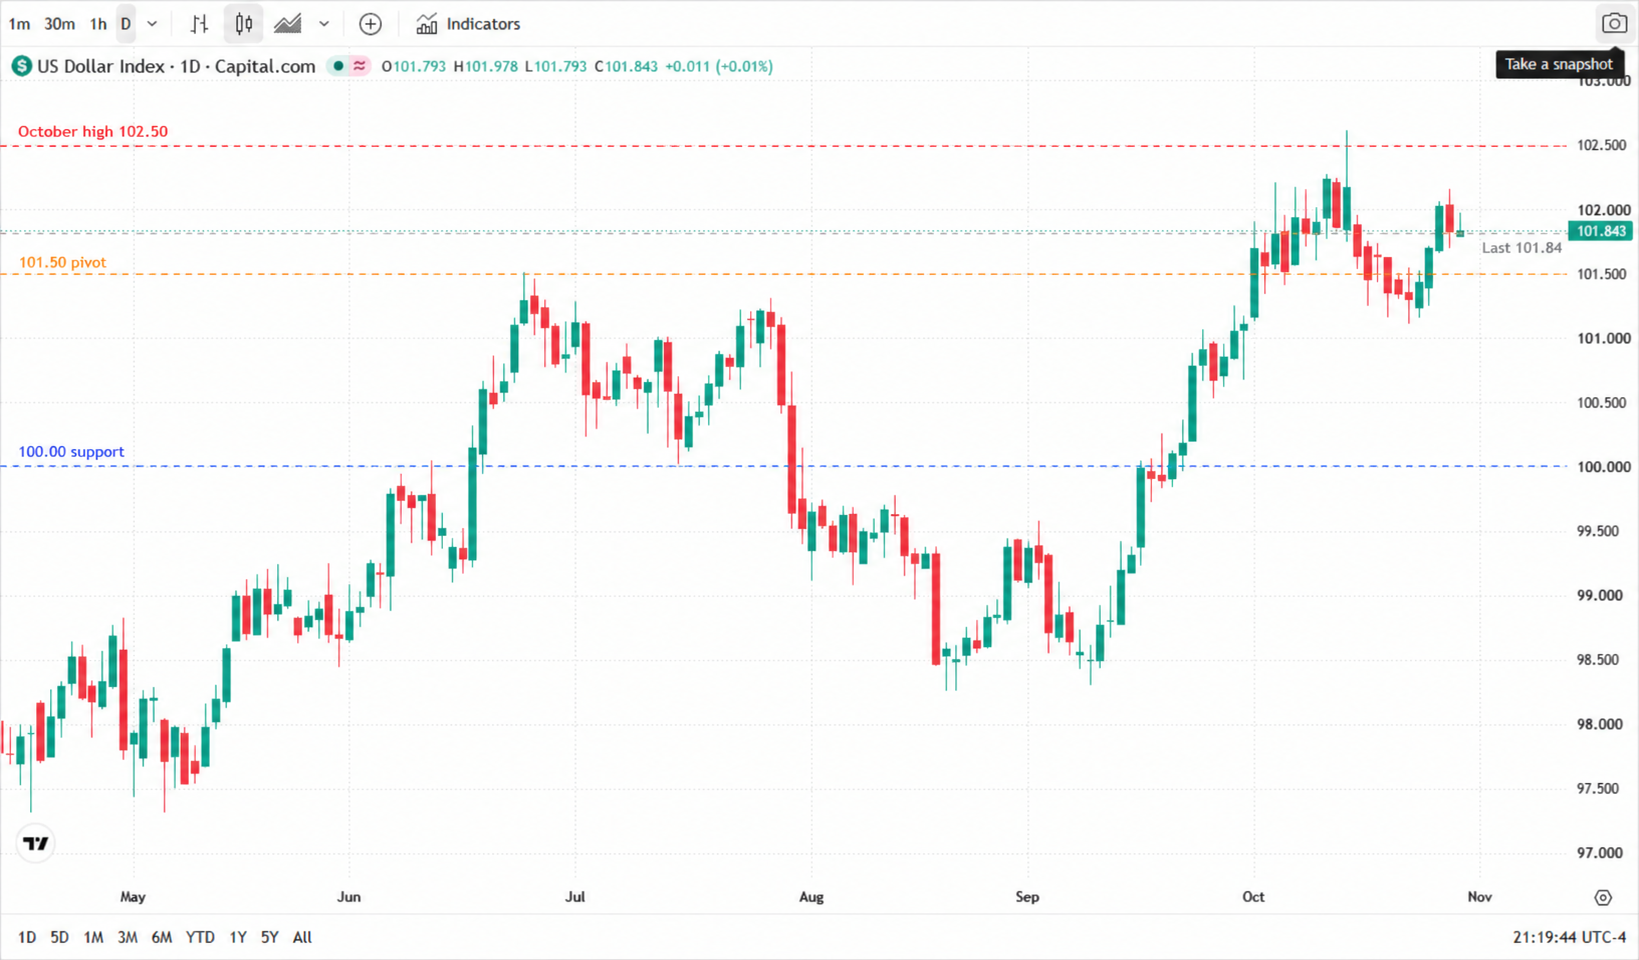
US Dollar Index (DXY) daily chart, May to October 2026, with the October high at 102.50, the 101.50 pivot, the 100.00 support and the current 101.84 marked by dashed lines aligned to the price axis. The chart shows a rally from around 98.0 in August to 102.5 in October, followed by a pullback to 101.84 after the Fed's 10–2 hold.

* Chart source: TradingView (US Dollar Index, Capital.com).

The 10–2 vote: Cook broke ranks

The headline is the hold. The story is the vote. Hammack's dissent was expected — she had already voted for tighter policy in April and July. Cook's was not. A Board governor breaking with the Chair carries more weight than a regional president doing so, and this was her first dissent since joining the Board. It tells you the hawkish bloc is no longer confined to the usual district presidents.

Why the 2-year fell 8bp

Because the market had priced a more hawkish hold than it got. Warsh said the Committee would "deliver price stability" and described activity as expanding at a "strong pace", but he explicitly declined to guide the market toward December and did not submit a dot-plot projection. He also announced that the Fed will cut its rate-setting meetings from eight to seven a year from 2027, and to six from 2028. In a market that wanted a clear "December is live" signal, the absence of one was read as a small dovish surprise at the front end. The 2-year fell to 4.70%; the 10-year stayed at 5.045%.

The dollar at 101.84

The dollar index had run to the 102.50 area in mid-October. It closed Wednesday at 101.84, below that ceiling. That is not a collapse; it is a market that has already priced a lot of tightening and is unwilling to add before it sees the data. The levels are simple: 102.50 is the October high, 101.50 is the pivot of the October range, and 100.00 is the round-number support.

December at 85%: the 08:30 ET referee

The December debate now hinges on two numbers due at 08:30 ET today: Q3 GDP and September core PCE. Consensus is for GDP at 3.1% annualised, up from 2.2% in Q2, and core PCE at +0.3% m/m and +3.1% y/y, up from 3.0%. Headline PCE is expected at +0.5% m/m and +3.7% y/y. A hot core print would validate the two dissents and push December odds toward 90%; a soft one would revive the "one and done" argument.

IndicatorConsensusPreviousWhy it matters
Q3 GDP (advance)+3.1%+2.2%A strong economy gives the Fed room to hike
Core PCE m/m+0.3%+0.2%The monthly pace the Fed watches
Core PCE y/y+3.1%+3.0%Still 110bp above the 2% target
Headline PCE y/y+3.7%+3.4%Energy pass-through is back

BoC hiked, ECB holds, BOJ waits

The dollar is also being priced against its peers. The Bank of Canada hiked 25bp to 2.50% on Wednesday, its first increase in more than three years. The ECB is expected to hold at 2.50% today, with December hike odds near 84%. The Bank of Japan is expected to hold at 1.25% on Friday. If the Fed pauses while the BoC hikes and the ECB keeps a tightening bias, the dollar's rate differential stops widening — that is the bear case for the dollar, and the bull case for gold.

The bull case: two dissents, core PCE at 3.1%, GDP at 3.1%, December at 85%, and a terminal rate debate moving toward 4.25%–4.50%. The dollar holds 101.50 and retests 102.50.

The bear case: the 2-year has already turned, Warsh has removed forward guidance, the meeting calendar is being cut, and the Fed is closer to the end of the cycle than the start. A soft core PCE print sends the dollar through 101.50 and opens 100.00.

Neither side gets a clean win before 08:30 ET. That is the point of a 10–2 hold: the vote tells you the direction of the debate, not the outcome.

Read more

  • US Sept. PCE Preview: Inflation May Heat Up Again, How Will US Stocks, the Dollar, and Gold React?
  • Gold rises above $4,050 ahead of Fed rate decision
  • Note: If you want to share the article 《The Fed held at 3.75%–4.00% — and two officials voted to hike. December is now 85% priced》, make sure you retain the original link. For more information, please visit Insights or browse www.mitrade.com.


    Before making any trading decisions, it is important to equip yourself with sufficient fundamental knowledge, have a comprehensive understanding of market trends, be aware of risks and hidden costs, carefully consider investment targets, level of experience, risk appetite, and seek professional advice if necessary.


    Furthermore, the content of this article is solely the author's personal opinion and does not necessarily constitute investment advice. The content of this article is for reference purposes only, and readers should not use this article as a basis for any investment decisions.


    Investors should not rely on this information as a substitute for independent judgment or make decisions solely based on this information. It does not constitute any trading activity and does not guarantee any profits in trading.


    If you have any inquiries regarding the data, information, or content related to Mitrade in this article, please contact us via email: insights@mitrade.com. The Mitrade team will carefully review the content to continue improving the quality of the article.


    goTop
    quote
    Related Articles
    placeholder
    The Fed will sit still on October 28 — but 100 of 100 economists now expect a December hikeA Reuters poll run October 16-20 found 94 of 100 economists expecting the Fed to hold at 3.75-4.00% on October 28 — and all 100 expecting a hike in December, against less than half a month earlier. The market is close to the same price, with CME FedWatch at roughly 17% for October and 82.8% for December. With the Fed in blackout since October 17, here are the five dates that decide the rest of the year, what each one is priced for, and the two directions each can take.
    Author  Irene Q.
    Oct 22, Thu
    A Reuters poll run October 16-20 found 94 of 100 economists expecting the Fed to hold at 3.75-4.00% on October 28 — and all 100 expecting a hike in December, against less than half a month earlier. The market is close to the same price, with CME FedWatch at roughly 17% for October and 82.8% for December. With the Fed in blackout since October 17, here are the five dates that decide the rest of the year, what each one is priced for, and the two directions each can take.
    placeholder
    Dollar presses 102 as the 10-year yield sits at 5.14% — and October hike odds are only 17%The dollar index closed at 101.99 (+0.20%) on Monday after briefly topping 102.07, while the 10-year Treasury yield rose to 5.14% and the 2-year hit 4.774% — yet futures price only about a 17% chance of a hike at the October 27-28 FOMC, versus roughly 90% for December. The driver is a global bond selloff, not a Fed repricing: France's 10-year OAT jumped to 4.84% ~ 4.94% and the OAT-Bund spread widened to 140 ~ 146bp. Here are the levels, the cross-asset read-through and what to watch.
    Author  Irene Q.
    Oct 20, Tue
    The dollar index closed at 101.99 (+0.20%) on Monday after briefly topping 102.07, while the 10-year Treasury yield rose to 5.14% and the 2-year hit 4.774% — yet futures price only about a 17% chance of a hike at the October 27-28 FOMC, versus roughly 90% for December. The driver is a global bond selloff, not a Fed repricing: France's 10-year OAT jumped to 4.84% ~ 4.94% and the OAT-Bund spread widened to 140 ~ 146bp. Here are the levels, the cross-asset read-through and what to watch.
    placeholder
    Gold retests $4,200 as dollar and yields retreat — can bullion clear its hardest level?Spot gold traded near $4,175 on Monday (+0.23%), with an intraday high of $4,187.71 after last week's $4,073 ~ $4,217 range; COMEX futures briefly topped $4,200. The dollar slipped to 101.76 and 10-year yields eased from their highs, but October Fed hike odds near 52% and BofA's sub-$4,000 call still cap the upside. Here are the drivers, the levels and what would flip the script.
    Author  Irene Q.
    Oct 19, Mon
    Spot gold traded near $4,175 on Monday (+0.23%), with an intraday high of $4,187.71 after last week's $4,073 ~ $4,217 range; COMEX futures briefly topped $4,200. The dollar slipped to 101.76 and 10-year yields eased from their highs, but October Fed hike odds near 52% and BofA's sub-$4,000 call still cap the upside. Here are the drivers, the levels and what would flip the script.
    placeholder
    US September CPI recap: inflation hits 3.7% as core runs hot — is an October Fed hike back on the table?September CPI landed hot: headline 3.7% y/y, core 2.6% y/y and 0.3% m/m. October hike odds jumped from ~22% to ~37% — yet the dollar faded to 101.74, gold closed higher and the S&P 500 fell 1.11%. Here is the full repricing, the levels and what to watch next.
    Author  Irene Q.
    Oct 15, Thu
    September CPI landed hot: headline 3.7% y/y, core 2.6% y/y and 0.3% m/m. October hike odds jumped from ~22% to ~37% — yet the dollar faded to 101.74, gold closed higher and the S&P 500 fell 1.11%. Here is the full repricing, the levels and what to watch next.
    placeholder
    Yen inches toward 159 as Tokyo reopens — where is the line in the sand before 160?USD/JPY traded around 158.5 on Tuesday after Monday's 158.60 close — the highest since September 24 — as Tokyo reopened and the market re-focused on two dates dominating the yen calendar: the G20 finance ministers' meeting in Bangkok on October 15 and the Bank of Japan's October 30 decision. Here are the three forces leaning on the yen, the positioning picture, and the scenarios into Wednesday's US CPI.
    Author  Irene Q.
    Oct 13, Tue
    USD/JPY traded around 158.5 on Tuesday after Monday's 158.60 close — the highest since September 24 — as Tokyo reopened and the market re-focused on two dates dominating the yen calendar: the G20 finance ministers' meeting in Bangkok on October 15 and the Bank of Japan's October 30 decision. Here are the three forces leaning on the yen, the positioning picture, and the scenarios into Wednesday's US CPI.
    Live Quotes
    Name / SymbolChart% Change / Price
    USDOLLAR-F
    USDOLLAR-F
    0.00%0.00
    US500
    US500
    0.00%0.00