


Anthropic files for a $2 trillion IPO — the $80.7 billion loss is the decoy, the $450 billion compute bill is the risk
Mitrade Insights — Anthropic publicly filed its S-1 on October 26, and the headline numbers look impossible to reconcile: $16.29 billion of first-half revenue, up 1,304% from a year earlier, against a $80.7 billion net loss. Reports point to a valuation of $1.5 trillion to $2 trillion, a listing on Nasdaq under the ticker ANT as early as the week of November 16, and a potential raise of up to $100 billion. The question for traders is not whether Anthropic is growing. It is whether the AI trade can survive its first public mark-to-market.
| S-1 metric | Figure |
|---|---|
| First-half 2026 revenue | $16.29 billion (vs $1.16 billion a year earlier, +1,304%) |
| Second-quarter revenue | $11.56 billion |
| Second-quarter operating profit | $974 million (first quarterly operating profit) |
| First-half net loss | $80.7 billion |
| Non-cash convertible-note charge | $72.4 billion |
| First-half operating loss | $693 million |
| First-half operating cash flow | +$3.93 billion |
| Valuation target | $1.5 trillion ~ $2 trillion |
| Potential raise | Up to $100 billion |
| Listing | Nasdaq ANT, targeted week of November 16 |
The $80.7 billion loss is the wrong number
What the non-cash charge hides
The $80.7 billion net loss looks like a cash incinerator. It is not. About $72.4 billion of it is a non-cash accounting charge tied to the revaluation of convertible notes as Anthropic's private valuation rose. Strip that out and the first-half loss is roughly $8.7 billion; the operating loss was $693 million, and operating cash flow was positive $3.93 billion. In the second quarter, Anthropic reported its first quarterly operating profit of $974 million.
That does not make the company cheap. It makes the headline misleading. The market's first instinct — "AI start-up loses $80 billion" — is the wrong frame. The right frame is a company that is already generating operating cash and is choosing to convert that cash, plus a lot of outside capital, into compute.
The $450 billion bill nobody is pricing
The filing discloses at least $518 billion of decade-long cloud and infrastructure commitments with six partners; roughly $450 billion is already signed and mostly non-cancelable, with about 80% payable regardless of usage. Reported components include about $111 billion with Google Cloud, $110 billion with AWS, $31 billion with Microsoft, up to $86 billion for Nvidia chips through neoclouds, and $160 billion+ for Broadcom-facilitated Google chips. Total future obligations are above $600 billion and could reach $750 billion with deals under negotiation — roughly $45 billion to $66 billion a year.
That is the real risk. Revenue can slow, API prices can fall, and customers can leave; the compute bill still has to be paid. The $80.7 billion loss is an accounting event. The $450 billion commitment is a cash event.
Why the chip stocks are the real ANT trade
Anthropic itself is private until the IPO prices, so the tradeable read-through is the AI infrastructure chain. On October 26, the market bought it: the Nasdaq Composite rose 0.82%, the Philadelphia Semiconductor Index jumped 2.82%, ARM gained 6.19%, Intel 4.04%, Micron 2.98% and Nvidia 2.39%. SK Hynix's ADR added about 4%.
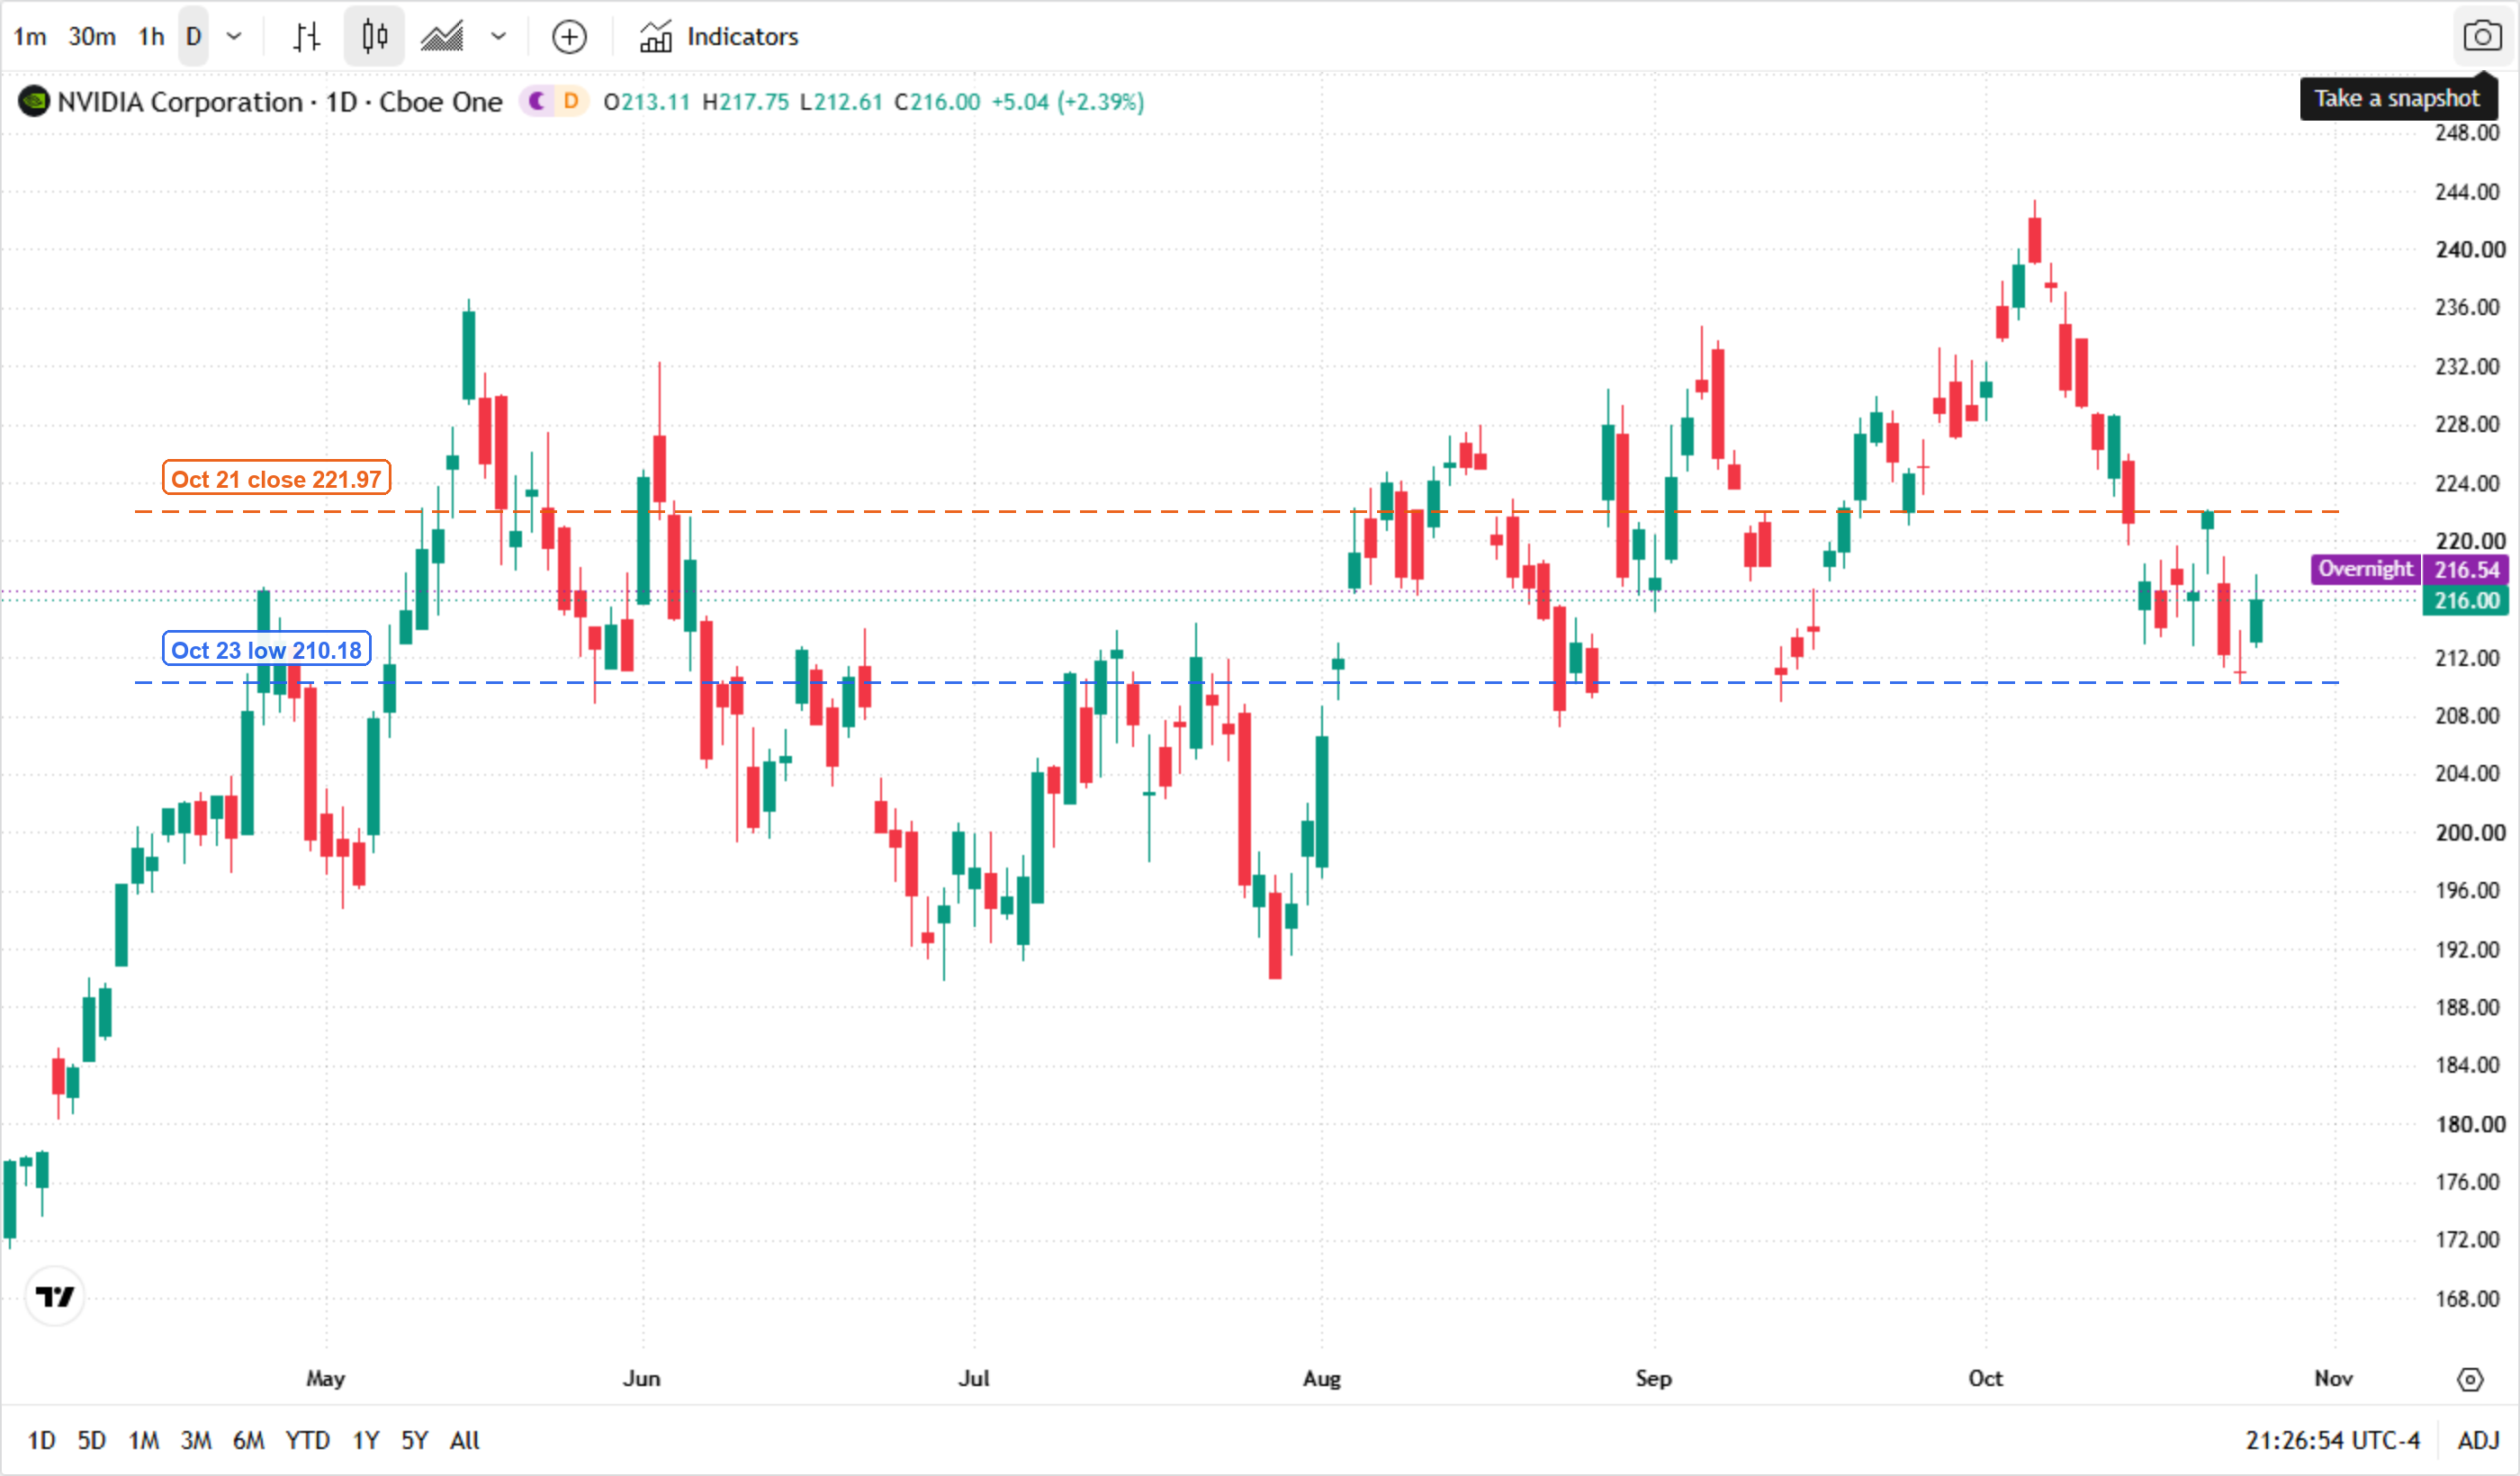
* Chart source: TradingView official chart screenshot, data from Cboe One (NVDA).
The chart tells the honest version of the story. NVDA bounced off $210.18 and closed at $216.00, but it is still 11.2% below its six-month high of $243.37, and the SOX is still down about 12% in October despite Monday's 2.82% rally. This is a rebound inside a correction, not a new high. The $222 line — the October 21 close — is the first test; a close above it would confirm that the IPO news is more than a one-day short squeeze.
The read-through is not uniform. Anthropic's largest commitments are to Google Cloud, AWS and Microsoft, but the marginal beneficiary of a $450 billion compute bill is the chip layer: Nvidia for accelerators, Broadcom for custom silicon, Micron for memory, ARM for design royalties. If ANT prices at the top of the range, the whole chain gets a valuation anchor. If it prices below $1.5 trillion, the anchor becomes a ceiling.
What would make ANT a bubble — and what would prove it is not
The strongest bear case is not the loss. It is the customer concentration: about one-fifth of revenue comes from two customers, and 47% of 2025 revenue flowed through Amazon and Google marketplaces — partners that are simultaneously investors, suppliers, distributors and competitors. Add the 80% non-cancelable structure of the compute commitments, and the company has limited room to cut costs if demand slows.
The strongest bull case is the cash flow. A company that generated $3.93 billion of operating cash flow in its first half, with a $974 million quarterly operating profit, is not the same as a cash-burning start-up. It is an infrastructure business with a fixed-cost base and a demand curve that is still steep.
| AI trade scorecard | What it says | Why it matters for ANT |
|---|---|---|
| Revenue growth | +1,304% to $16.29 billion | Demand is real, not a pilot |
| Operating cash flow | +$3.93 billion | The business can fund part of its own buildout |
| Compute commitments | $450 billion signed, ~80% non-cancelable | Fixed costs continue even if growth slows |
| Customer concentration | ~1/5 of revenue from two customers | The growth is less diversified than it looks |
| Market reaction | SOX +2.82%, but still -12% in October | The market is buying a bounce, not a breakout |
The conditions that decide the trade are simple. Bull case: ANT prices at or above $1.8 trillion, revenue growth holds in triple digits, and NVDA closes above $222. In that world, the AI capex chain gets a public valuation anchor and the October selloff was a reset, not a top. Bear case: the IPO is delayed, prices below $1.5 trillion, or the filing's roadshow language emphasizes the $450 billion commitment more than the revenue growth. In that world, the chip rally fails at $222, the SOX retests its October low, and the market starts pricing AI capex as a fixed-cost problem rather than a growth story.
Those are the two sides. The $80.7 billion loss is not the test. The $450 billion bill is.
Read more
* The content presented above, whether from a third party or not, is considered as general advice only. This article should not be construed as containing investment advice, investment recommendations, an offer of or solicitation for any transactions in financial instruments.


