




Monday.com vs. Okta: Which Tech Stock Is a Better Buy for 2027?
Key Points
Monday.com is expanding its AI-driven platform to move beyond basic work management into CRM and software development.
Okta maintains a strong foothold in the critical identity security market, serving a large portion of the Fortune 100.
Which software leader offers the better combination of growth and value for your portfolio heading into 2027?
- 10 stocks we like better than Monday.com ›
As digital transformation evolves, many investors weigh high-growth software platforms against established security leaders. Deciding between Monday.com (NASDAQ:MNDY) and Okta (NASDAQ:OKTA) requires balancing rapid expansion against critical infrastructure stability.
Monday.com offers a highly flexible work operating system that allows businesses to build custom applications without writing code. Okta specializes in identity management, ensuring that only the right people have access to specific corporate systems. Both companies are vital to modern workforces but serve different niches within the software market.
The case for Monday.com
Monday.com provides an AI-powered work platform designed to help teams manage projects, sales cycles, and software development tasks in one place. As businesses prioritize efficiency, many are turning to tech companies that offer versatile software-as-a-service solutions. Monday.com serves roughly 250,000 customers globally, focusing on a multi-product strategy that encourages users to adopt its CRM and service tools alongside core management features.
In the 12 months ended Sept. 30, 2026, revenue reached nearly $1.4 billion, reflecting a growth rate of approximately 22.4%. This expansion helped the company achieve net income of close to $143.4 million during the same period. The transition from a single-product tool to a comprehensive enterprise platform has been a primary driver of this financial performance.
As of Monday.com's December 2025 balance sheet, the current ratio stands at roughly 2.5. This ratio measures a company's ability to cover its short-term obligations with assets that can be converted to cash within one year. The debt-to-equity ratio, which compares total debt to shareholder equity, is approximately 0.3. In the fiscal year ended Dec. 31, 2025, free cash flow was nearly $309.9 million. Note that stock-based compensation accounted for roughly 53.1% of operating cash flow, inflating reported cash generation, since SBC is a non-cash expense added back in the cash flow statement.
The case for Okta
Okta serves as a foundational layer for enterprise security by providing identity and access management solutions. The platform helps more than 19,300 organizations secure their employees and customers across various cloud and on-premises environments. To strengthen its ecosystem, Okta maintains deep integrations with major providers like Amazon (NASDAQ:AMZN), ServiceNow (NYSE:NOW), and Salesforce (NYSE:CRM).
In the 12 months ended July 31, 2026, revenue reached close to $3.1 billion, an increase of approximately 11.2%. The company reported a net income of nearly $296 million during this time frame. While its growth has moderated compared to previous years, the company continues to benefit from the essential nature of cybersecurity spending.
As of Okta's January 2026 balance sheet, the debt-to-equity ratio was approximately 0.1. This indicates a relatively low level of debt used to finance the company's assets compared to its equity. The current ratio stands at roughly 1.4, suggesting a sufficient cushion for short-term liabilities. In the fiscal year ended Jan. 31, 2026, free cash flow was approximately $863 million. Note that stock-based compensation represented roughly 61.5% of operating cash flow.
Risk profile comparison
Monday.com faces significant competition from well-capitalized rivals in the productivity software space. While the platform is versatile, it must compete against established tools from Microsoft (NASDAQ:MSFT) and Atlassian (NASDAQ:TEAM). If enterprise spending on new software licenses slows due to macroeconomic pressures, the company could see a deceleration in user acquisition. Additionally, maintaining high growth requires constant investment in research and development to stay ahead of rapidly evolving artificial intelligence trends.
Okta operates in a crowded security market, competing with large infrastructure providers such as Microsoft. Any cybersecurity vulnerability or breach of Okta's own systems could severely damage its brand reputation and trust among enterprise clients. The company also depends on the retention and expansion of its existing customer base to sustain revenue growth. Operational risks include the complex task of integrating identity solutions across a vast array of third-party platforms and mobile hardware.
Valuation comparison
Based on its significantly lower earnings multiples and sales-based valuation, Monday.com appears to be the more attractively priced option compared to Okta.
| Metric | Monday.com | Okta |
|---|---|---|
| Forward P/E | 10.9 | 52.7 |
| P/S ratio | 2.1 | 11.3 |
Valuation metrics include sourcing from Financial Modeling Prep (FMP) and may differ from other data providers.
Which stock would I buy for 2027?
It's certainly an interesting time to be picking stocks given the market's recent meltdown. Tech stocks have been hit especially hard year to date:
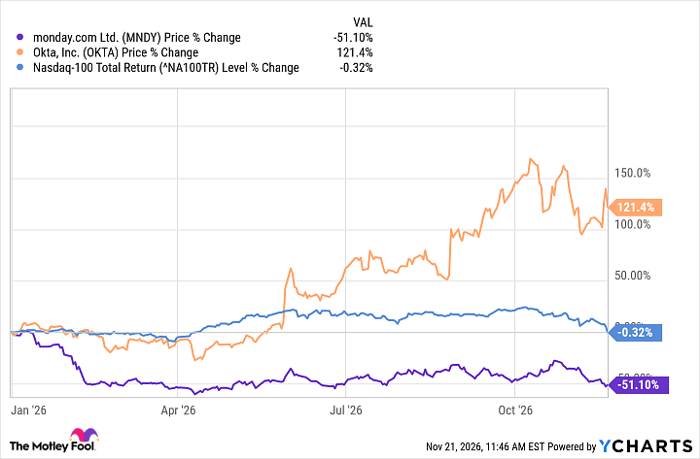
MNDY data by YCharts
Okta and Monday.com are reporting roughly similar net margins, but the latter is seeing stronger revenue growth. That said, I think Okta is more attractive here. Monday.com has to compete with the likes of Microsoft and Atlassian, which is a tough proposition. Microsoft's software is ubiquitous and entrenched. Furthermore, I think Okta offers a stickier product. The company provides critical software to maintain organizational security and identity management. It's more important than ever for companies to lock down data for reputational, regulatory, and legal reasons. Cybersecurity isn't a "nice to have"; it's a pivotal need for any organization. I'm not convinced Monday.com's offerings are equally necessary.
Finally, while past performance is no indication of future results, Okta stock has put in a stronger showing so far this year. Okta gets my vote for 2027 and beyond.
Should you buy stock in Monday.com right now?
Before you buy stock in Monday.com, consider this:
The Motley Fool Stock Advisor analyst team just identified what they believe are the 10 best stocks for investors to buy now… and Monday.com wasn’t one of them. The 10 stocks that made the cut could produce monster returns in the coming years.
Consider when Netflix made this list on December 17, 2004... if you invested $1,000 at the time of our recommendation, you’d have $305,941!* Or when Nvidia made this list on April 15, 2005... if you invested $1,000 at the time of our recommendation, you’d have $771,325!*
Now, it’s worth noting Stock Advisor’s total average return is 719% — a market-crushing outperformance compared to 192% for the S&P 500. Don't miss the latest top 10 list, available with Stock Advisor, and join an investing community built by individual investors for individual investors.
See the 10 stocks »
*Stock Advisor returns as of November 22, 2026.
Erin Kennedy has no position in any of the stocks mentioned. The Motley Fool has positions in and recommends Amazon, Atlassian, Microsoft, Monday.com, Okta, Salesforce, and ServiceNow. The Motley Fool has a disclosure policy.
Recommended Articles


