




Nvidia Just Issued a Major Warning to AMD and Intel Stock Investors
Key Points
Nvidia is seeing phenomenal demand for its Vera server CPUs, which are being deployed by multiple hyperscalers and AI companies.
Nvidia expects sales of its Vera CPUs to more than double next year.
Intel and AMD are the dominant players in the server CPU market, and Nvidia's growth in this market suggests that they may feel the heat next year.
- Motley Fool Issues Rare "Total Conviction" Buy Alert ›
Nvidia (NASDAQ:NVDA) released solid results for the third quarter of fiscal 2027 (which ended on Oct. 25) on Nov. 17 and backed its outstanding performance with impressive guidance.
Its data center business recorded healthy growth once again last quarter, and Nvidia's upgraded guidance for fiscal 2028 suggests that the segment will continue to move the needle substantially next year. However, a closer look at Nvidia's results suggests it is quickly gaining ground in a market where Intel (NASDAQ:INTC) and Advanced Micro Devices (NASDAQ:AMD) are the dominant players.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Let's take a closer look at this particular business and check why Nvidia's progress in this space doesn't bode well for Intel and AMD.

Image source: Nvidia.
Nvidia's Vera CPUs are in terrific demand
The market for server central processing units (CPUs) has been growing rapidly amid the increasing adoption of agentic AI and inference applications. This explains why Nvidia decided earlier this year to offer its latest-generation Vera server CPUs as a stand-alone product to customers.
The company already had a server CPU before Vera, known as Grace, but it was available as part of rack-scale systems that integrated graphics cards, networking chips, memory, and other components into a single package. Nvidia's latest quarterly report is proof that its move into the stand-alone server CPU market is paying off.
The product has been adopted by leading hyperscalers, neocloud providers, and AI companies, including Oracle, Meta Platforms, OpenAI, CoreWeave, Nebius, and others. In fact, Nvidia has doubled down on the server CPU market by offering a CPU-based rack-scale server platform to handle agentic AI and inference applications.
Interim CEO Colette Kress remarked on the latest earnings call:
We continue to see very strong demand for Vera and expect total CPU revenue to more than double in fiscal year 2028.
Though the company didn't specify exactly how much revenue it generated from stand-alone sales of the Vera CPU last quarter, it noted on the fiscal Q1 earnings call that it expects $20 billion in revenue from this product in fiscal 2027. Assuming the estimate is still intact, Nvidia's Vera VPU revenue could jump to at least $40 billion next fiscal year.
This should set the alarm bells ringing for AMD and Nvidia investors.
AMD and Intel's fast-growing server CPU business could be under threat
At its Financial Analyst Day held in November last year, AMD predicted that the data center CPU market will be worth $26 billion. The company's 2030 server CPU estimate was $60 billion a year ago, suggesting a compound annual growth rate (CAGR) of 18% for the next five years.
However, AMD has significantly upgraded its 2030 server CPU estimate. It noted earlier this year that the server CPU market could generate $220 billion in revenue in 2030, clocking a CAGR of more than 50%. The good part is that AMD is making the most of this opportunity. It expects server CPU revenue to more than double in 2027.
On the other hand, Intel's data center and AI (DCAI) revenue increased by 78% year over year in Q3 to $7.3 billion, driven by record demand for its Xeon server CPUs. Intel expects server CPU shipments to increase by 30% in 2026 and 2027. These numbers from Intel and AMD suggest that Nvidia is quickly becoming more influential on their turf, which is a big deal considering that it entered the stand-alone server CPU market just this year.
We have already seen that AMD anticipates server CPU market revenue to grow at a 50% CAGR through 2030. Nvidia is already growing at double the pace of this market, giving tough competition to AMD. Intel, however, could be the bigger loser from Nvidia's entry into server CPUs, as the latter is already forecasting significantly stronger growth in this market.
So, even though Nvidia has fallen out of favor on Wall Street lately, its strong growth indicates it is a solid buy right now, especially given its attractive valuation relative to peers.
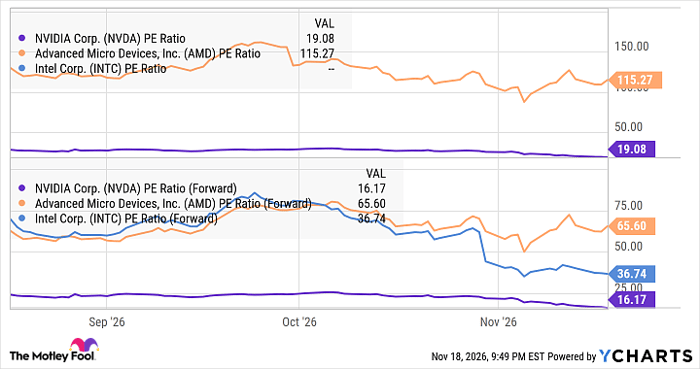
NVDA PE Ratio data by YCharts
Notably, Nvidia has increased its fiscal 2028 revenue growth forecast to 75% from the earlier expectation of 70%, citing growing demand for its chips, including the Vera CPU. The healthy revenue growth will translate into a robust increase in earnings per share as well.
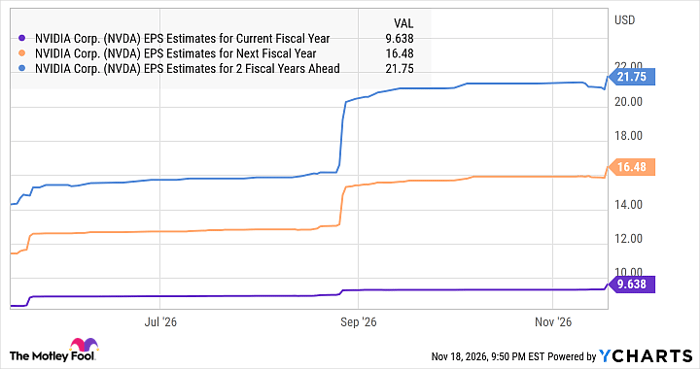
NVDA EPS Estimates for Current Fiscal Year data by YCharts
So, Nvidia looks like the best bet among these three semiconductor stocks right now, as its terrific earnings growth potential and attractive valuation are poised to drive further stock price upside.
Should you buy stock in Nvidia right now?
Before you buy stock in Nvidia, consider this:
The Motley Fool Stock Advisor analyst team just identified what they believe are the 10 best stocks for investors to buy now… and Nvidia wasn’t one of them. The 10 stocks that made the cut could produce monster returns in the coming years.
Consider when Netflix made this list on December 17, 2004... if you invested $1,000 at the time of our recommendation, you’d have $315,271!* Or when Nvidia made this list on April 15, 2005... if you invested $1,000 at the time of our recommendation, you’d have $896,981!*
Now, it’s worth noting Stock Advisor’s total average return is 768% — a market-crushing outperformance compared to 198% for the S&P 500. Don't miss the latest top 10 list, available with Stock Advisor, and join an investing community built by individual investors for individual investors.
See the 10 stocks »
*Stock Advisor returns as of November 21, 2026.
Harsh Chauhan has no position in any of the stocks mentioned. The Motley Fool has positions in and recommends Advanced Micro Devices, Intel, Meta Platforms, Nvidia, and Oracle. The Motley Fool has a disclosure policy.
Recommended Articles


