


Disney Earnings Preview: EPS Expected to Rise 50% YoY, Wall Street Targets Above $150
TradingKey - Disney's streaming profits ignite as EPS is poised to surge 50% year-over-year, with Wall Street's highest price target pointing to $151.
On November 17, Eastern Time, The Walt Disney Company (DIS) will officially release its fourth-quarter earnings report for fiscal 2026 before the U.S. market opens. Following multiple quarters of transitional adjustments and business restructuring, Wall Street has high expectations for Disney's upcoming results, anticipating explosive fourth-quarter adjusted EPS growth of over 50% year-over-year, while the highest analyst 12-month price target points toward $151.20.
According to the latest consensus estimates from Zacks, TipRanks, and multiple Wall Street firms, Disney's key Q4 financial metrics point to double-digit revenue growth and a substantial earnings leap, as detailed below:
Core Financial Metric | Consensus Estimate | Prior-Year Actual | Estimated YoY Growth |
Total Revenue | $25.19 billion – $25.26 billion | $22.46 billion | +12.1% to +12.4% |
Adjusted EPS | $1.67 – $1.69 | $1.11 | +50.5% to +52.3% |
Disney's more than 50% EPS growth is driven by three key factors: First, the streaming segment's operating margin doubled from 5% in the prior-year period to double digits, officially transitioning from a cash drain into a stable profit driver; second, the Experiences and Parks segment benefited from cruise capacity expansion and price increases, keeping profitability elevated; and third, the company executed over $9 billion in share repurchases throughout the year, significantly reducing its share count and boosting EPS performance.
Currently, Wall Street firms hold an average 12-month price target for Disney of approximately $126.73 to $130.58, while the most bullish camp has set a Street-high target of $151, as detailed below:
Institution / Brokerage | Price Target | Core Bullish Thesis / Key Rationale |
Goldman Sachs | $151.00 | With the full rollout of the password-sharing crackdown, tiered subscription price hikes, and improved ad-tier monetization, the streaming division has turned the corner on billions of dollars in annual losses. |
Citigroup | $140.00 | Robust cash flow from the experiences, parks, and cruise businesses provides room for valuation recovery |
Wells Fargo | $132.00 | Theme park capacity expansion helps quarterly revenue surpass the $10 billion mark |
TD Cowen | $123.00 | Near-term macroeconomic consumer uncertainties remain, maintaining a neutral, wait-and-see stance |
UBS / Barclays | $115.00 | Cautious regarding consumer downtrading pressures and the high base effect following the 53rd week |
Options market pricing indicates an implied single-day move of approximately ±6.30% for Disney following the earnings release. If results beat expectations, it could propel the stock to break through its nearly four-year resistance level of $125, fully unlocking upside potential. Conversely, in the current high-rate macro environment, if fiscal 2027 guidance fails to deliver an upside surprise, investors should remain watchful for near-term profit-taking pressure.
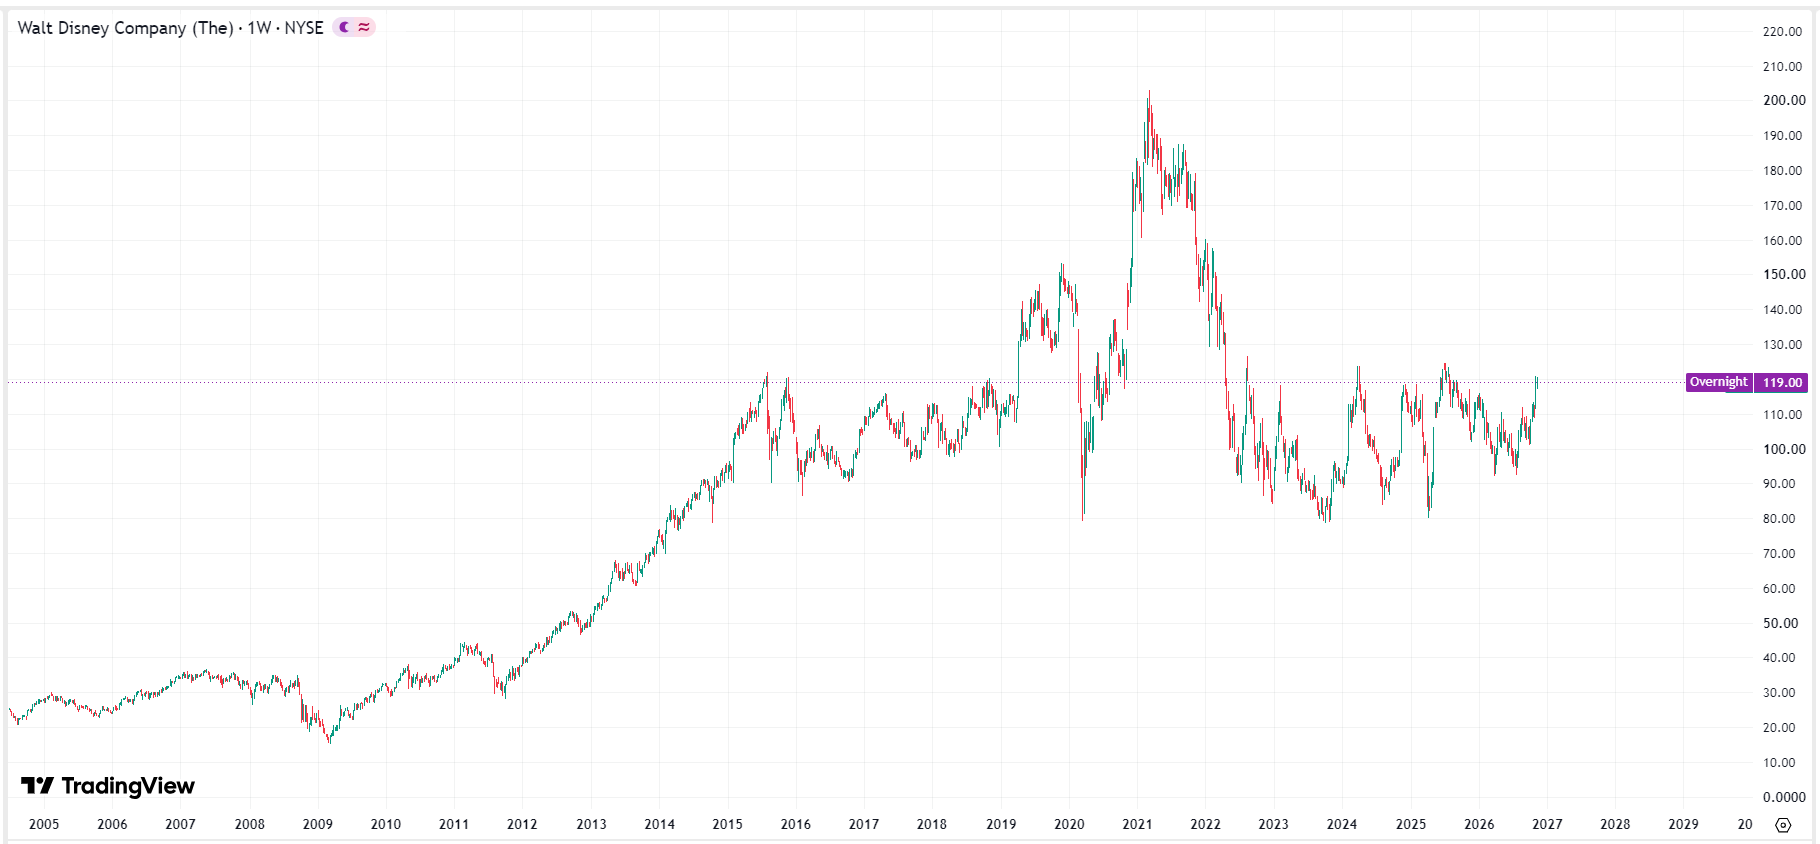 Disney price chart, Source: TradingView
Recommended Articles


