


Bloom Energy Is Down 43% From Its High. Should You Buy the Dip?
Key Points
Bloom's revenue has surged year over year, but concerns over AI spending have pressured its stock.
Bloom trades at a premium, yet rapid growth could justify buying it today.
- Motley Fool Issues Rare "Total Conviction" Buy Alert ›
Bloom Energy (NYSE:BE) had a knockout third quarter, with growth on all sides of its business. Third-quarter revenue came in at $1.24 billion, up 138% year over year, and full-year 2026 guidance was raised again, this time to a range of $4.4 billion to $4.6 billion. Bloom announced another major deal, this one with information technology services company NTT DATA, to deploy 900 megawatts of fuel cell power to its data centers across the world. If that project materializes, it will be Bloom's largest international deployment yet.

Image source: Bloom Energy.
Missed AI’s "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our analysts, we’re only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
And yet, like other stocks linked to the artificial intelligence (AI) infrastructure build-out, Bloom has seen better days in the market. The stock is down roughly 43% from its 52-week high of about $350, currently trading for about $200.
So what gives? And more importantly -- should you buy the dip?
Certainly, concerns over a potential slowdown in data center construction have weighed heavily on the clean energy stock. Since data center developers have been driving much of Bloom's extraordinary growth, any slowdown could make it harder for the company to deliver the sales that Wall Street is counting on.
Indeed, Bloom's valuation was already hard to swallow before the AI jitters hit Wall Street, and it still is, even after its decline. The stock currently trades at about 62 times its projected adjusted earnings for the year. That's much higher than for other AI industrial stocks.
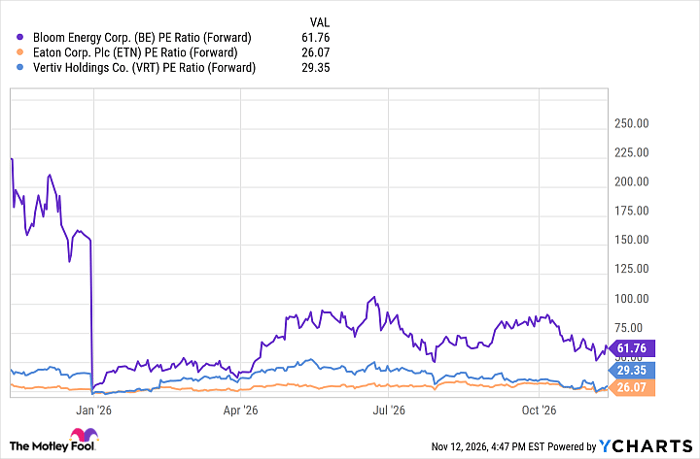
BE PE Ratio (Forward) data by YCharts
At the same time, Bloom is growing much faster than other industrial companies, with an order backlog that stands at about $20 billion. Sure, its valuation demands strong execution, but Bloom's recent results make me feel confident it can rise to the challenge. For investors willing to hold through the volatility, I think the pullback offers an opportunity to open a small position in a business with plenty of growth ahead.
Should you buy stock in Bloom Energy right now?
Before you buy stock in Bloom Energy, consider this:
The Motley Fool Stock Advisor analyst team just identified what they believe are the 10 best stocks for investors to buy now… and Bloom Energy wasn’t one of them. The 10 stocks that made the cut could produce monster returns in the coming years.
Consider when Netflix made this list on December 17, 2004... if you invested $1,000 at the time of our recommendation, you’d have $335,171!* Or when Nvidia made this list on April 15, 2005... if you invested $1,000 at the time of our recommendation, you’d have $1,000,640!*
Now, it’s worth noting Stock Advisor’s total average return is 823% — a market-crushing outperformance compared to 208% for the S&P 500. Don't miss the latest top 10 list, available with Stock Advisor, and join an investing community built by individual investors for individual investors.
See the 10 stocks »
*Stock Advisor returns as of November 15, 2026.
Steven Porrello has no position in any of the stocks mentioned. The Motley Fool has positions in and recommends Bloom Energy. The Motley Fool has a disclosure policy.
Recommended Articles


