

3 Ways Boeing Can Have a Great 2025

Tony
coverImg
Source: DepositPhotos

It's been an extremely challenging few years for Boeing (NYSE: BA), and its recovery under new CEO Kelly Ortberg isn't going to be a quick fix. Still, there's a bullish case for the stock based on a backlog of about $428 billion at Boeing commercial airplanes (BCA), $62 billion at Boeing defense, space & security (BDS), and $20 billion at its aviation services business, Boeing global services (BGS).


The backlog is there, and Boeing continues to win orders, so what can investors expect from Boeing in 2025?


Boeing's challenges and opportunities


On a practical level, it's obvious what Boeing needs to do in all three segments: continue expanding its margin at BGS while ramping production on the 737 MAX now that the strike is over. Boeing is in a position to stabilize production at an initial rate of 38 a month. Meanwhile, BDS must stem the flow of charges and losses on its problematic fixed-price projects.


All of these things are necessities for the bullish case. Still, there are a few other considerations that relate to how the company communicates with investors and helps build a narrative around the stock.


Meet the cash flow guidance


With consolidated debt of $57.7 billion and cash and marketable securities of $10.5 billion at the end of the third quarter, Boeing's last need is to see ongoing cash outflows. Unfortunately, that will happen this year, with Wall Street analysts estimating a $14.2 billion outflow due to losses from BCA and BDS -- and it gets worse. Boeing CFO Brian West told investors that "we expect 2025 to be another use of cash." For reference, Wall Street expects a $2.7 billion outflow next year, as the company struggles to ramp airplane production and works through loss-making defense programs. 


Still, while West's commentary on the third-quarter earnings call shouldn't be taken as formal guidance, he said, "We expect the first half to be a cash usage and the second half to turn positive and then build real momentum as we exit the year."


As such, if Boeing can achieve this aim, the narrative around the stock would change going into the second half of 2025, and investors would start penciling in more optimistic scenarios for Boeing's cash generation and debt retirement.
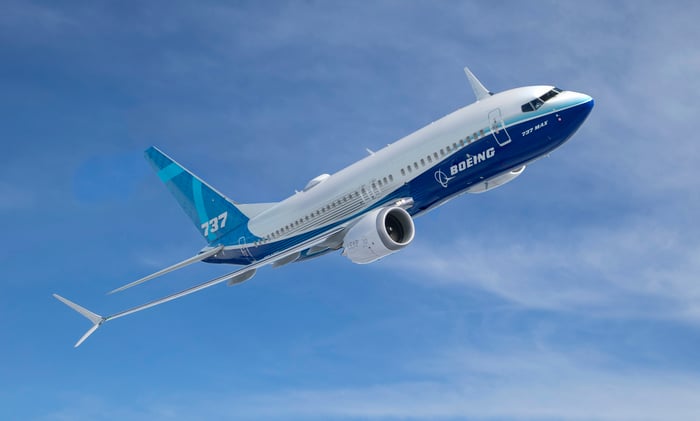

A Boeing 737 MAX.

Image source: Getty Images.


Ortberg's portfolio evaluation


Another source of improvement in the investment narrative around the stock comes from Ortberg's evaluation of what businesses are core and non-core at Boeing. He was clear on the earnings call that he needs to streamline "the portfolio to do what we do well."


Raising cash and cutting costs by exiting less profitable businesses is one way to improve investors' perceptions of the company. Moreover, it does not need to be a whole business. For example, RTX's defense business, Raytheon, terminated a fixed-price development contract in the second quarter, taking a $575 million charge in the process. Boeing may take similar rationalizing actions, even if they fall short of walking away from problematic programs.


Underpromise, overdeliver


When Larry Culp took over at the former General Electric, the first thing he did was firmly grasp the investment narrative by issuing a wide range of arguably conservative guidance that the company was able to hit or surpass. That changed the way investors thought about the stock.


Unfortunately, Boeing is highly unlikely to meet the $10 billion in free cash flow (FCF) target for 2025/2026 that former CEO Dave Calhoun laid out in late 2022.  Calhoun left office without having taken the guidance down, and clearly, Ortberg needs to issue a new financial outlook for investors.


Furthermore, the issue doesn't just involve BCA's manufacturing quality issues or the strike action; BDS has consistently taken charges on problematic defense contracts far more frequently than investors expected.


Ortberg discussed the matter on the latest earnings call and told investors that Boeing's estimate at completion (EAC) process needs to improve. That's the first step in ensuring BDS performance aligns with management's guidance. This is something in Boeing's hands.


Boeing in 2025


The three considerations discussed above are within management's capability and would help improve investor perception of Boeing. If so, the narrative around the stock should change as investors see Boeing generating FCF again in the second half.


Portfolio restructuring could improve its margin profile, and investors will start penciling in valuations with confidence that Boeing will hit the numbers rather than pouring doubt on management's ability to deliver. As such, investor perception of the stock could improve dramatically in 2025.


Read more

  • Nvidia Q3 Earnings Loom as Market Expects Revenue Near $109 Billion: Can NVDA Stock Hold $150?
  • Australian Dollar declines below 0.6750 after RBA minutes, US Retail Sales data in focus
  • Bitcoin Plunges 13% in a Week as Market Retreats to $60,000 Level
  • * The content presented above, whether from a third party or not, is considered as general advice only.  This article should not be construed as containing investment advice, investment recommendations, an offer of or solicitation for any transactions in financial instruments.

    goTop
    quote
    Related Articles
    placeholder
    Nvidia posts record $115.8B Q3 revenue, but crypto stays mutedThe crypto market remained subdued on Tuesday despite Nvidia's (NVDA) Q3 earnings release beating analysts' expectations as demand for artificial intelligence infrastructure continued to drive growth across its business.
    Author  FXStreet
    15 hours ago
    The crypto market remained subdued on Tuesday despite Nvidia's (NVDA) Q3 earnings release beating analysts' expectations as demand for artificial intelligence infrastructure continued to drive growth across its business.
    placeholder
    Nvidia Q3 Earnings Loom as Market Expects Revenue Near $109 Billion: Can NVDA Stock Hold $150? As of the close on November 16 ET, Nvidia (NVDA) shares fell 4.12% to close at $156.14, with an intraday low of $155.01 and trading volume of about 334 million shares. Compared with its p
    Author  TradingKey
    Yesterday 09: 10
    As of the close on November 16 ET, Nvidia (NVDA) shares fell 4.12% to close at $156.14, with an intraday low of $155.01 and trading volume of about 334 million shares. Compared with its p
    placeholder
    Weekly Report: The index rose 2.5% while Nvidia fell 12.7% — two equity divergences, one should closeThe S&P 500 rose 2.51% to 7,561.67 and the QQQ rose 3.63% to 679.89 last week, while Nvidia fell 12.75% to 162.85 — a sixth straight weekly loss and 32% below its October record. In the same five sessions, energy equities rose 5.42% while WTI fell 2.52%. Both pairs normally move together (60-day correlations of +0.64 and +0.58). This report ranks which divergence closes first, with the trigger for each.
    Author  Irene Q.
    Nov 16, Mon
    The S&P 500 rose 2.51% to 7,561.67 and the QQQ rose 3.63% to 679.89 last week, while Nvidia fell 12.75% to 162.85 — a sixth straight weekly loss and 32% below its October record. In the same five sessions, energy equities rose 5.42% while WTI fell 2.52%. Both pairs normally move together (60-day correlations of +0.64 and +0.58). This report ranks which divergence closes first, with the trigger for each.
    placeholder
    Anthropic is six times oversubscribed at $1.4 trillion while Nvidia is down 32% — the AI trade has two pricesAnthropic lists on Nasdaq as ANT on Thursday at $70 ~ $78 a share, raising up to $64.4 billion at a target valuation near $1.4 trillion, and the book is reportedly six times covered. In the same six weeks, Nvidia has fallen 32% and the QQQ is 10.9% below its October peak. Private capital and public markets are marking the same AI complex at two very different prices. This piece separates the two books: what the S-1 shows, who is anchoring the $26 billion private placement, and what Thursday's debut would have to do to change the public tape.
    Author  Irene Q.
    Nov 16, Mon
    Anthropic lists on Nasdaq as ANT on Thursday at $70 ~ $78 a share, raising up to $64.4 billion at a target valuation near $1.4 trillion, and the book is reportedly six times covered. In the same six weeks, Nvidia has fallen 32% and the QQQ is 10.9% below its October peak. Private capital and public markets are marking the same AI complex at two very different prices. This piece separates the two books: what the S-1 shows, who is anchoring the $26 billion private placement, and what Thursday's debut would have to do to change the public tape.
    placeholder
    Nvidia reports tomorrow with an interim CEO — $108 billion is the easy numberNvidia closed at 162.85 on Friday, down 12.75% on the week and 32% below its 6 October record, with market value down to $3.92 trillion. The Q3 bar is $108 billion ±2%, and consensus already sits at $108.7 ~ 108.8 billion, so the revenue line is not where the surprise lives. The number that decides the reaction is the 71 ~ 72% Q4 gross-margin trough, followed by a Q4 guide against a $124.9 billion consensus. This piece prices the print, marks the 158.39 line and lays out the three scenarios in a table.
    Author  Irene Q.
    Nov 16, Mon
    Nvidia closed at 162.85 on Friday, down 12.75% on the week and 32% below its 6 October record, with market value down to $3.92 trillion. The Q3 bar is $108 billion ±2%, and consensus already sits at $108.7 ~ 108.8 billion, so the revenue line is not where the surprise lives. The number that decides the reaction is the 71 ~ 72% Q4 gross-margin trough, followed by a Q4 guide against a $124.9 billion consensus. This piece prices the print, marks the 158.39 line and lays out the three scenarios in a table.
    Live Quotes
    Name / SymbolChart% Change / Price
    BA
    BA
    0.00%0.00

    US Stocks Related Articles

    • 10 Best Day Trading Platforms for Beginners and Active Traders in 2026: A Practical Guide
    • How To Invest in SpaceX Stock in 2026? Everything Investors Need to Know
    • Practice Trading Us Stocks? These Are 10 Best Stock Trading Demo Apps For Beginners
    • ​5 Best Paper Trading Platforms for 2026 (Free Demo Accounts for Beginners & Traders)
    • Wall Street’s Top 10 US Stocks for 2026 vs What Reddit Is Actually Buying
    • Is Mitrade Right for You? A Complete Guide on How to Start Trading CFDs in 5 Steps

    Click to view more