




Nike Stock Just Jumped 13%. Should You Buy the Stock on the Way Up?
Key Points
Nike is addressing its sales decline with a three-pronged strategy to list sales in China, revitalize its premium branding, and target consumers in sports.
Management still expects sales to drop this year, but gross margin is improving.
Nike stock is cheap right now, but it doesn't look quite like a bargain.
- Motley Fool Issues Rare "Total Conviction" Buy Alert ›
Nike (NYSE:NKE) is working hard to get back up to speed in athletic wear, where it's been losing ground to several newcomers. Its stock is 79% off its all-time high from 2021, but it's been rising recently, and it's up 13% since it bottomed out in October.
Is it time to buy into its recovery?
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Off its game
Nike is by far the largest company of its type in the world. It has incredible brand power and consistently ranks among the world's most valuable fashion brands, despite its athletic focus.

Image source: Nike.
However, it made some strategic decisions a few years ago that altered its model with brutal results. Instead of innovating, it began to rely on what it thought were proven franchises, cutting its wholesale relationships to focus on its direct-to-consumer business. It thought it could rely on its brand to keep loyal customers coming.
Instead, customers found other brands that offered great products, and Nike sales have been declining. In fact, they're roughly where they were five years ago.
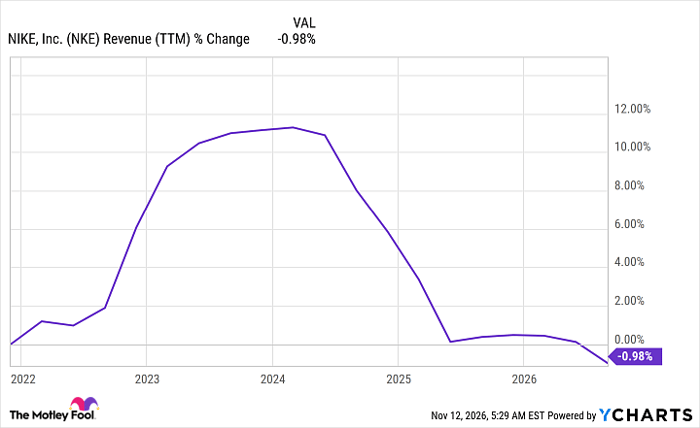
NKE Revenue (TTM) data by YCharts
Back on track
New CEO Elliott Hill has been working on a recovery, and while management still expects sales to decline this year, there are rays of hope.
Nike's women's basketball business has increased 500% from fiscal 2022 through 2026, for example, and gross margin, which was hampered by last year's tariffs, improved 0.60 percentage points to 42.8%.
Hill identified three specific avenues toward growth. One is creating scarcity around some of its franchises, like the Jordan brand, to revitalize the premium feel and generate more full-price sales.
The second is gaining traction in China, where sales were down 26% from last year in the 2027 fiscal first quarter (ended Aug. 31). Nike is aiming to boost its image there as well by being more deliberate about wholesale partners and concentrating on premium branding.
Finally, perhaps the most important of the three new approaches is regaining the respect of sports consumers by creating products that meet their specific needs. Nike is accelerating its innovation and bringing out more products faster, and it's releasing clothing and footwear for smaller niches in both sports and lifestyle.
Why is Nike rising?
The market seems to believe that Nike stock looked priced to buy, especially as a hedge against some of the more capricious tech plays, when it hit rock bottom in October.
At the current price, it trades at 24 times trailing-12-month earnings, which isn't cheap enough for me to call it a bargain in its current situation. It has an excellent dividend that yields 4.3% at the current price, however, and it could be a great buy for long-term passive income investors.
Missed AI’s "Act 1"? Act 2 Could Be 14x Bigger
Most investors think they missed the AI boat because they didn't buy Nvidia in 2005.
But according to our analysts, we’re only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout, a massive technology build-out that Google’s CEO says could be more profound than fire or electricity.
While everyone watches the chip designers, one "backbone" company provides the critical technology that Nvidia and AMD literally cannot function without. We’ve detailed this under-the-radar player in our new AI Playbook.
Continue »
Jennifer Saibil has no position in any of the stocks mentioned. The Motley Fool has positions in and recommends Nike. The Motley Fool has a disclosure policy.
Recommended Articles


