




Sandisk’s Stock Split Takes Effect Nov. 19. Should You Buy It Now?
Key Points
Sandisk is reshaping its business to make it more sustainable.
Shares of the memory chip maker are very cheap right now.
- Motley Fool Issues Rare "Total Conviction" Buy Alert ›
Sandisk (NASDAQ:SNDK) has a major event coming soon: a stock split. In the past, stock splits have caused share prices to rise in anticipation of the split, making them popular events to invest in.
However, I think there are far better reasons to invest in Sandisk's stock split, as its business is looking strong. Its stock is also priced quite cheaply, which really makes it a great buy now.
Missed AI’s "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our analysts, we’re only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
So, regardless of how the stock reacts after its stock split on Nov. 19, I think Sandisk is a top investment option in the market.

Image source: The Motley Fool.
Sandisk is capitalizing on the AI build-out
Sandisk manufactures NAND memory, and also devices that those go into. NAND memory is utilized for long-term data storage and can be used in devices like smartphones and solid-state drives (SSDs). AI hyperscalers and their quest to build out as much computing power as possible have eaten up nearly all production capacity for NAND memory, as they need storage devices like SSDs to store massive amounts of data to be used for AI recall.
That shortage has been a huge boost for Sandisk. There isn't a lot that separates Sandisk's products from the competition, so its clients often went with the cheapest option. However, as supply for these units dried up, prices began to rise. For Sandisk, this isn't a problem, because it can now make a far larger profit on each unit sold because its input costs hadn't changed.
This is reflected in Sandisk's financials, as its gross and profit margins have both soared.
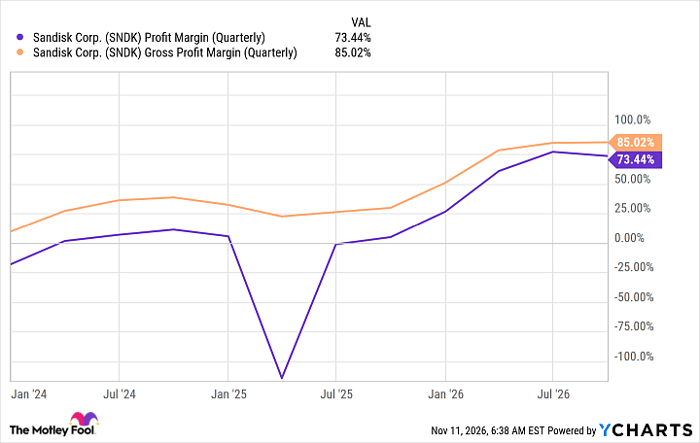
SNDK Profit Margin (Quarterly) data by YCharts
This is a major improvement over previous highs and has translated into major shareholder returns. This year, Sandisk is the second-best-performing S&P 500 (SNPINDEX:^GSPC) stock, rising nearly 300% so far in 2026. However, I think it could have more returns ahead of it, as nothing has shifted in the market right now.
Sandisk won't be as cyclical moving forward
The biggest reason why Sandisk and its peers weren't prepared for the AI demand wave is that their clients don't have close working relationships. As mentioned above, its clients utilize the cheapest options available, so that meant bouncing around from supplier to supplier.
Because Sandisk and its peers were operating as cheaply as possible to cut costs, they had no plans to increase production capacity when it wasn't being fully utilized anyway. However, Sandisk's clients have now seen the value in keeping close business ties with them, and Sandisk has started to enter into what it calls "New Business Model" agreements.
This arrangement locks in committed volumes and structured pricing levels, which gives Sandisk a more stable business. This allows the company to better plan for what its cash flows will be, which will allow it to aggressively repurchase shares, which will boost investor returns.
This is great news for investors, and will reduce the cyclical downturn that Sandisk and other memory companies have historically experienced as demand waves end.
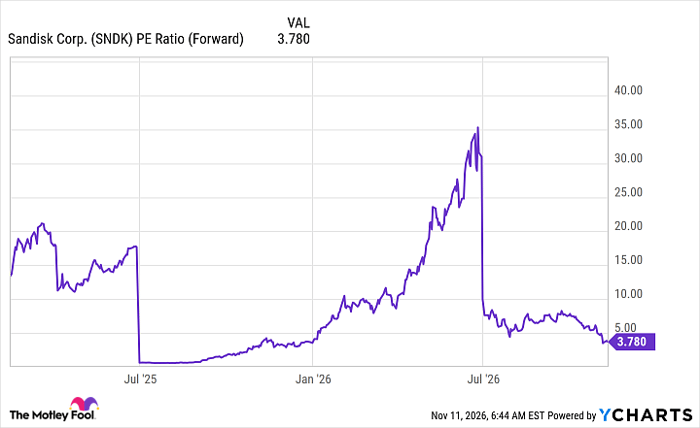
SNDK PE Ratio (Forward) data by YCharts
However, the stock is priced as if the demand wave will end tomorrow. With the shares trading at less than 4 times forward earnings, the market isn't pricing in any success. I think that's a huge mistake, as Sandisk will now be able to repurchase shares for next to nothing.
A large share repurchase plan will accelerate Sandisk's earnings-per-share growth and will send shares to a far higher level. I think this will be the ultimate catalyst for Sandisk that sends its shares higher throughout 2027, not the stock split.
Sandisk may have had a good 2026, but I think 2027 could be just as strong thanks to sustained demand and a new financial model. Now would be a great time to buy, as the stock is pretty weak thanks to overall AI investment weakness.
Should you buy stock in Sandisk right now?
Before you buy stock in Sandisk, consider this:
The Motley Fool Stock Advisor analyst team just identified what they believe are the 10 best stocks for investors to buy now… and Sandisk wasn’t one of them. The 10 stocks that made the cut could produce monster returns in the coming years.
Consider when Netflix made this list on December 17, 2004... if you invested $1,000 at the time of our recommendation, you’d have $335,171!* Or when Nvidia made this list on April 15, 2005... if you invested $1,000 at the time of our recommendation, you’d have $1,000,640!*
Now, it’s worth noting Stock Advisor’s total average return is 823% — a market-crushing outperformance compared to 208% for the S&P 500. Don't miss the latest top 10 list, available with Stock Advisor, and join an investing community built by individual investors for individual investors.
See the 10 stocks »
*Stock Advisor returns as of November 14, 2026.
Keithen Drury has no position in any of the stocks mentioned. The Motley Fool has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy.
Recommended Articles


