


This Dirt Cheap $5 Stock Could Make You Filthy Rich
Key Points
Joby Aviation is not a cheap stock per se, but its current price looks attractive against its future.
Joby hasn't certified its eVTOL, but it's earning revenue through Blade Air Mobility.
- 10 stocks we like better than Joby Aviation ›
What's a beaten-down stock trading for $5 a share, whose company is building one of America's first electric air taxis and could be worth several times its valuation if it succeeds?
My answer: Joby Aviation (NYSE: JOBY).
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Yes, Joby, the electric air taxi developer, has been on a roll in 2026, flying its eVTOL (electric vertical takeoff and landing) aircraft in New York City, San Francisco, and Dallas-Fort Worth, and gearing up for its first passengers. And yet the stock has tanked -- no surprise, really, given its extraordinary valuation before -- dropping about 65% this year.
Why, then, should investors be interested in Joby?
Joby already owns key parts of its future business
To begin with, Joby is trying to launch an air taxi business. This isn't as futuristic as it sounds -- not as futuristic as, say, the flying cars in Back to the Future. Still, Joby's flying taxi could help solve a major headache in cities: rush-hour traffic.
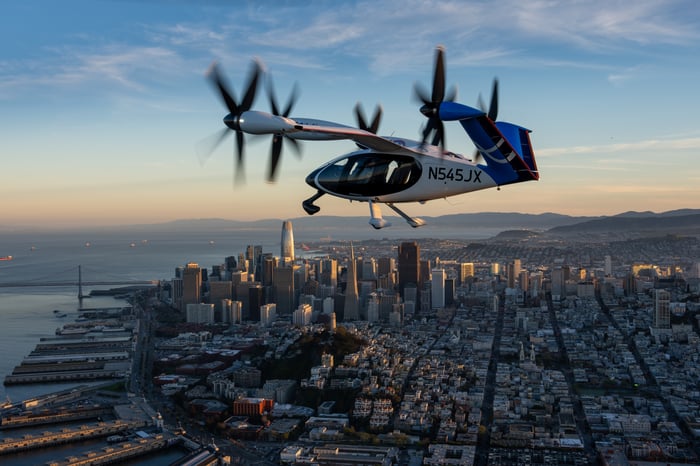
Image source: Joby Aviation.
Most of the attention around Joby goes to its aircraft, and understandably so, given that they are still uncertified for commercial operations. The company is progressing through the final stages of FAA type certification, which, once completed, would put it one step closer to flying paying customers.
Although Joby has yet to secure certification for commercial passenger operations, it's been making some smart moves elsewhere.
Last year, for instance, Joby acquired Blade Air Mobility's passenger business. Blade doesn't fly eVTOLs, but it does offer helicopter services on established routes using infrastructure in places like New York. In the second quarter, Blade generated about $36 million for Joby, with the number of passenger seats filled on flights growing more than 50% from the previous year.
What I like about Blade isn't the revenue (although that's a nice touch, too). Rather, it's the data. With Blade, Joby can already start assessing which routes attract the most passengers, what customers are willing to pay, and when they use the service most (and least). These are questions Joby's competitors will eventually have to answer, yet Joby has the advantage of studying existing routes even before launching its electric air taxi services.
Should you buy Joby at $5?
Admittedly, Blade's passengers aren't necessarily representative of Joby's future market, or rather, we can't definitively prove that they are. What works for premium helicopter rides -- geared toward the wealthy -- might not work for electric air taxis, especially if Joby wants them to appeal to the masses.
Still, Joby doesn't need to attract the masses in a single day; it just needs to attract enough customers to get its air taxi business off the ground. Blade has done that to some extent, giving it an existing customer base and a better idea of which routes might be more profitable. That could eventually give Joby a sharp advantage over other eVTOL companies.
Joby's valuation, to be sure, isn't cheap: The stock trades for about 40 times trailing revenue, which is much higher than other aviation stocks (Delta Air Lines, for instance, trades below 1). Still, I think Wall Street has good reason to be optimistic about Joby's long-term prospects. Indeed, if Joby can turn its aircraft into a profitable business, today's price could look remarkably cheap in retrospect.
Should you buy stock in Joby Aviation right now?
Before you buy stock in Joby Aviation, consider this:
The Motley Fool Stock Advisor analyst team just identified what they believe are the 10 best stocks for investors to buy now… and Joby Aviation wasn’t one of them. The 10 stocks that made the cut could produce monster returns in the coming years.
Consider when Netflix made this list on December 17, 2004... if you invested $1,000 at the time of our recommendation, you’d have $334,793!* Or when Nvidia made this list on April 15, 2005... if you invested $1,000 at the time of our recommendation, you’d have $1,257,420!*
Now, it’s worth noting Stock Advisor’s total average return is 874% — a market-crushing outperformance compared to 209% for the S&P 500. Don't miss the latest top 10 list, available with Stock Advisor, and join an investing community built by individual investors for individual investors.
See the 10 stocks »
*Stock Advisor returns as of October 31, 2026.
Steven Porrello has positions in Joby Aviation. The Motley Fool recommends Delta Air Lines. The Motley Fool has a disclosure policy.
Recommended Articles


