


Alphabet Tumbles 8% After Hours as Q3 Revenue Slightly Misses Estimates, Free Cash Flow Negative $9.065 Billion
TradingKey - On October 28, Google parent company Alphabet (GOOGL) (GOOG) reported its third-quarter 2026 financial results. Doubling Google Cloud revenue drove group revenue up 25% and operating profit up 30%. However, total revenue fell slightly short of market expectations, losses on securities investments dragged on net profit, and expanding capital expenditures kept free cash flow negative for the second consecutive quarter.
As of press time, Google shares once fell over 8% in after-hours trading to $298.
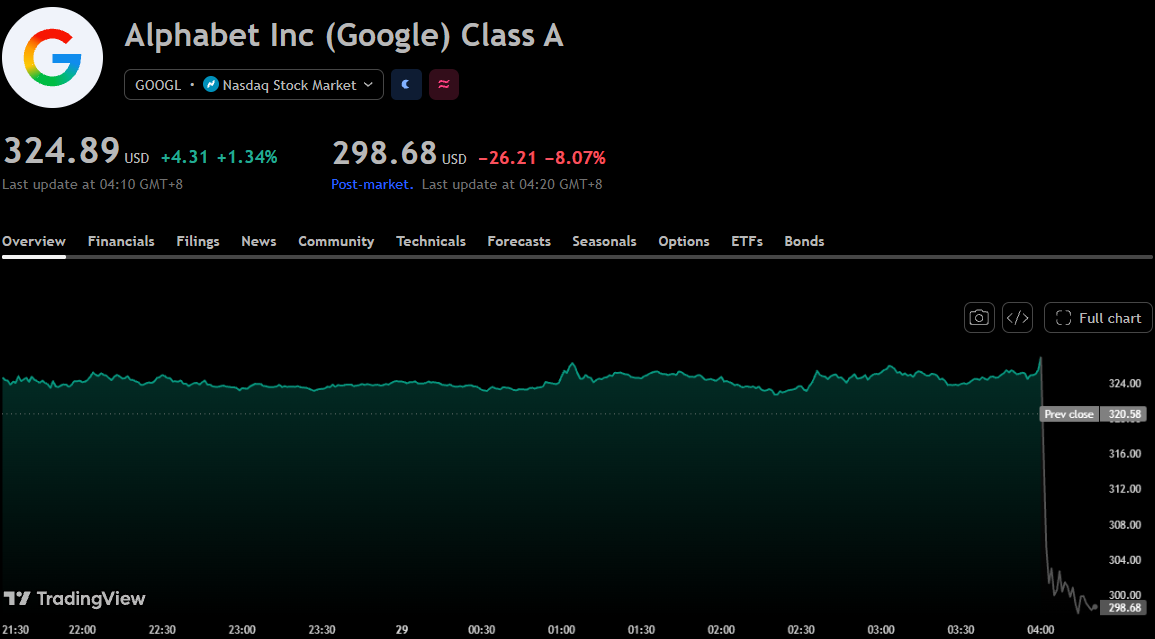
Google stock chart, Source: TradingView
Alphabet Third-Quarter Revenue Misses Estimates by 0.49%
Alphabet's third-quarter revenue reached $127.577 billion, up 25% year-over-year, or 25% on a constant currency basis, marking the 13th consecutive quarter of double-digit revenue growth. Compared to market expectations of $128.200 billion, actual revenue fell short by $623 million, coming in 0.49% below expectations; the year-over-year growth rate disclosed by the company was in line with the market estimate of 25%.
Google Cloud remained the primary growth driver, with revenue of $30.709 billion, up 103% year-over-year. The company attributed the growth to demand for enterprise AI infrastructure, AI solutions, and core Google Cloud Platform services, noting that TPU system sales also made a significant contribution to revenue growth. Cloud operating income rose to $11.121 billion from $3.594 billion in the same period last year.
Google Services revenue reached $96.302 billion, up 11% year-over-year. Within this segment, Search & other revenue was $63.350 billion, up 12% year-over-year; YouTube advertising revenue was $11.207 billion, while Subscriptions, platforms, and devices revenue reached $14.290 billion. Google Services operating income rose to $39.157 billion from $33.527 billion.
Alphabet Adjusted EPS of $2.12 Falls Well Short of Market Estimate of $3.02
During the period, Alphabet's operating income reached $40.576 billion, up 30% year-over-year, with an operating margin of 31.8%.
However, the growth in operating income failed to drive a corresponding increase in net income. GAAP net income stood at $26.468 billion, and after deducting preferred stock dividends of $298 million, net income available to common shareholders was $26.170 billion, down from $34.979 billion in the same period last year. Diluted earnings per share were $2.12, compared with $2.87 in the year-ago period, missing market expectations of $3.02.
Profit was significantly impacted by a reversal in gains and losses on securities investments. Net other expense for the quarter was $8.221 billion, compared with net other income of $12.759 billion in the same period last year.
Specifically, equity securities swung from a net gain of $10.734 billion in the prior-year period to a net loss of $8.664 billion. This item includes both realized and unrealized gains and losses, so it cannot be characterized entirely as unrealized losses. The company disclosed that the equity securities loss in the quarter reduced income tax expense by approximately $1.900 billion, while lowering net income by approximately $6.700 billion and diluted earnings per share by $0.55.
Free Cash Flow Negative for Second Consecutive Quarter
Capital expenditures and cash flow were another focus. Purchases of property and equipment in the third quarter stood at $51.355 billion, up approximately 114.4% year-over-year calculated based on financial report data, which was below the analyst expectation of $55.200 billion tracked by FactSet, coming in $3.845 billion or 6.97% lower than expected.
However, operating cash flow fell from $48.414 billion in the same period last year to $42.290 billion, failing to cover capital expenditures. Consequently, free cash flow was negative $9.065 billion, declining further from negative $5.855 billion in the previous quarter. Compared with the analyst estimate of negative $2.270 billion, free cash flow saw an additional outflow of $6.795 billion this quarter.
Recommended Articles


