


Fed October Rate Decision Preview: Rate Hike Pause Has Become Consensus, How Will US Stocks, Dollar, and Gold React?
TradingKey - The Federal Reserve will announce its October interest rate decision at 14:00 Eastern Time on October 28, and Fed Chair Warsh will hold a press conference at 14:30. Markets currently widely expect that after a 25-basis-point rate hike in September, the Fed will temporarily stand pat, maintaining the target range for the federal funds rate at 3.75%-4.00%.
Fed May Pause Rate Hikes in October, But Chance of December Hike Remains High
According to the latest Reuters survey, almost all surveyed economists expect the Federal Reserve to keep interest rates unchanged in October, but most institutions still believe another rate hike in December is possible. At its September meeting, the Fed had just raised rates by 25 basis points to 3.75%-4.00%, while the September meeting minutes showed that a majority of officials believed another rate hike before year-end could be appropriate.
Inflation remains the primary factor supporting further policy tightening by the Fed. In September, U.S. CPI rose 3.7% year-over-year, well above the 2% inflation target, while core CPI increased 2.6% year-over-year. The subsequently released September PPI surged 1.3% month-over-month and rose to 6.3% year-over-year, marking its largest monthly gain in over four years. Energy prices were a major driver, but service prices and some core components were also strong, indicating that inflationary pressures are not entirely confined to gasoline and energy.
However, a cooling labor market provides a rationale for the Fed to pause rate hikes. U.S. nonfarm payrolls added only 29,000 jobs in September, significantly below market expectations of 90,000, while the unemployment rate rose from 4.1% to 4.2% and wage growth slowed. Although the latest initial jobless claims remain near historic lows at 194,000, indicating that companies have not engaged in large-scale layoffs, hiring activity has clearly slowed.
Notably, financial conditions affecting rate hikes have tightened significantly. Following the September rate hike, U.S. Treasury yields continued to climb, with the 10-year Treasury yield briefly surging above 5.3%. The Fed may prefer to observe the impact of high interest rates and rising bond yields on consumption, housing, and corporate investment, rather than raising rates at two consecutive meetings. The Reuters survey therefore suggests that a pause in October followed by another rate hike in December is currently the more mainstream policy path.
Therefore, the most critical aspect to watch at this meeting is Warsh's wording regarding the December policy path. If he continues to emphasize inflation risks and indicates that further policy tightening remains appropriate, even without an October rate hike, it could be interpreted by the market as a "hawkish pause." If Warsh places greater emphasis on slowing employment, tightening financial conditions, and waiting for more data, the market may lower its expectations for a December rate hike.
How Will the October Fed Decision Impact US Stocks, the Dollar, and Gold?
For US equities, if the Federal Reserve keeps interest rates unchanged at 3.75%-4.00% while Warsh does not significantly reinforce expectations of a December rate hike, US stocks may receive temporary support. Recently, the 10-year US Treasury yield has remained near 5%, with high interest rates becoming a key factor constraining tech stock valuations. Therefore, any dovish signal could drive US Treasury yields lower, which would be relatively favorable for high-valuation sectors such as the Nasdaq, AI, and semiconductors. However, if the Fed pauses rate hikes but explicitly hints at another hike in December, the market may view it as a "hawkish pause," sending Treasury yields higher again and leaving high-valuation tech stocks under pressure.
Regarding the US dollar, its reaction may depend more on Warsh's press conference than on the rate hold itself. A pause in rate hikes is currently well priced in by the market. If the Fed clearly states that inflation remains too high and policy tightening may continue in December, the US dollar could strengthen again, driven by the US interest rate advantage and rising Treasury yields. Conversely, if Warsh emphasizes employment risks and downplays the urgency of further rate increases, the market may lower December rate hike expectations, leaving room for a short-term pullback in the US Dollar Index. Currently, the greenback remains near an 18-month high, with shifts in policy expectations exerting a significant impact on its short-term movement.
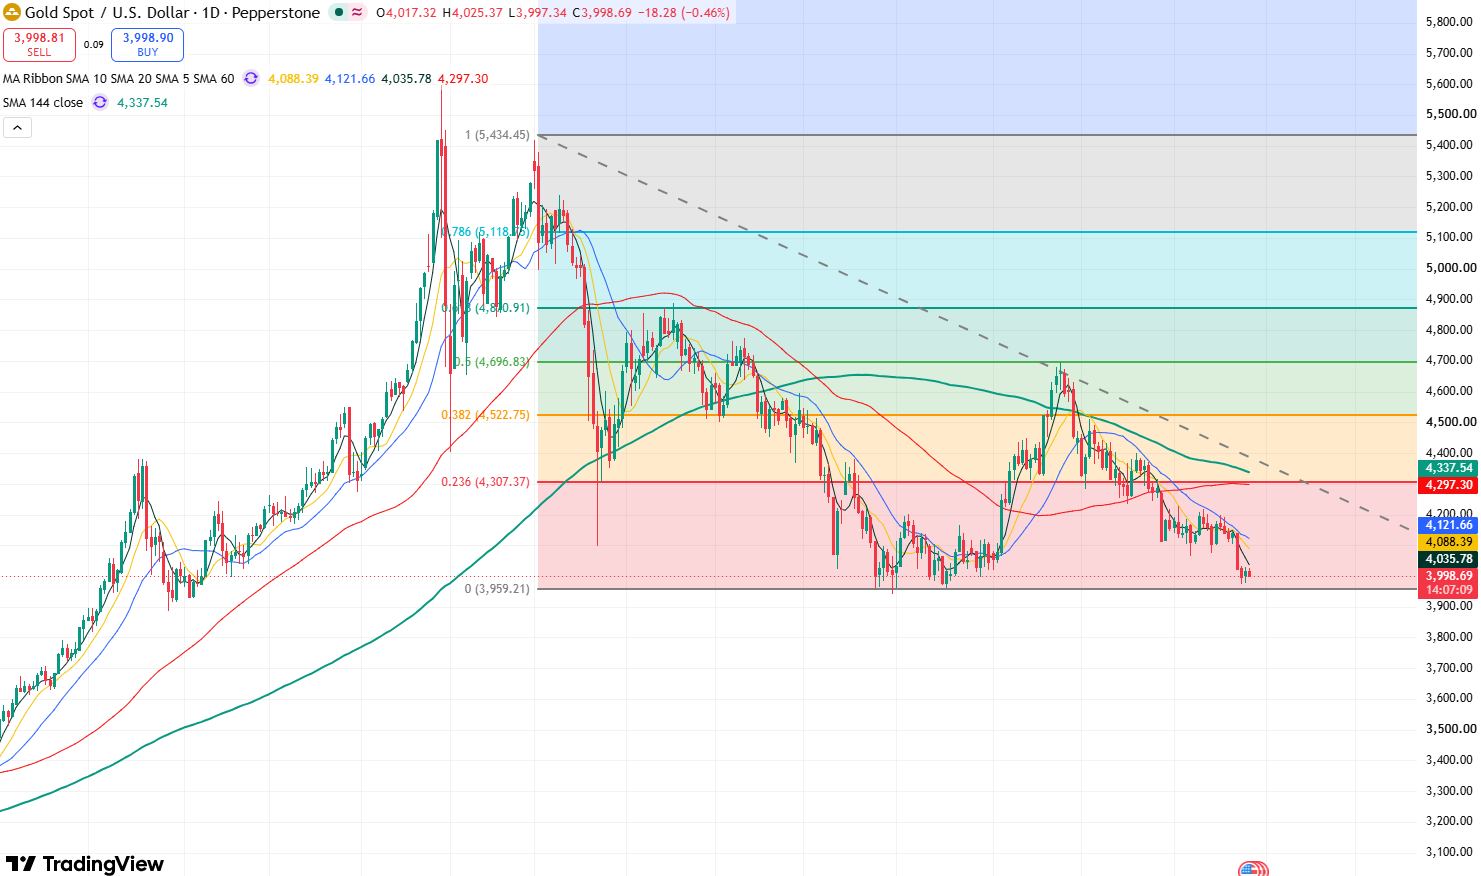
Gold Price Daily Chart, Source: TradingView
As for gold, current gold prices (XAUUSD) are trading near $4,000, with high interest rates and a strong US dollar continuing to limit a rebound in gold. If the Fed delivers hawkish signals and reinforces the likelihood of a December rate hike, US Treasury yields and the dollar could strengthen in tandem, placing gold under pressure again; gold prices may fall below $4,000 and further test the low near $3,940. If the Fed pauses rate hikes while remaining cautious about subsequent policy, causing the market to scale back December rate-hike bets, gold could regain support, with prices expected to rebound to test $4,100.
Read more
* The content presented above, whether from a third party or not, is considered as general advice only. This article should not be construed as containing investment advice, investment recommendations, an offer of or solicitation for any transactions in financial instruments.


