


Gold breaks $4,000 as oil becomes the inflation problem — $3,943 is the line that matters
Mitrade Insights — Spot gold closed at $3,995.6 on October 23, down about 4.1% for the week, after touching $3,975 — its lowest since mid-July. On October 26 it traded near $3,988. The unusual part is what happened around it: Brent crude settled at $116.72, up about 6% on the week and near a six-month high, while Middle East supply risk remained elevated. Gold usually catches a bid when oil and geopolitics flare together. This time it did not.
Three numbers: $4,008, $3,943, 4.99%
The first number is the price: $4,008 on the COMEX December contract and $3,988 on spot, just below the $4,000 line. The second is $3,943, the July low that Bank of America's Paul Ciana calls the more important level. The third is 4.99%, the 10-year Treasury yield.
Put them together and the story is not “gold lost its haven status.” It is that the haven bid was outbid by the discount rate.
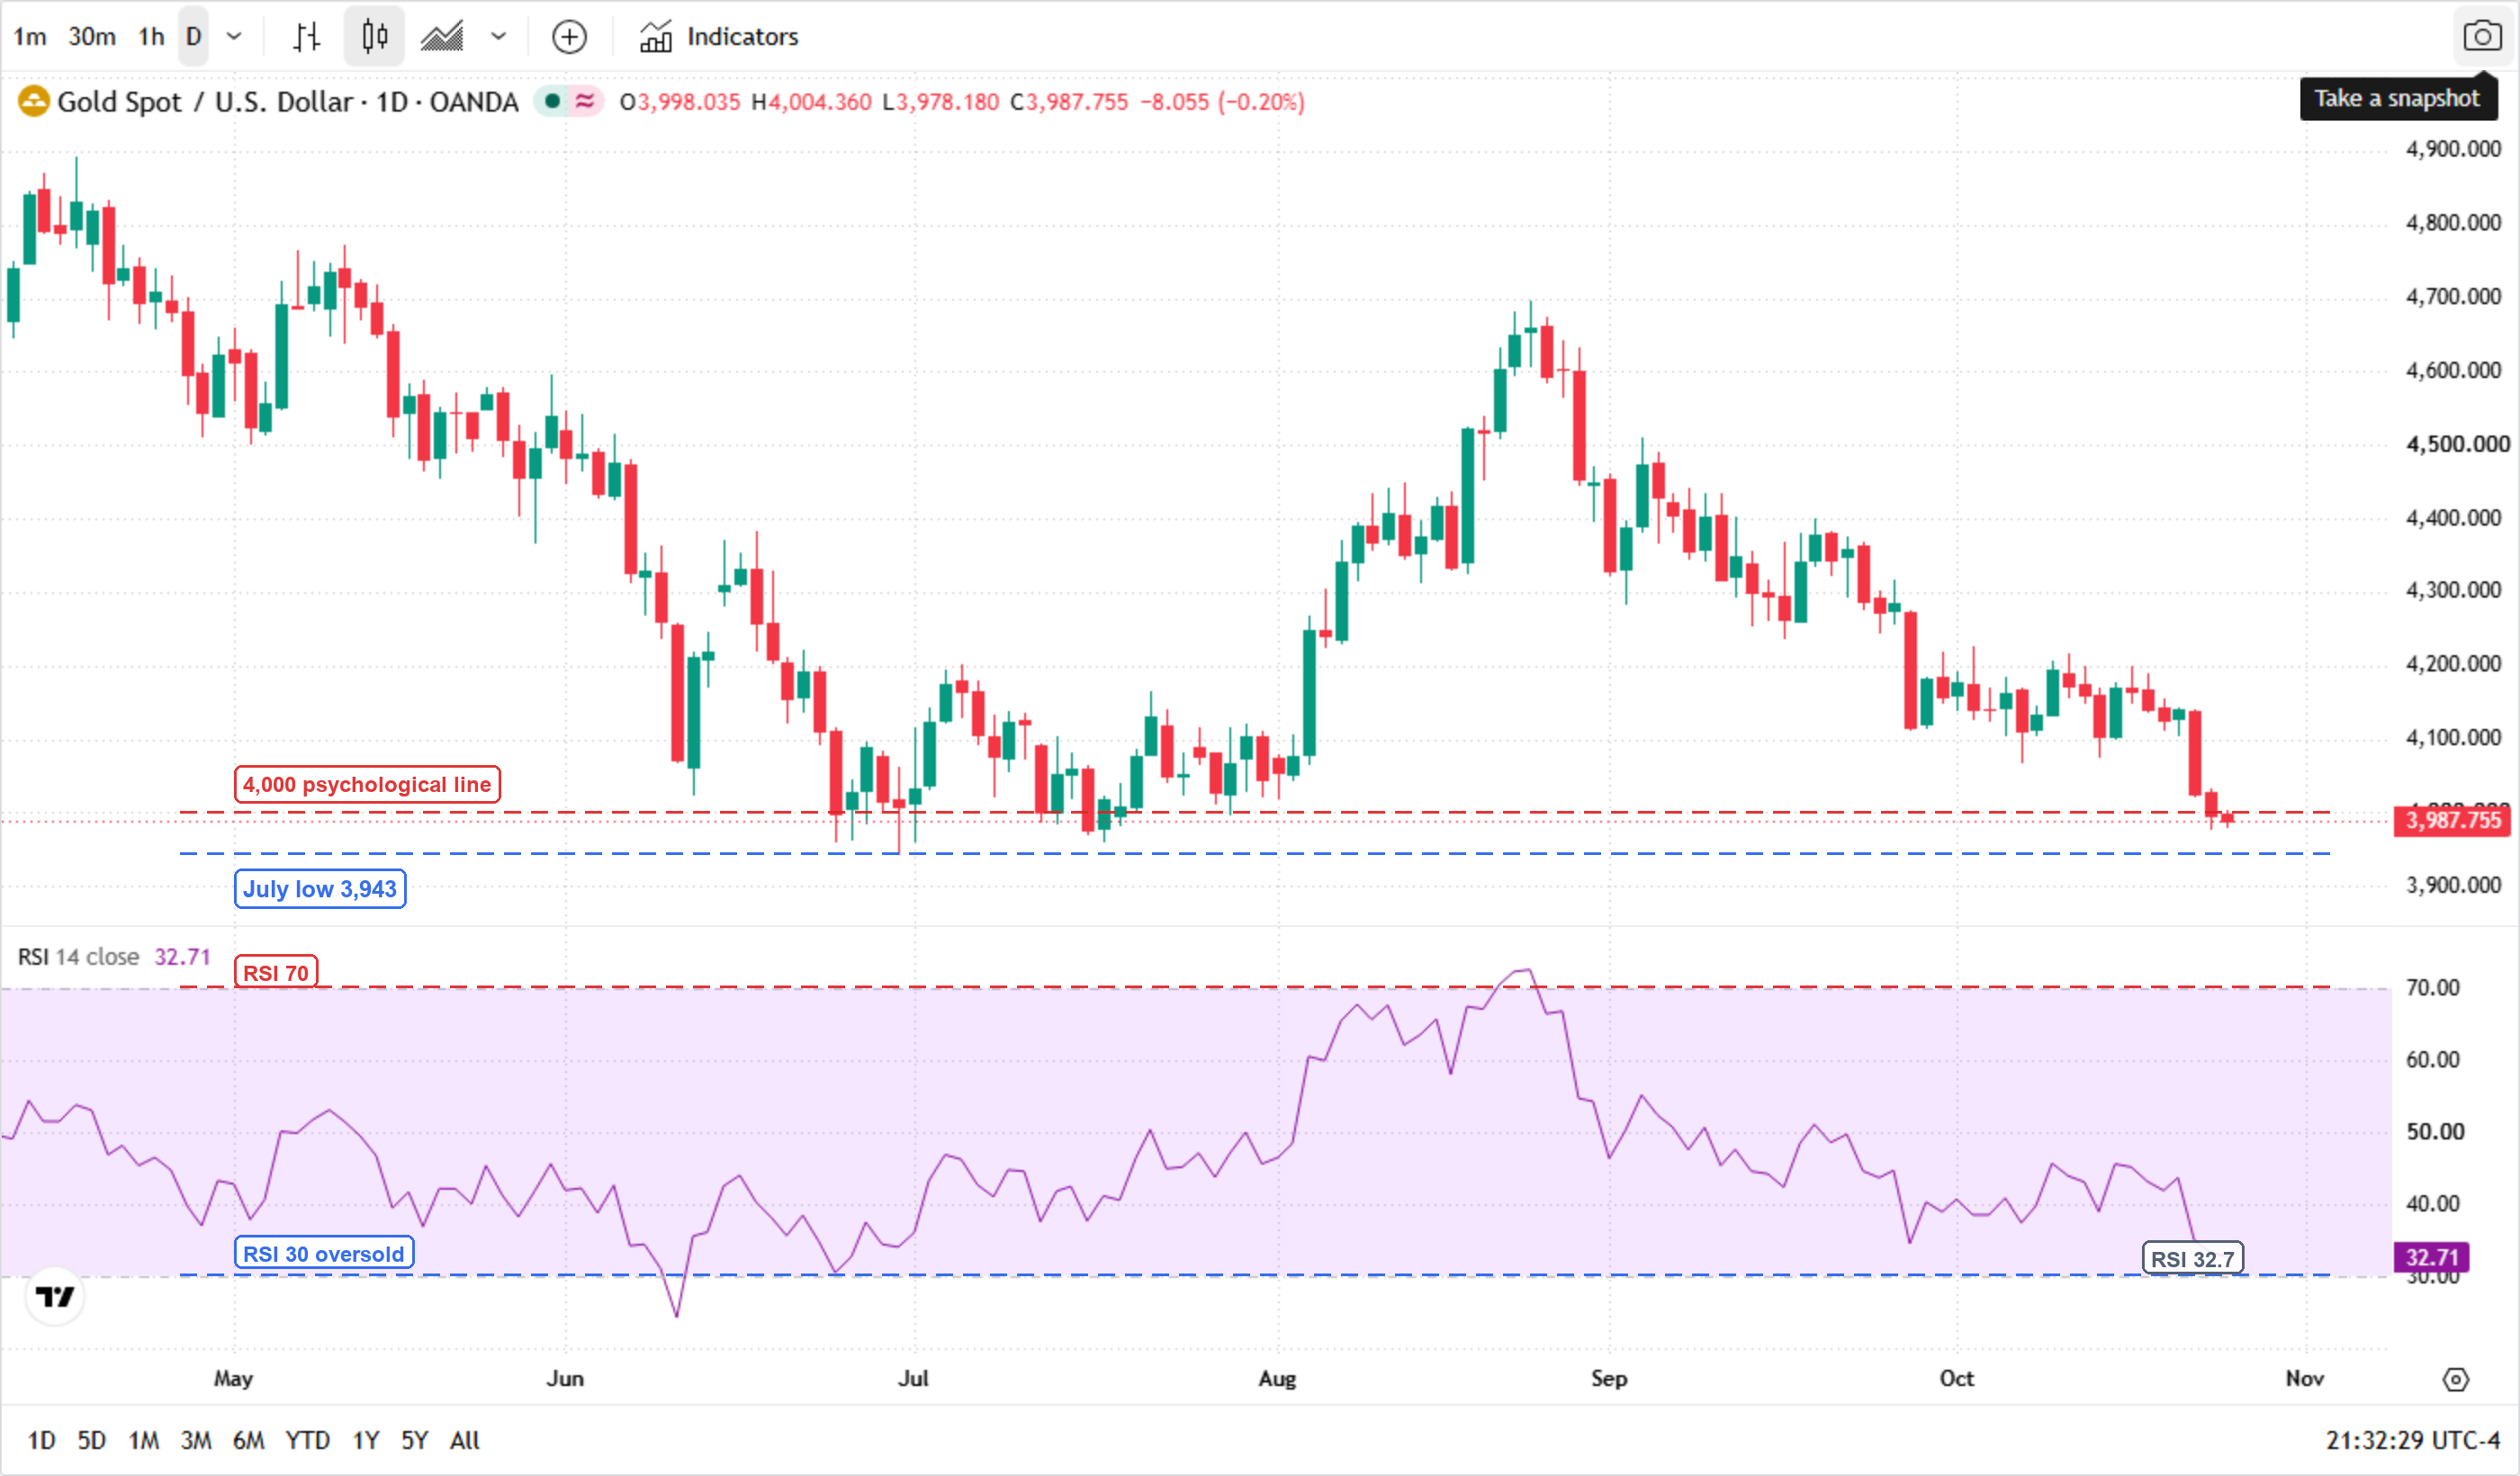
* Image source: TradingView (OANDA:XAUUSD, gold spot CFD).
Why the war premium stopped working
Oil is now the inflation trade
Brent's move from roughly $110 to $116.72 in a week is not a demand story. It is a supply-risk premium: attacks on Saudi energy infrastructure and shipping, plus the threat around the Strait of Hormuz. For most of the past two years, that would have been a straightforward gold bid. This time the same barrel of oil feeds directly into the inflation expectations that drive Fed pricing.
CME FedWatch shows a 90% chance the Fed holds at 3.75%–4.00% on October 28, but a 68.9% chance of a 25bp hike by December, and 76.2% odds of at least one hike by year-end. Higher oil pushes the hike path further out, not away.
The dollar and the real yield
The 10-year nominal yield actually fell about 16 basis points on the week, to 4.988%. If gold were trading off nominal yields alone, it should have held. It did not, because the relevant rate is the real yield: when oil lifts inflation expectations faster than nominal yields, the real yield rises even with the nominal yield flat. The dollar added a second pressure point, with DXY at 101.81.
| Asset | Oct 23 close | Weekly change | What it says |
|---|---|---|---|
| Spot gold | $3,995.6 | -4.1% | Lowest since mid-July |
| COMEX silver | $53.71 | about -6% | 2026 low; industrial beta cut both ways |
| Brent crude | $116.72 | +6% | Supply-risk premium, not demand |
| US 10-year yield | 4.988% | -16 bp | Nominal yields fell; gold still fell |
| Dollar index (DXY) | 101.81 | small gain | A second headwind |
The July low is the line
The technical map is unusually clean. Support sits at $3,985, $3,970, $3,943 (the July low), then $3,886 and $3,700. Resistance is $4,015, $4,035, $4,065–$4,075 and $4,230. The 14-day RSI is 30.7, just into oversold territory, and price is below the 20-, 60- and 200-day averages shown on the chart.
| Level | Price | Why it matters |
|---|---|---|
| Support 1 | $3,985 | Near-term gamma support |
| Support 2 | $3,943 | July low; BofA's double-bottom line |
| Support 3 | $3,886 / $3,700 | Next targets if $3,943 breaks |
| Resistance 1 | $4,035 | Base case stays bearish below it |
| Resistance 2 | $4,065–$4,075 | First real recovery test |
| Resistance 3 | $4,230 | Would signal the correction is over |
The Kitco weekly survey is split: 41% of Wall Street analysts expect further declines, 24% expect a rise and 35% expect sideways. UBS still sees $5,400 by September 2027; BofA's near-term map is $3,886 then $3,700.
What would make this a bottom
The strongest historical analogy comes from the July low itself. Gold bottomed near $3,943 — BofA's level — then rallied to about $4,753 by late August, a 20% move. BCA Research notes that the gap between the current price and its 200-day average resembles that late-July short-term bottom. If the same setup is repeating, $3,943 is where buyers should appear again, and a reclaim of $4,065–$4,075 would confirm it.
The counter-case is equally specific. If $3,943 breaks on a daily close, the July analogy fails and the measured move opens $3,886 and then $3,700. That would not be a haven story at all; it would be a repricing of gold's discount rate in a world where oil keeps the Fed hiking.
Read more
* The content presented above, whether from a third party or not, is considered as general advice only. This article should not be construed as containing investment advice, investment recommendations, an offer of or solicitation for any transactions in financial instruments.


