


Big Tech's $800 billion AI bill faces its first real test — free cash flow is the judge
Mitrade Insights — Three of the largest AI spenders report this week: Alphabet and Microsoft after the close on October 28, Amazon on October 29. Together with Meta, hyperscaler capital expenditure is running near $800 billion a year. Until last week, the market paid for that spending on the promise of AI demand. After Meta's negative free cash flow and 9.40% drop on October 22, the question has changed: does the cloud revenue and contracted backlog cover the bill?
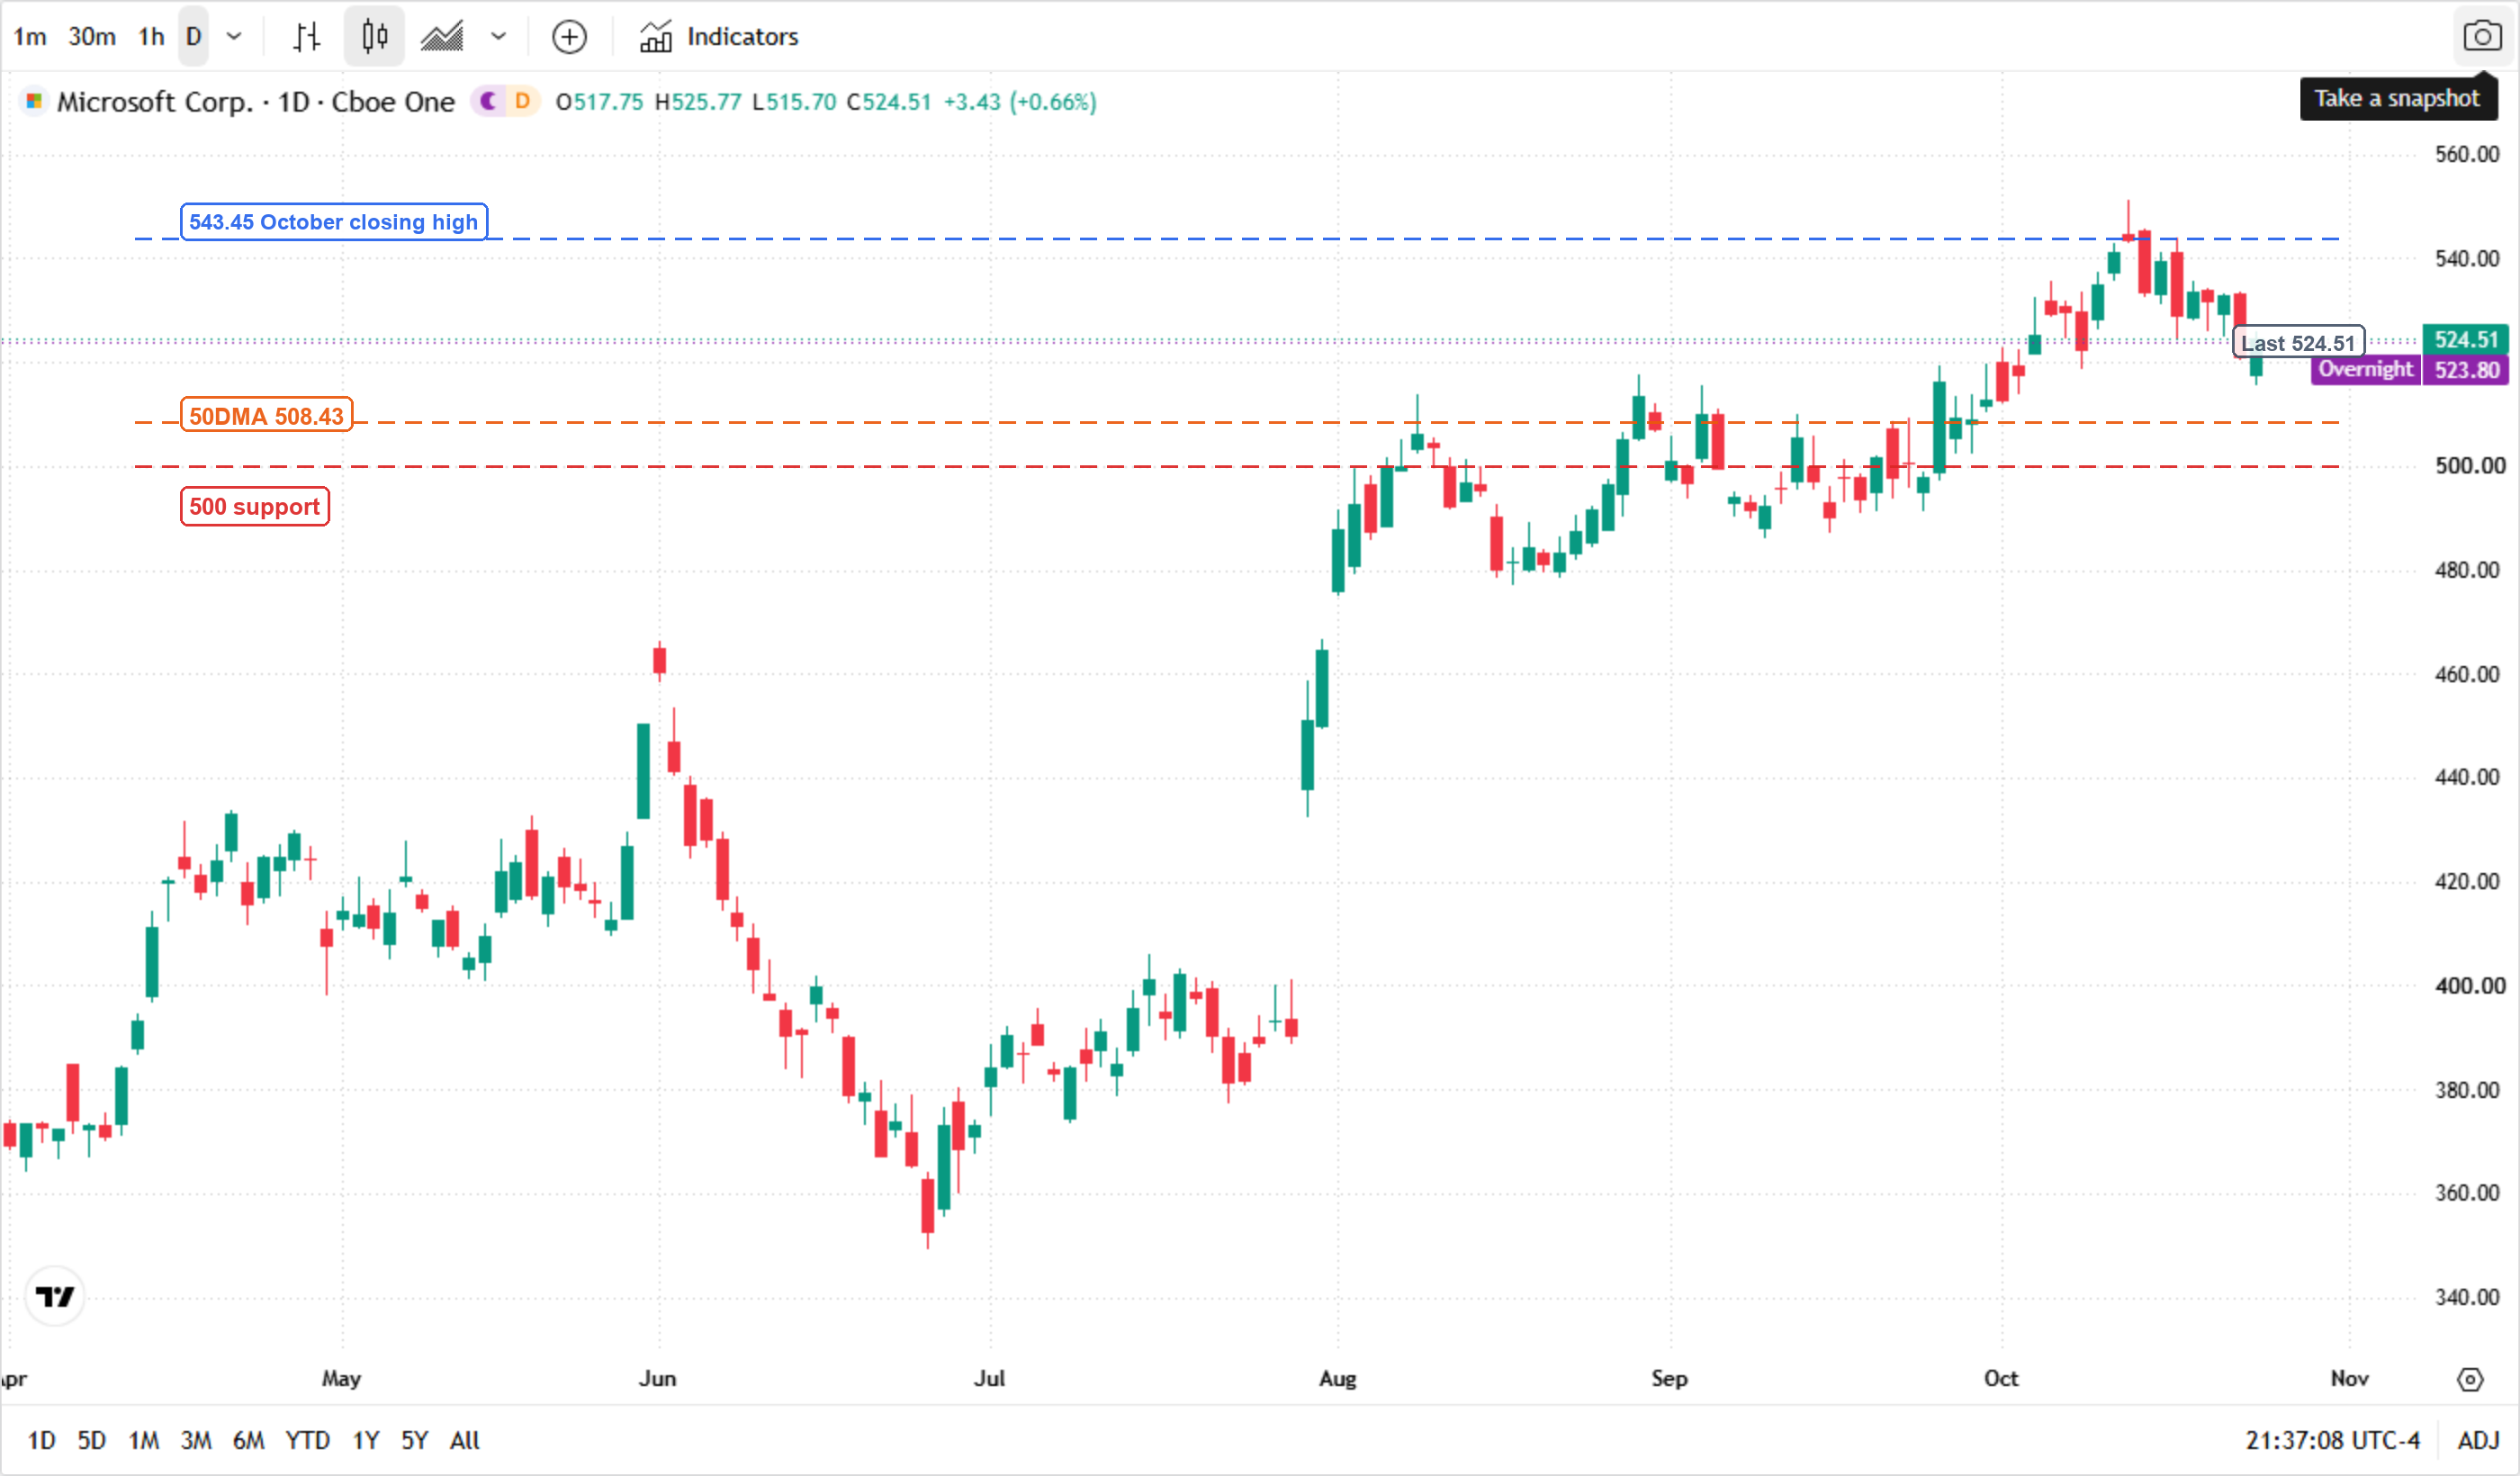
* Image source: TradingView (Microsoft, Nasdaq: MSFT).
How the AI trade got to this week
The sequence matters. On October 22, Meta beat on revenue and still lost more than $100 billion of market value after guiding 2026 capex to $135 billion ~ $145 billion and posting negative free cash flow for the first time since going public. Lam Research fell 12.82% on supply-constrained guidance. The Nasdaq Composite dropped 2.60%, its worst session since June, and the Philadelphia Semiconductor Index fell 6.72%. By Friday, the Nasdaq had logged a second straight weekly loss, down 0.71%, while the S&P 500 slipped 0.47%.
That is the setup for this week. The market is no longer rewarding capex announcements; it is asking for the cash return on them. With the 10-year Treasury yield at 4.988% and CME FedWatch pricing a 68.9% chance of a December hike, the discount rate is not helping.
Three companies, one question
Microsoft: $50 billion of capex against 44–45% Azure growth
Microsoft reports fiscal Q1 2027 after the close on October 28. Consensus is for revenue of $90.6 billion ~ $91 billion, up about 17%, and EPS of $4.71 ~ $4.73. The line that matters is Azure: management guided 44–45% constant-currency growth, and some analysts argue the stock needs closer to 47% to justify the multiple.
The cushion is the backlog. Commercial remaining performance obligations stood at about $678 billion last quarter, and Microsoft remains free-cash-flow positive — $19.6 billion in the prior quarter, down 23% year on year but still positive. Capex is guided above $50 billion this quarter, versus roughly $41 billion prior. Microsoft is the company that can spend and still pay.
The stock closed at $524.51 on Friday, above its 50-day average at $508.43 but below the 20-day at $526.70; the October closing high was $543.45.
Alphabet: negative free cash flow and a $514 billion backlog
Alphabet is the opposite case. Consensus is for revenue of $127 billion ~ $128 billion, up about 25%, and EPS of $3.00. Google Cloud is expected to grow close to 90–93%, after 82% growth to $24.8 billion in Q2. The cloud backlog is about $514 billion.
But Alphabet's 2026 capex outlook is $175 billion ~ $185 billion, and Q2 free cash flow was negative $5.9 billion; buybacks have been paused. The equity is already pricing doubt: GOOG closed at $317.28 on Friday, below its 20-, 50- and 200-day averages — all clustered near $339.5 — with a 14-day RSI of 30.9. Alphabet has the most to prove.
Amazon: AWS is the swing factor
Amazon reports after the close on October 29. AWS growth, retail margins and capex will decide whether the third hyperscaler confirms the spending story or joins the de-rating. AMZN closed at $248.00, above its 200-day average at $243.29 but below the 20- and 50-day averages at $254.43 and $255.65.
The free-cash-flow table
| Company | Report | Consensus revenue | Consensus EPS | Cloud growth | Capex / FCF | Bull case | Bear case |
|---|---|---|---|---|---|---|---|
| Microsoft | Oct 28, after close | $90.6B ~ $91B | $4.71 ~ $4.73 | Azure 44–45% cc | Capex >$50B; FCF +$19.6B prior quarter | Azure beats 47%, backlog converts, capex held | Azure misses and capex rises again |
| Alphabet | Oct 28, after close | $127B ~ $128B | about $3.00 | Cloud 90–93% | 2026 capex $175B ~ $185B; Q2 FCF -$5.9B | Cloud beats, backlog converts, 2027 capex framed | FCF stays negative; capex guide moves higher |
| Amazon | Oct 29, after close | — | — | AWS | Capex guided higher | AWS accelerates, retail margin holds | AWS slows as capex peaks |
Read the table left to right: Microsoft is the cushion, Alphabet is the test, Amazon is the swing. If cloud growth beats and capex guidance holds, the AI trade gets a second leg. If free cash flow turns negative at two of the three, the de-rating that started with Meta has more room to run.
Read more
Before making any trading decisions, it is important to equip yourself with sufficient fundamental knowledge, have a comprehensive understanding of market trends, be aware of risks and hidden costs, carefully consider investment targets, level of experience, risk appetite, and seek professional advice if necessary.
Furthermore, the content of this article is solely the author's personal opinion and does not necessarily constitute investment advice. The content of this article is for reference purposes only, and readers should not use this article as a basis for any investment decisions.
Investors should not rely on this information as a substitute for independent judgment or make decisions solely based on this information. It does not constitute any trading activity and does not guarantee any profits in trading.
If you have any inquiries regarding the data, information, or content related to Mitrade in this article, please contact us via email: insights@mitrade.com. The Mitrade team will carefully review the content to continue improving the quality of the article.


