


I Asked Anthropic's Own AI Model Whether I Should Buy the IPO. Claude's Answer Shocked Me.
Key Points
Anthropic is the artificial intelligence (AI) developer behind the Claude chatbot.
Anthropic generated $16.3 billion in revenue during the first half of the year while also trimming operating losses.
Despite the hype surrounding its IPO, investing in Anthropic comes with risks.
- 10 stocks we like better than Amazon ›
One of the most anticipated initial public offerings (IPOs) in recent memory is finally taking shape. On Oct. 26, Anthropic, the artificial intelligence (AI) company developing the popular Claude chatbot, publicly filed its S-1 registration statement with the Securities and Exchange Commission (SEC). The company intends to list on the Nasdaq under the ticker symbol ANT.
Given the excitement surrounding Anthropic's IPO, I decided to conduct an experiment. I put Anthropic's S-1 into Claude and asked whether I should buy Anthropic stock when it goes public.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
To my surprise, Claude's answer was far from an enthusiastic endorsement of its creator. Instead, it delivered a nuanced, cautious assessment of Anthropic's valuation, financial obligations, and shareholder protections. Here's what I learned.
Image source: Getty Images.
Anthropic's financial results are unbelievable
Anthropic generates revenue by selling access to its AI models. Businesses pay to use Claude for tasks such as software development, research, and the automation of administrative work. Its flagship products include Claude Code and Claude Cowork, while its models are also available through cloud platforms operated by Amazon (NASDAQ: AMZN), Microsoft (NASDAQ: MSFT), and Alphabet (NASDAQ: GOOGL) (NASDAQ: GOOG).
According to the S-1, Anthropic generated $16.3 billion in revenue during the first half of 2026. That represents nearly 1,300% year-over-year growth. However, the company's profitability needs a closer examination.
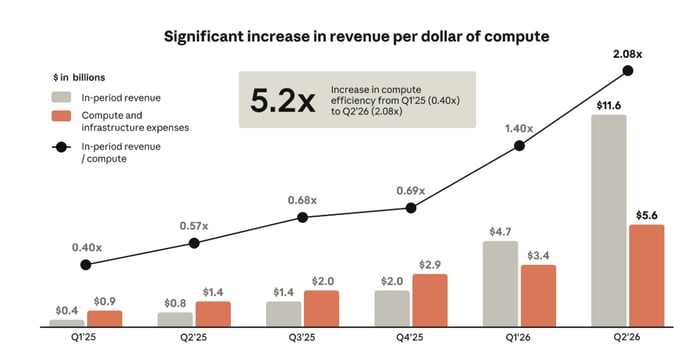
Image source: Anthropic S-1 Filing.
Anthropic reported a net loss of $80.7 billion over the first six months of 2026. At first glance, that figure might make investors question whether the business model is sustainable. Interestingly, Claude identified an important distinction from Anthropic's income statement.
Roughly $72.4 billion of the loss stemmed from changes in the accounting value of convertible securities and other financial instruments. These are largely non-cash charges associated with Anthropic's valuation rather than actual money spent on engineering.
A more useful metric for gauging Anthropic's profitability is operating income. Operating income measures profitability from a company's core business before certain financing items. Anthropic reported an operating loss of approximately $693 million, narrowing a loss of $2.1 billion during the first half of 2025.
What are the risks of the Anthropic IPO?
Claude highlighted some concerns that could complicate the company's attractiveness as a long-term investment.
The first involves AI computing costs. Developing and operating frontier models requires vast amounts of compute, much of which Anthropic obtains through capacity agreements with cloud services providers. Claude pointed out that some of these commitments extend through 2045. This is important because Anthropic could remain obligated to pay for capacity even if demand for compute slows down or newer technology erodes the economics of existing infrastructure.
Another concern involves competition from hyperscalers. Anthropic relies on Amazon Web Services (AWS) and Google Cloud for custom chips, model training, and distribution. But these companies are also developing their own AI products. In other words, some of Anthropic's most important partners are also competitors.
Claude also raised an issue involving shareholder voting rights. According to Anthropic's S-1, its seven co-founders, most notably CEO Dario Amodei, will retain 50.1% of the voting power as shareholders through a special share structure.
Should you buy the Anthropic IPO?
The most interesting part of my experiment came when Claude evaluated Anthropic at three hypothetical valuations: $500 billion, $1 trillion, and $2 trillion.
Anthropic's $16.3 billion in revenue during the first half of 2026 translates into approximately $32.6 billion on an annualized basis. This simply doubles the first-half figure; it isn't a formal forecast of actual full-year revenue. At a $500 billion valuation, Anthropic would trade at a price-to-sales (P/S) ratio of 15. Claude suggested that a small speculative investment could make sense at this price.
At a $1 trillion valuation, Anthropic's P/S multiple in this exercise would jump to 31. Claude recommended passing on the IPO at that price, arguing that investors would be paying for years of outsize growth. Given that opinion, clearly a $2 trillion IPO and a 61 times P/S ratio is a non-starter from Claude's perspective.
It's important to understand that these were hypothetical scenarios, not Anthropic's actual IPO price range. The company has not yet established its offering price or final share count.
Ultimately, Claude's conclusion reinforces one of investing's most important principles: A great company isn't necessarily a great stock at any price. For investors considering the upcoming IPO, Claude's recommendation was straightforward: Wait for the final prospectus, understand the mechanics of the company's financial obligations, and don't confuse excitement about a new AI stock with a reason to chase momentum and overpay. That is how unsuspecting investors end up holding the bag.
Should you buy stock in Amazon right now?
Before you buy stock in Amazon, consider this:
The Motley Fool Stock Advisor analyst team just identified what they believe are the 10 best stocks for investors to buy now… and Amazon wasn’t one of them. The 10 stocks that made the cut could produce monster returns in the coming years.
Consider when Netflix made this list on December 17, 2004... if you invested $1,000 at the time of our recommendation, you’d have $355,124!* Or when Nvidia made this list on April 15, 2005... if you invested $1,000 at the time of our recommendation, you’d have $1,296,254!*
Now, it’s worth noting Stock Advisor’s total average return is 901% — a market-crushing outperformance compared to 210% for the S&P 500. Don't miss the latest top 10 list, available with Stock Advisor, and join an investing community built by individual investors for individual investors.
See the 10 stocks »
*Stock Advisor returns as of October 27, 2026.
Adam Spatacco has positions in Alphabet, Amazon, and Microsoft. The Motley Fool has positions in and recommends Alphabet, Amazon, and Microsoft. The Motley Fool has a disclosure policy.
Recommended Articles


