


Celestica Stock Forecast: CLS Eyes C$380 as a $40 Billion 2027 Outlook Sparks a Premarket Rebound
TradingKey - Celestica (TSX: CLS) fell 4.78% to C$346.97 in Toronto on Monday, October 26, its third straight loss and about 37% below its October 6 close of C$551.79. In New York, the shares closed down 5.14% at $246.65 before the company reported third-quarter results after the bell.
The results turned that around. The New York shares rose 15.51% to $284.90 in early premarket trade on Tuesday, which works out to roughly C$400 at Monday's exchange rate, by my calculation. That would put the stock back above the key C$379.86 level when Toronto opens.
Q3 Beat Its Own Guidance
Celestica reports in US dollars. Revenue rose 83% to $5.83 billion, above the $5.44 billion consensus and the top of its $5.25 billion to $5.55 billion guidance range. Adjusted EPS, which excludes items such as stock-based pay and amortization, more than doubled to $3.30 against $2.99 expected, while GAAP EPS rose to $3.26 from $2.31. The adjusted operating margin improved to 8.5% from 7.6%.
Most of that growth came from data centers. The Connectivity and Cloud Solutions segment, which builds networking and data center hardware, grew revenue 102% to $4.87 billion. Advanced Technology Solutions rose 23% to $960 million.
The $40 Billion 2027 Outlook
Celestica raised its 2026 forecast to $21.0 billion in revenue, from $20.5 billion, and adjusted EPS of $11.55, from $11.30. For the fourth quarter, it expects revenue of $6.275 billion to $6.575 billion and adjusted EPS of $3.37 to $3.57.
The bigger surprise was its first 2027 outlook: revenue of $40.0 billion, up 90%, adjusted EPS of $21.50, a 9.0% adjusted operating margin and capex of $1.5 billion to $2.0 billion. CEO Rob Mionis added that customer demand forecasts are "meaningfully higher for 2028."
That runs against the fear behind the recent selloff. Toronto shares dropped 12% on October 22 alone as AI hardware stocks sold off, yet Celestica is guiding for 90% growth next year, not a slowdown.
Three Customers Drive Two-Thirds of Sales
The growth depends on very few buyers. According to its quarterly filing, three customers in the data center segment made up 35%, 17% and 14% of third-quarter revenue, or 66% combined, up from 30%, 15% and 14% a year earlier. The filing does not name them, so a spending cut at one large cloud customer could hit results hard.
Cash Flow Is the Weak Spot
Celestica cut its 2026 free cash flow forecast to $460 million from $600 million, as it puts more money into working capital for 2027 growth. Free cash flow is the cash left after operating costs and capital spending. Inventory has more than doubled this year to $4.51 billion from $2.19 billion. In August, Celestica also sold 11.1 million new shares, raising about $3.39 billion after costs.
The company plans a new share buyback in the fourth quarter, after its current program expires on November 2, which could cover up to 2.5% of its public float over 12 months.
Valuation and Analysts
At the premarket price, CLS trades at about 13 times its 2027 adjusted EPS guide, a modest multiple for a company guiding to 90% growth. Average analyst targets sit around $465 to $468, far above even the premarket price. The results call and Investor and Analyst Day begin at 8:00 a.m. ET today, where 2028 demand and customer mix are likely to draw the most questions.
Celestica Technical Analysis: 4-Hour Close Above C$379.86 Could Open C$426.91
Before the results, the 4-hour chart showed a steady decline. Since its early-October peak near C$560, CLS has fallen inside a downward-sloping channel, two parallel lines that contain a falling trend. Monday's drop pushed price below C$379.86 support, and the stock trades far below both moving averages, which track the average price over a set period, so sellers are firmly in control.
RSI, a momentum gauge that runs from 0 to 100, dropped to about 25, deep below the 30 oversold line, a sign that selling may be overdone.
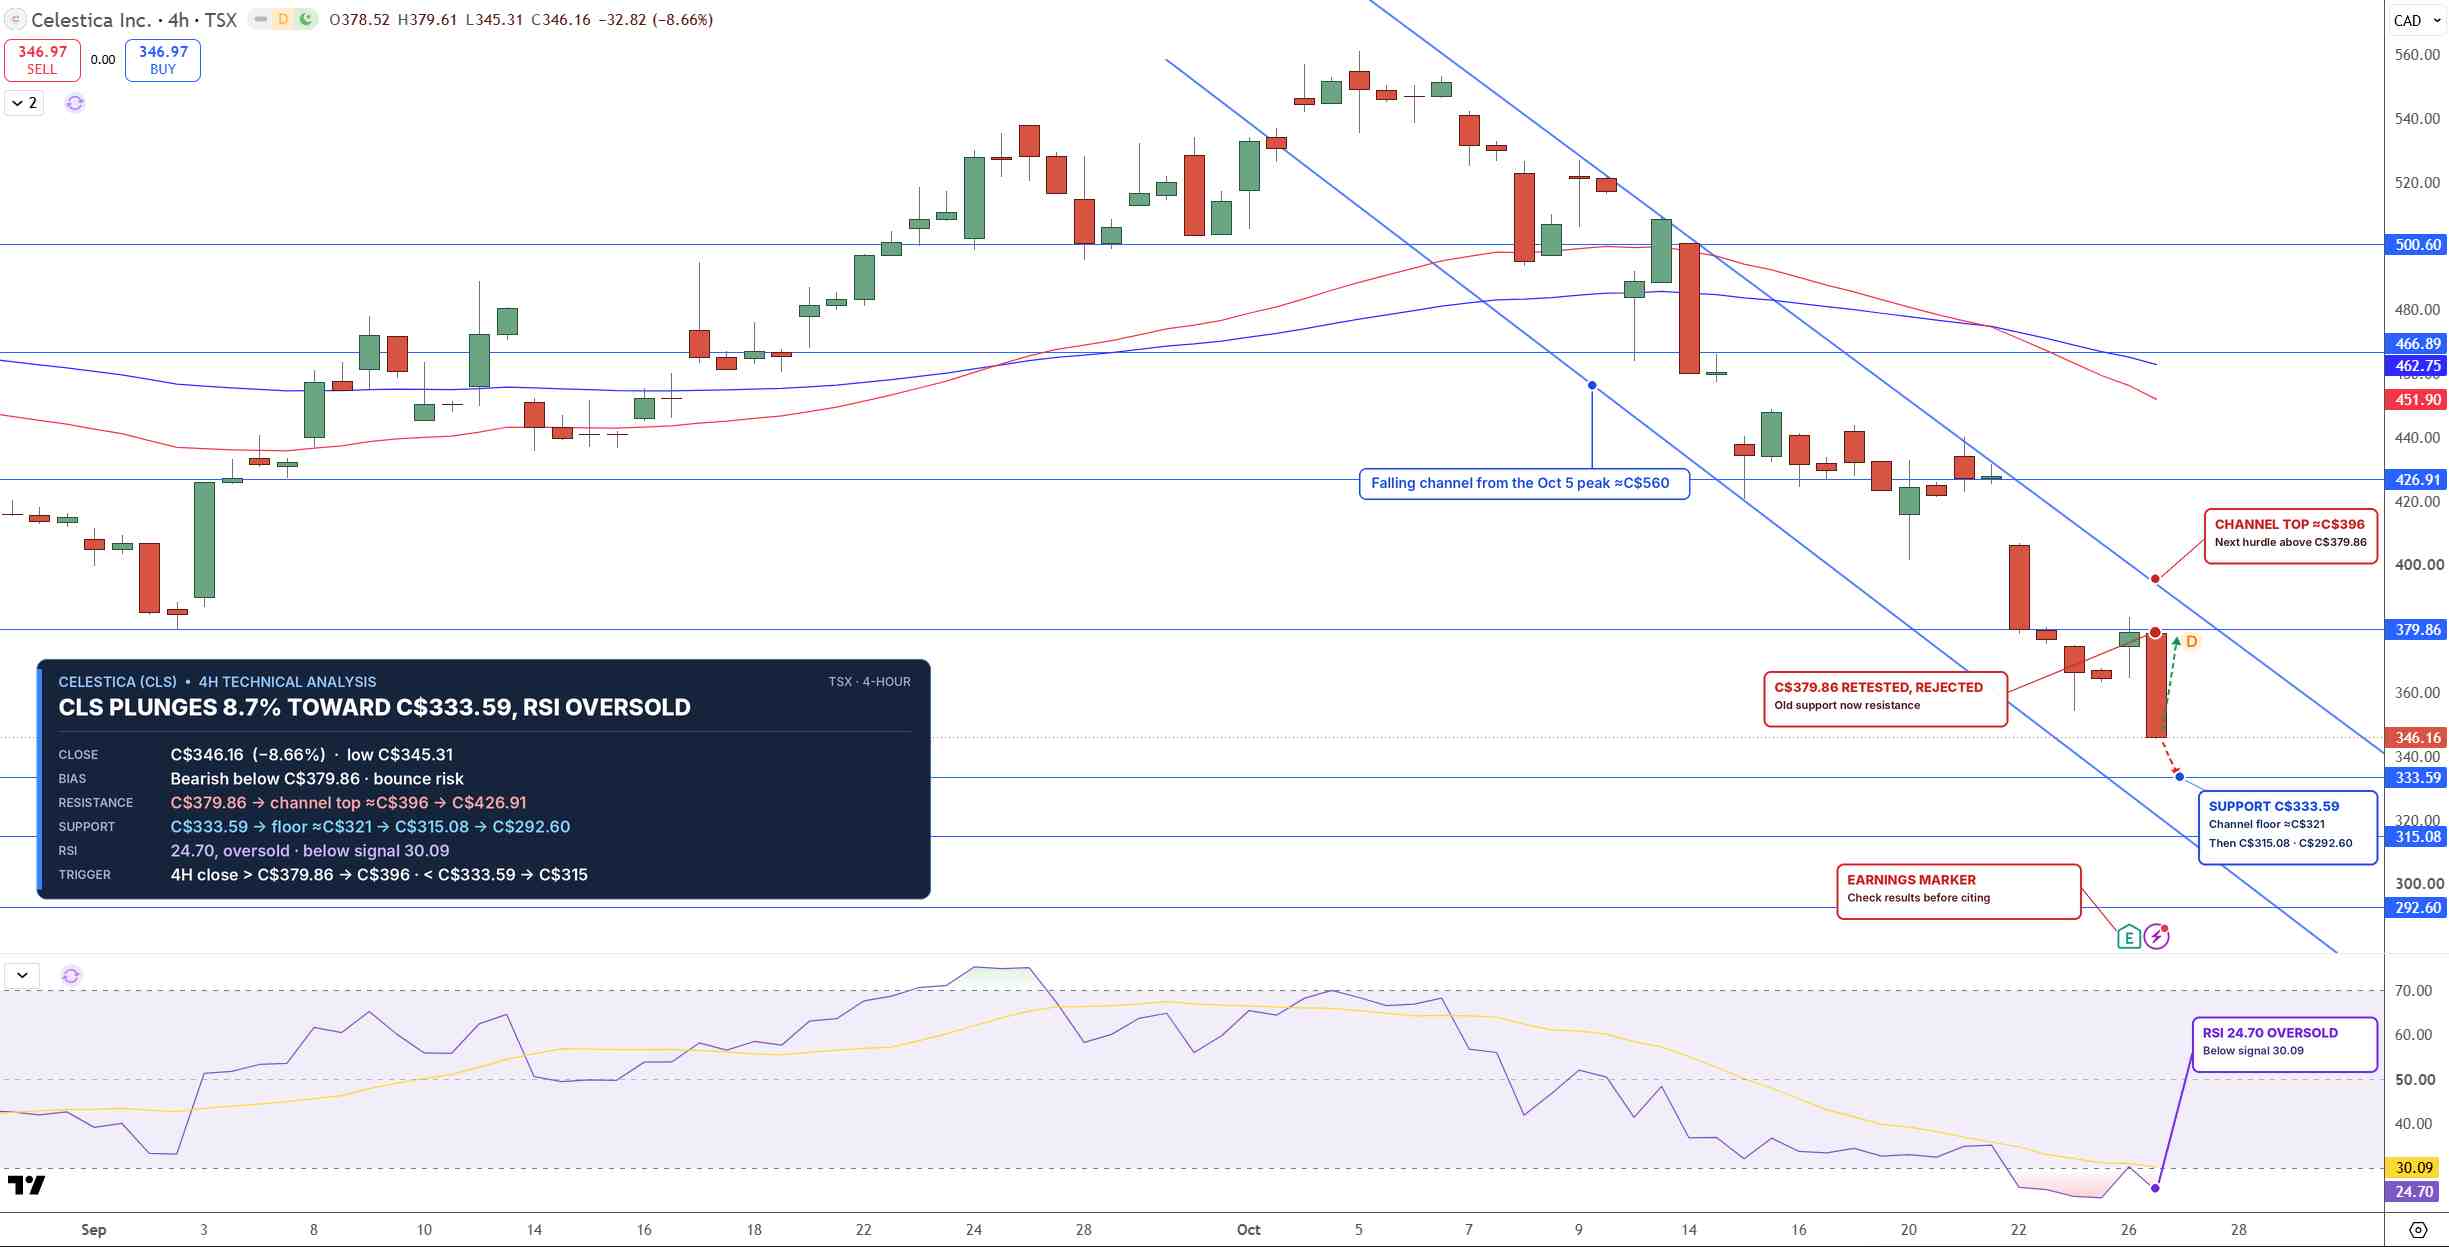
CLS Price Chart - Source: Tradingview
That makes C$379.86 the level to watch today. A 4-hour close back above it would be the first sign of recovery and could open C$426.91. If the premarket gain fades, C$333.59 is the next support, just above the 52-week low of C$330.79, and a break there would open C$315.08.
I'm bearish while CLS stays below C$379.86, though oversold conditions could spark a brief rebound, and the premarket jump suggests that test may come at the open.
Key Levels
- Last close: C$346.97, down 4.78% on October 26 (TSX)
- Support: C$333.59, C$315.08, C$292.60
- Resistance: C$379.86, C$426.91, C$451.90, C$462.75
- RSI: 24.70, oversold
- Bullish trigger: 4-hour close above C$379.86
- Bearish trigger: 4-hour close below C$333.59
FAQs
Why is Celestica stock rising after earnings?
Celestica beat Q3 estimates with revenue up 83% to $5.83 billion and adjusted EPS of $3.30, raised its 2026 outlook and guided to $40.0 billion of revenue in 2027, up 90%. Its New York shares rose 15.51% premarket on October 27.
What is the Celestica stock forecast now?
The 4-hour chart is bearish below C$379.86. A 4-hour close above C$379.86 would open C$426.91, while a close below C$333.59 would open C$315.08 and C$292.60.
Bottom Line
Celestica's numbers challenge the idea that AI hardware demand is peaking, though three customers now drive two-thirds of its sales and cash flow is under pressure. The level that matters is C$379.86. In my view, a 4-hour close above it would end the downtrend's control and open C$426.91, while a failure there would put C$333.59 back in focus.
Recommended Articles


