


Fair Isaac Corp Stock (FICO) Moved Down by 25.97% on Sep 29: Facts Behind the Movement
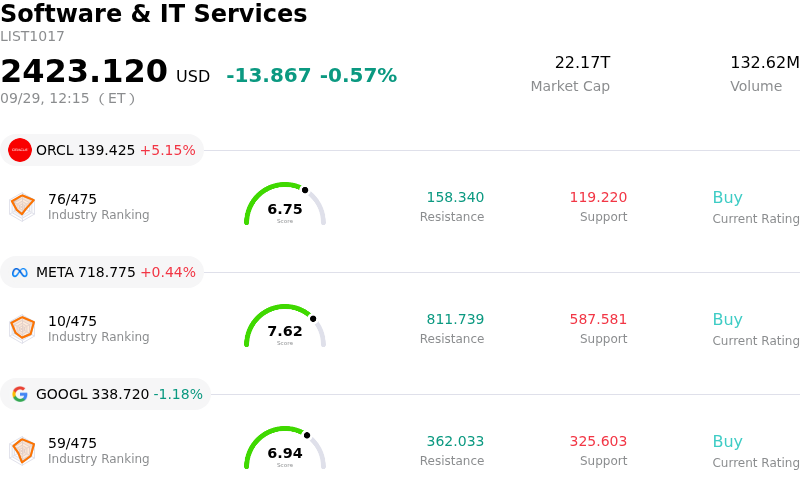
Fair Isaac Corp (FICO) moved down by 25.97%. The Software & IT Services sector is down by 0.57%. The company underperformed the industry. Top 3 stocks by turnover in the sector: Oracle Corp (ORCL) up 5.14%; Meta Platforms Inc (META) up 0.44%; Alphabet Inc Class A (GOOGL) down 1.18%.
What is driving Fair Isaac Corp (FICO)’s stock price down today?
Fair Isaac Corporation experienced severe downward pressure following major regulatory developments that directly threaten its long-standing dominance in the mortgage credit-scoring market. The Federal Housing Finance Agency announced that government-sponsored enterprises Fannie Mae and Freddie Mac will adopt a single loan-level pricing adjustment grid covering both FICO and VantageScore. This decision eliminates the pricing framework that previously forced mortgage lenders to rely almost exclusively on FICO scores to secure conventional loan approvals. By placing VantageScore on equal footing, the agency removed a primary structural barrier, permitting lenders to evaluate borrowers using alternative scoring models without incurring higher risk-based fees.
The market reaction was further amplified by aggressive competitive moves across the credit industry. TransUnion extended its discounted pricing strategy for VantageScore through late 2028, significantly undercutting FICO's fee structure. Concurrently, major mortgage originators, including Rocket Mortgage, signaled a shift toward adopting VantageScore as a preferred credit-scoring model for eligible loans. These developments have heightened fears among investors regarding score shopping, a process where lenders choose whichever scoring model yields a lower interest rate for the borrower. Analyst commentary noted that this dynamic could severely erode FICO's pricing power and shrink its market share in the highly profitable mortgage origination segment.
From a strategic perspective, the breakdown of FICO's regulatory moat fundamentally alters its long-term growth thesis. Although the company continues to generate steady cash flows from its software and enterprise analytics divisions, its scores segment has historically benefited from near-monopolistic pricing power. Analysts warn that Fair Isaac may be forced to restructure its per-pull fee model to protect its economics, leading Wall Street to sharply re-evaluate the stock's valuation multiple. The sudden transition from an entrenched monopoly to direct price competition has sparked widespread risk aversion, driving institutional portfolios to reduce exposure.
Technical Analysis of Fair Isaac Corp (FICO)
Technically, Fair Isaac Corp (FICO) shows a MACD (12,26,9) value of -47.312, indicating a sell signal. The RSI at 16.666 suggests oversold condition and the Williams %R at 93.479 suggests oversold condition. Please monitor closely.
Fundamental Analysis of Fair Isaac Corp (FICO)
Fair Isaac Corp (FICO) is in the Software & IT Services industry. Its latest annual revenue is $1.99B, ranking 127 in the industry. The net profit is $651.95M, ranking 59 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $1458.68, a high of $1750.00, and a low of $696.00.
More details about Fair Isaac Corp (FICO)
Company Specific Risks:
- FHFA Regulatory Directives and Loss of Mortgage Dominance: Federal Housing Finance Agency policy updates and loan-level price adjustment grid changes have placed competing VantageScore 4.0 on equal footing with Classic FICO, triggering immediate adoption by major lenders like Rocket Mortgage and breaking FICO's longstanding quasi-monopoly in government-conforming mortgage scoring.
- Aggressive Competitor Pricing and Margin Compression: TransUnion's extension of 99-cent promotional pricing for VantageScore 4.0 through December 2028 directly undercuts FICO's higher-cost per-pull fees, creating severe unit volume headwind and eroding pricing power within FICO's highest-margin B2B Scores segment.
- Analyst Downgrades and Business Model Disruption: Wall Street analysts, including Autonomous Research cutting its price target to $600, warned that widespread lender "score shopping" may force FICO to prematurely abandon its traditional per-pull origination fee model, introducing operational execution risks and revenue instability.
- Elevated Balance Sheet Leverage Amid Revenue Trajectory Risks: FICO's draw of a $1.5 billion term loan facility to execute aggressive share repurchases increases fixed financial obligations and balance sheet leverage, amplifying financial downside just as core scoring revenues face heightened competitive pressure.
Recommended Articles


