




Is Dutch Bros Stock a Buy as Shares Plunge?
Key Points
Dutch Bros turned in a solid quarter, although investors worry about increased competition and slowing same-store sales growth.
The stock is very cheap given its growth potential.
- 10 stocks we like better than Dutch Bros ›
For the second time in two quarters, Dutch Bros (NYSE: BROS) shares collapsed following its earnings report, as investors fear that increasing competition is starting to eat into its growth. However, the company's overall same-store sales growth is still solid in a difficult consumer environment, and it continues to have one of the best expansion opportunities in the restaurant space.
The stock is now down more than 40% on the year, reversing the strong momentum the stock saw earlier in 2026. This looks like a golden opportunity to buy Dutch Bros in my view, as the stock's long-term underlying investment thesis remains unchanged.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Let's take a closer look at the coffee shop operator's third-quarter results and prospects and why I think it is a buy on this dip.
Image source: The Motley Fool
A top expansion story
The biggest reason to own Dutch Bros is that it is one of the best expansion stories in the consumer space. The company opened 48 shops in Q3, of which 42 were company-opened, and plans to open at least 185 this year. It ended the quarter with 1,273 locations, of which 960 were company-owned shops. Meanwhile, it forecasted that it will open around 250 locations in 2027, which would be about 19% growth.
The company said it now has full visibility with its real estate pipeline to reach its goal of 2,029 shops in 2029. Its longer-term goal is to have 7,000 shops in the U.S., and it said it's being deliberate about how and where it grows, and it's not just simply about opening new locations and entering new states. In 2027, it plans to open most of its new shops in existing markets to benefit from increased density and to build brand awareness in these markets.
Dutch Bros shops typically have smaller footprints with two drive-thrus and no indoor seating, and are cost-efficient to build. This lets the company fund expansion fully with its operating cash flow. And while its shops are small, they generate a lot of revenue per location, with average unit volume (AUV) of more than $2.2 million. That helps the company get quick paybacks on new stores, increasing cash flow, and letting it funnel that back into new shops.
Dutch Bros also continues to deliver solid same-store sales. For Q3, comparable-store sales rose by 4.4%, as traffic increased by 0.4%. Company-owned stores yet again outperformed, with comparable-shop sales jumping 5.4% on a 1% increase in visits. The company credited its brand marketing and its rewards program for the growth.
CEO Cristine Barone said the company saw increased choppiness in Q3, but didn't feel that came from any increased competition. Instead, she blamed rising gas prices and said that its mix from energy drinks grew during the quarter despite a big competitor's launch in Q3. The company plans to continue to lean into menu innovation, including launching a matcha platform in 2027.
Dutch Bros' overall revenue climbed 29.8% to $549.8 million, while earnings per share (EPS) jumped 43% to $0.20. Adjusted earnings before interest, taxes, depreciation, and amortization (EBITDA) climbed 30% to $101.1 million.
Looking ahead, Dutch Bros projected 2026 revenue to be at least $2.1 billion compared to prior guidance for revenue of between $2.1 billion to $2.13 billion. Same-store sales are expected to be up at least 5%, which is below the 5.5% level the company said it was trending toward last quarter. It now expects adjusted EBITDA of roughly $380 million, down from its previous forecast of $385 million to $390 million.
Why the stock is a buy
Same-store growth in the restaurant industry is never a linear path, and there will be ups and downs based on things like the strength of the consumer and the lapping of popular new menu items. I would not be overly concerned with slightly slower same-store growth from Dutch Bros in what has been a tough consumer environment this year due to high gas prices stemming from the war in Iran and elevated overall inflation because of tariffs.
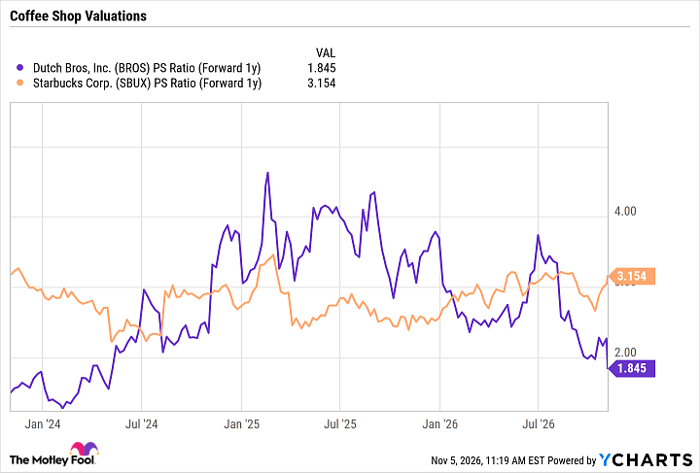
The recent sell-off, meanwhile, has put the stock squarely in the bargain bin. It now trades at a forward price-to-sales (P/S) ratio of 1.9, which is well below Starbucks' 3.2 multiple, despite Dutch Bros having the much larger growth runway ahead. Meanwhile, earnings growth will continue to climb at a faster pace than revenue as the company scales and spreads out fixed corporate costs over a larger base.
BROS PS Ratio (Forward 1y) data by YCharts
Dutch Bros is a top growth stock trading at a big discount, making the stock a buy following this sell-off.
Should you buy stock in Dutch Bros right now?
Before you buy stock in Dutch Bros, consider this:
The Motley Fool Stock Advisor analyst team just identified what they believe are the 10 best stocks for investors to buy now… and Dutch Bros wasn’t one of them. The 10 stocks that made the cut could produce monster returns in the coming years.
Consider when Netflix made this list on December 17, 2004... if you invested $1,000 at the time of our recommendation, you’d have $341,966!* Or when Nvidia made this list on April 15, 2005... if you invested $1,000 at the time of our recommendation, you’d have $1,146,819!*
Now, it’s worth noting Stock Advisor’s total average return is 852% — a market-crushing outperformance compared to 203% for the S&P 500. Don't miss the latest top 10 list, available with Stock Advisor, and join an investing community built by individual investors for individual investors.
See the 10 stocks »
*Stock Advisor returns as of November 8, 2026.
Geoffrey Seiler has positions in Dutch Bros. The Motley Fool has positions in and recommends Dutch Bros and Starbucks. The Motley Fool has a disclosure policy.
Recommended Articles


