




Before You Invest a Dollar, Figure Out How Much You're Actually Allowed to Invest
Key Points
Your buffer for rent and necessities comes off the top, before the first dollar reaches a brokerage account.
The cash reserve belongs in a high-yield savings or money market account.
Automatic monthly contributions beat one big deposit, because they remove the monthly investment decision entirely.
- The $23,760 Social Security bonus most retirees completely overlook ›
Somebody I know is 19 years old with $21,000 sitting in a checking account. The kid wanted to know what to buy. That's the wrong question, but a fair one.
The instinct is to jump straight to stock picking. That's what I did in 2004, unfortunately. The correct first move is figuring out how much of that money is not actually available to invest.
Missed AI’s "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our analysts, we’re only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
Step one: Rent is the boss of this conversation
Rent does not care about the market. It's a fixed, recurring, non-negotiable obligation. So are utilities, insurance, a phone bill, groceries, and transportation. Some would add a gym membership; others have expensive sourdough baking habits. Add those up, and the result is a monthly burn rate. Call it $1,800 for a student splitting an apartment near campus.
If you have a steady job, take that monthly burn rate and multiply it by three. If you don't have that predictable paycheck, multiply by six instead. That is the pile that stays in cash, and it is not negotiable, and yes, it is going to feel like an annoyingly large number. For my inquisitive student with stipends and a part-time job, let's call it a steady income and set aside $5,400 for the non-negotiable necessities.
What is left after that subtraction is the actual investable money. It's often less than what people assume. In this example, it's about $15,600.

Image source: Getty Images.
Step two: Your checking account is quietly robbing you
Big-bank checking accounts pay essentially nothing. Round it to 0% and nobody will correct you. Meanwhile, inflation keeps doing what inflation does. At the long-term average inflation rate of 3.2%, my young friend's $21,000, left idle, loses roughly $650 in buying power per year. The statement still says $21,000. The same money just buys less stuff over time. That's by design, by the way -- central banks want to keep a modest inflation rate to inspire more spending and less saving.
The fix takes about fifteen minutes on a phone. Open a high-yield savings or money market account at an online bank, park the rent buffer there, and link it back to your day-to-day checking account. It's FDIC-insured, transfers land in a day or two, and suddenly, the boring money is earning approximately 4% a year instead of nothing. Same safety, same liquidity, a slightly inflation-beating rate. There is no catch and no downside worth mentioning. No, the paperwork for setting up the interest-bearing savings doesn't count.
Step three: Choose the account before choosing the investment
With the buffer addressed, what remains can go to market.
First question is not "which stock." It is "which account."
A Roth IRA takes money that has already been taxed and then never taxes it again, which is an outrageously good deal for anybody currently in a low tax bracket.
But of course, there's a catch. A Roth account requires earned income. Actual wages from an actual job. Birthday money does not count. Luckily, the ambitious student in my example found a part-time gig with a local engineering company.
There is also an annual limit, so a $21,000 pile cannot cannonball into a Roth all at once. In 2026, the annual limit is $7,500 in most cases, though contributions can't exceed your earned income that year. It fills up over several years, and anything waiting its turn can sit in a regular brokerage account doing productive work in the meantime.
And if there is a job with a 401(k) match sitting unclaimed somewhere, go get that first. An employer match is the only guaranteed instant return in this entire field. Everything else in investing is a probability. That one is a certainty, and leaving it on the table is like asking for a smaller paycheck.
Step four: The fund selection is the easy part
Buy the whole market and stop thinking about it.
The Vanguard S&P 500 ETF (NYSEMKT:VOO) holds 500 large American companies and has an annual expense ratio of 0.03%, which is effectively a rounding error. If the amount of trillion-dollar stocks like Nvidia and Tesla packed into the top of the S&P 500 (SNPINDEX:^GSPC) index gives you hives, the Invesco S&P 500 Equal Weight ETF (NYSEMKT:RSP) holds the same companies in equal slices for a 0.20% expense ratio.
Going the equal-weighted route is a choice, not a guaranteed upgrade. Sometimes it wins, sometimes it loses. At best, anyone who tells you which is coming next is guessing with confidence.
Step five: Form an investing habit
A single large deposit makes for a clean chart. It is not the mechanism that builds wealth.
The secret sauce is automatic monthly contributions, forever, ignored entirely. Your employer may offer 401(k) deductions from your paycheck. Otherwise, every stock brokerage worth considering will make it easy to set up monthly contributions.
Either way, an investor who contributes every month, regardless of the headlines, will buy during downturns without having to summon any courage. And don't forget to enable dividend reinvestments right away. It's one checkbox that makes a big difference to your multi-decade total returns.
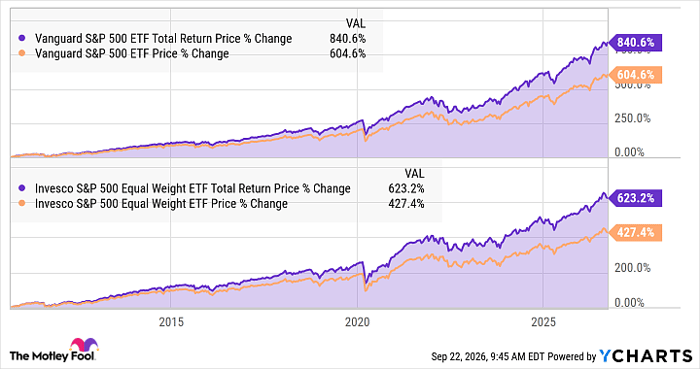
VOO Total Return Price data by YCharts
The unavoidable disclaimer
Stocks fall. The S&P 500 lost about half its value in the 2008 meltdown and shed roughly 18% in the inflation crisis of 2022. Both recoveries happened, and both took long enough to hurt. Anybody putting money into the market should assume a serious drop is coming at some point, possibly next month, and plan to do absolutely nothing about it when it arrives. Selling during a crash simply locks in poor returns.
I am not a Certified Financial Planner®. If I were, I would still give you a bad idea every now and then. But keeping a real cash buffer, parking it somewhere that pays, and feeding a cheap index fund on a schedule is about as close to a solved problem as personal finance gets.
The $23,760 Social Security bonus most retirees completely overlook
If you're like most Americans, you're a few years (or more) behind on your retirement savings. But a handful of little-known "Social Security secrets" could help ensure a boost in your retirement income.
One easy trick could pay you as much as $23,760 more... each year! Once you learn how to maximize your Social Security benefits, we think you could retire confidently with the peace of mind we're all after. Join Stock Advisor to learn more about these strategies.
View the "Social Security secrets" »
Anders Bylund has positions in Invesco S&P 500 Equal Weight ETF, Nvidia, and Vanguard S&P 500 ETF. The Motley Fool has positions in and recommends Nvidia, Tesla, and Vanguard S&P 500 ETF. The Motley Fool has a disclosure policy.
Recommended Articles


