


Why altcoin season isn't coming back — and what stole its capital
If, after two years of being frozen in ice, Katara and Sokka woke you up to the crypto market, it would seem like 100 years have passed.
With Bitcoin soaring to record highs just over a year ago, everyone expected a routine altcoin season, where investors take profits from the top crypto to chase higher returns in altcoins.
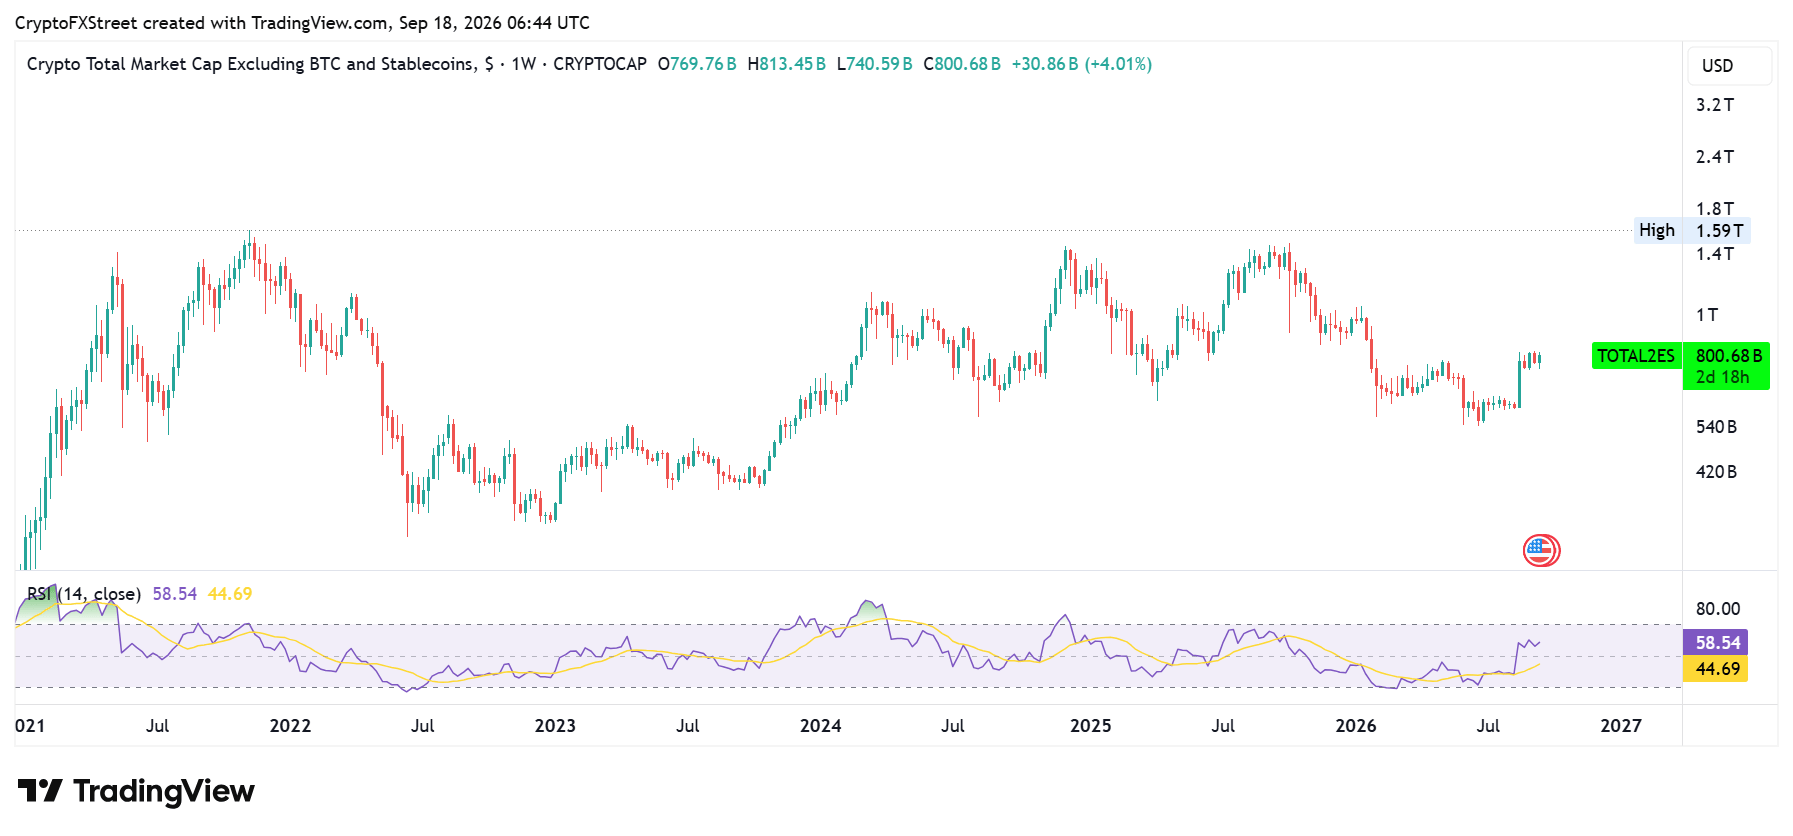
However, that season failed to materialize as the global crypto market capitalization crashed over 50% between October 2025 and June. Altcoins' market cap fell from $1.49 trillion to $543 billion.
Before the crash, Bitcoin grew roughly 8x from a $15,500 low to a peak above $126,000. On a cycle-top comparison, Bitcoin’s market cap gained roughly 90% between two cycles spanning 2021 and 2025, nearly doubling its size to $2.48 trillion.
In the same period, the global crypto market jumped roughly 50% between two cycle tops. Do you know what failed to grow meaningfully during that timeframe? Altcoins.
The altcoin market cap moved 5.1x to $1.49 trillion last October from a low of $292 billion. On a cycle-top basis, it fell 6% from $1.59 trillion over four years before the bear season crash.
So much for being a high-beta play on Bitcoin.
Compared to the 2017 and 2021 cycles, altcoins outperformed Bitcoin by roughly 350x vs. 20x and 35x vs. 22x, respectively. During those times, Bitcoin Dominance dropped from 95% to 31% and from 73% to 38%. This cycle, it stayed firm in the 50-60% range.
The big question is, what changed this cycle?
The two earlier cycles had primary structural drivers that pushed attention back to native cryptocurrencies.
The Initial Coin Offering (ICO) boom of 2017 enabled the creation of cryptocurrencies and decentralized applications without passing through the arduous process of launching a new blockchain network. Similar to the dotcom bubble, investors poured money into the promises of these coins and applications, expanding the overall altcoin market before the eventual crash.
The 2020/21 cycle had several structural drivers, including DeFi Summer, non-fungible tokens (NFTs) and the Layer-1 (L1) Wars. This cycle gave rise to the modern altcoin market, with several altcoins gaining ground on the promise of innovative use cases.
One underlying theme in both cycles is how their structural drivers attracted new capital into altcoins, which further expanded the crypto market.
-1789725491322.png)
However, that didn't happen in the 2024/25 cycle, which filtered into 2026. Don't get me wrong. The crypto market saw major structural changes this cycle — the launch of spot crypto Exchange Traded Funds (ETFs), memecoin launchpads, tokenization, a favorable regulatory environment, etc. While all these changes expanded the crypto market, many of them came at the expense of an altcoin season. But how?
New markets, new investor behavior
An expanded market means investors have a wider range of options to chase new returns, unlike earlier times when altcoins were the focus. And this time around, the cycle's main structural drivers didn't create new entry points for capital to flow into altcoins.
These new markets/structural drivers are increasingly grabbing mindshare from altcoins.
Initially, the promise of the cycle was laying the foundation for crypto to merge with TradFi. The two primary drivers for that expectation were US spot crypto ETFs and real-world assets (RWAs).
Experts, analysts, traders, executives and others predicted these two solutions would pull massive capital into crypto and, in turn, spark outsized returns in several cryptocurrencies.
ETFs only enlarged the big boys further
With the launch of spot BTC ETFs in January 2024, Bitcoin saw a massive influx of new capital, with their total net assets reaching $150.77 billion by October 2025, spearheading Bitcoin's rally to a $126,000 record high. Ethereum saw a similar move following the launch of spot ETH ETFs, which attracted total net assets of $28.58 billion between July 2024 and August 2025.
However, the opposite has been true so far for altcoins. While XRP and SOL ETFs have attracted roughly $1.58 billion and $1.46 billion, respectively, within a year of launching, other altcoin products, including BNB, AVAX, DOGE, DOT, and LTC ETFs, have barely crossed $20 million in net assets.
Those figures for altcoin products are barely a scratch of the "influx of massive capital" many expected. One thing is clear. ETFs mainly strengthened Bitcoin and Ethereum dominance in the crypto market, leaving altcoins to search for other catalysts to spur the long-awaited altcoin season.
If ETFs didn't do it, maybe tokenization can
I mean, if BlackRock, JP Morgan, NYSE, Nasdaq, and several other giants are touting tokenization as the future of finance and asset management — and that's almost entirely what crypto is designed to solve — who dares think it won't spark a grand-scheme altcoin season? I mean, Bitcoin doesn't have a direct stake in this since it is not a smart contract blockchain and does not host trading venues for tokenized assets. It looked like the perfect setup to shift attention to altcoins, no?
With all the hype and big expectations surrounding it, RWAs — both tokenized and perpetual RWAs — didn't fail to deliver.
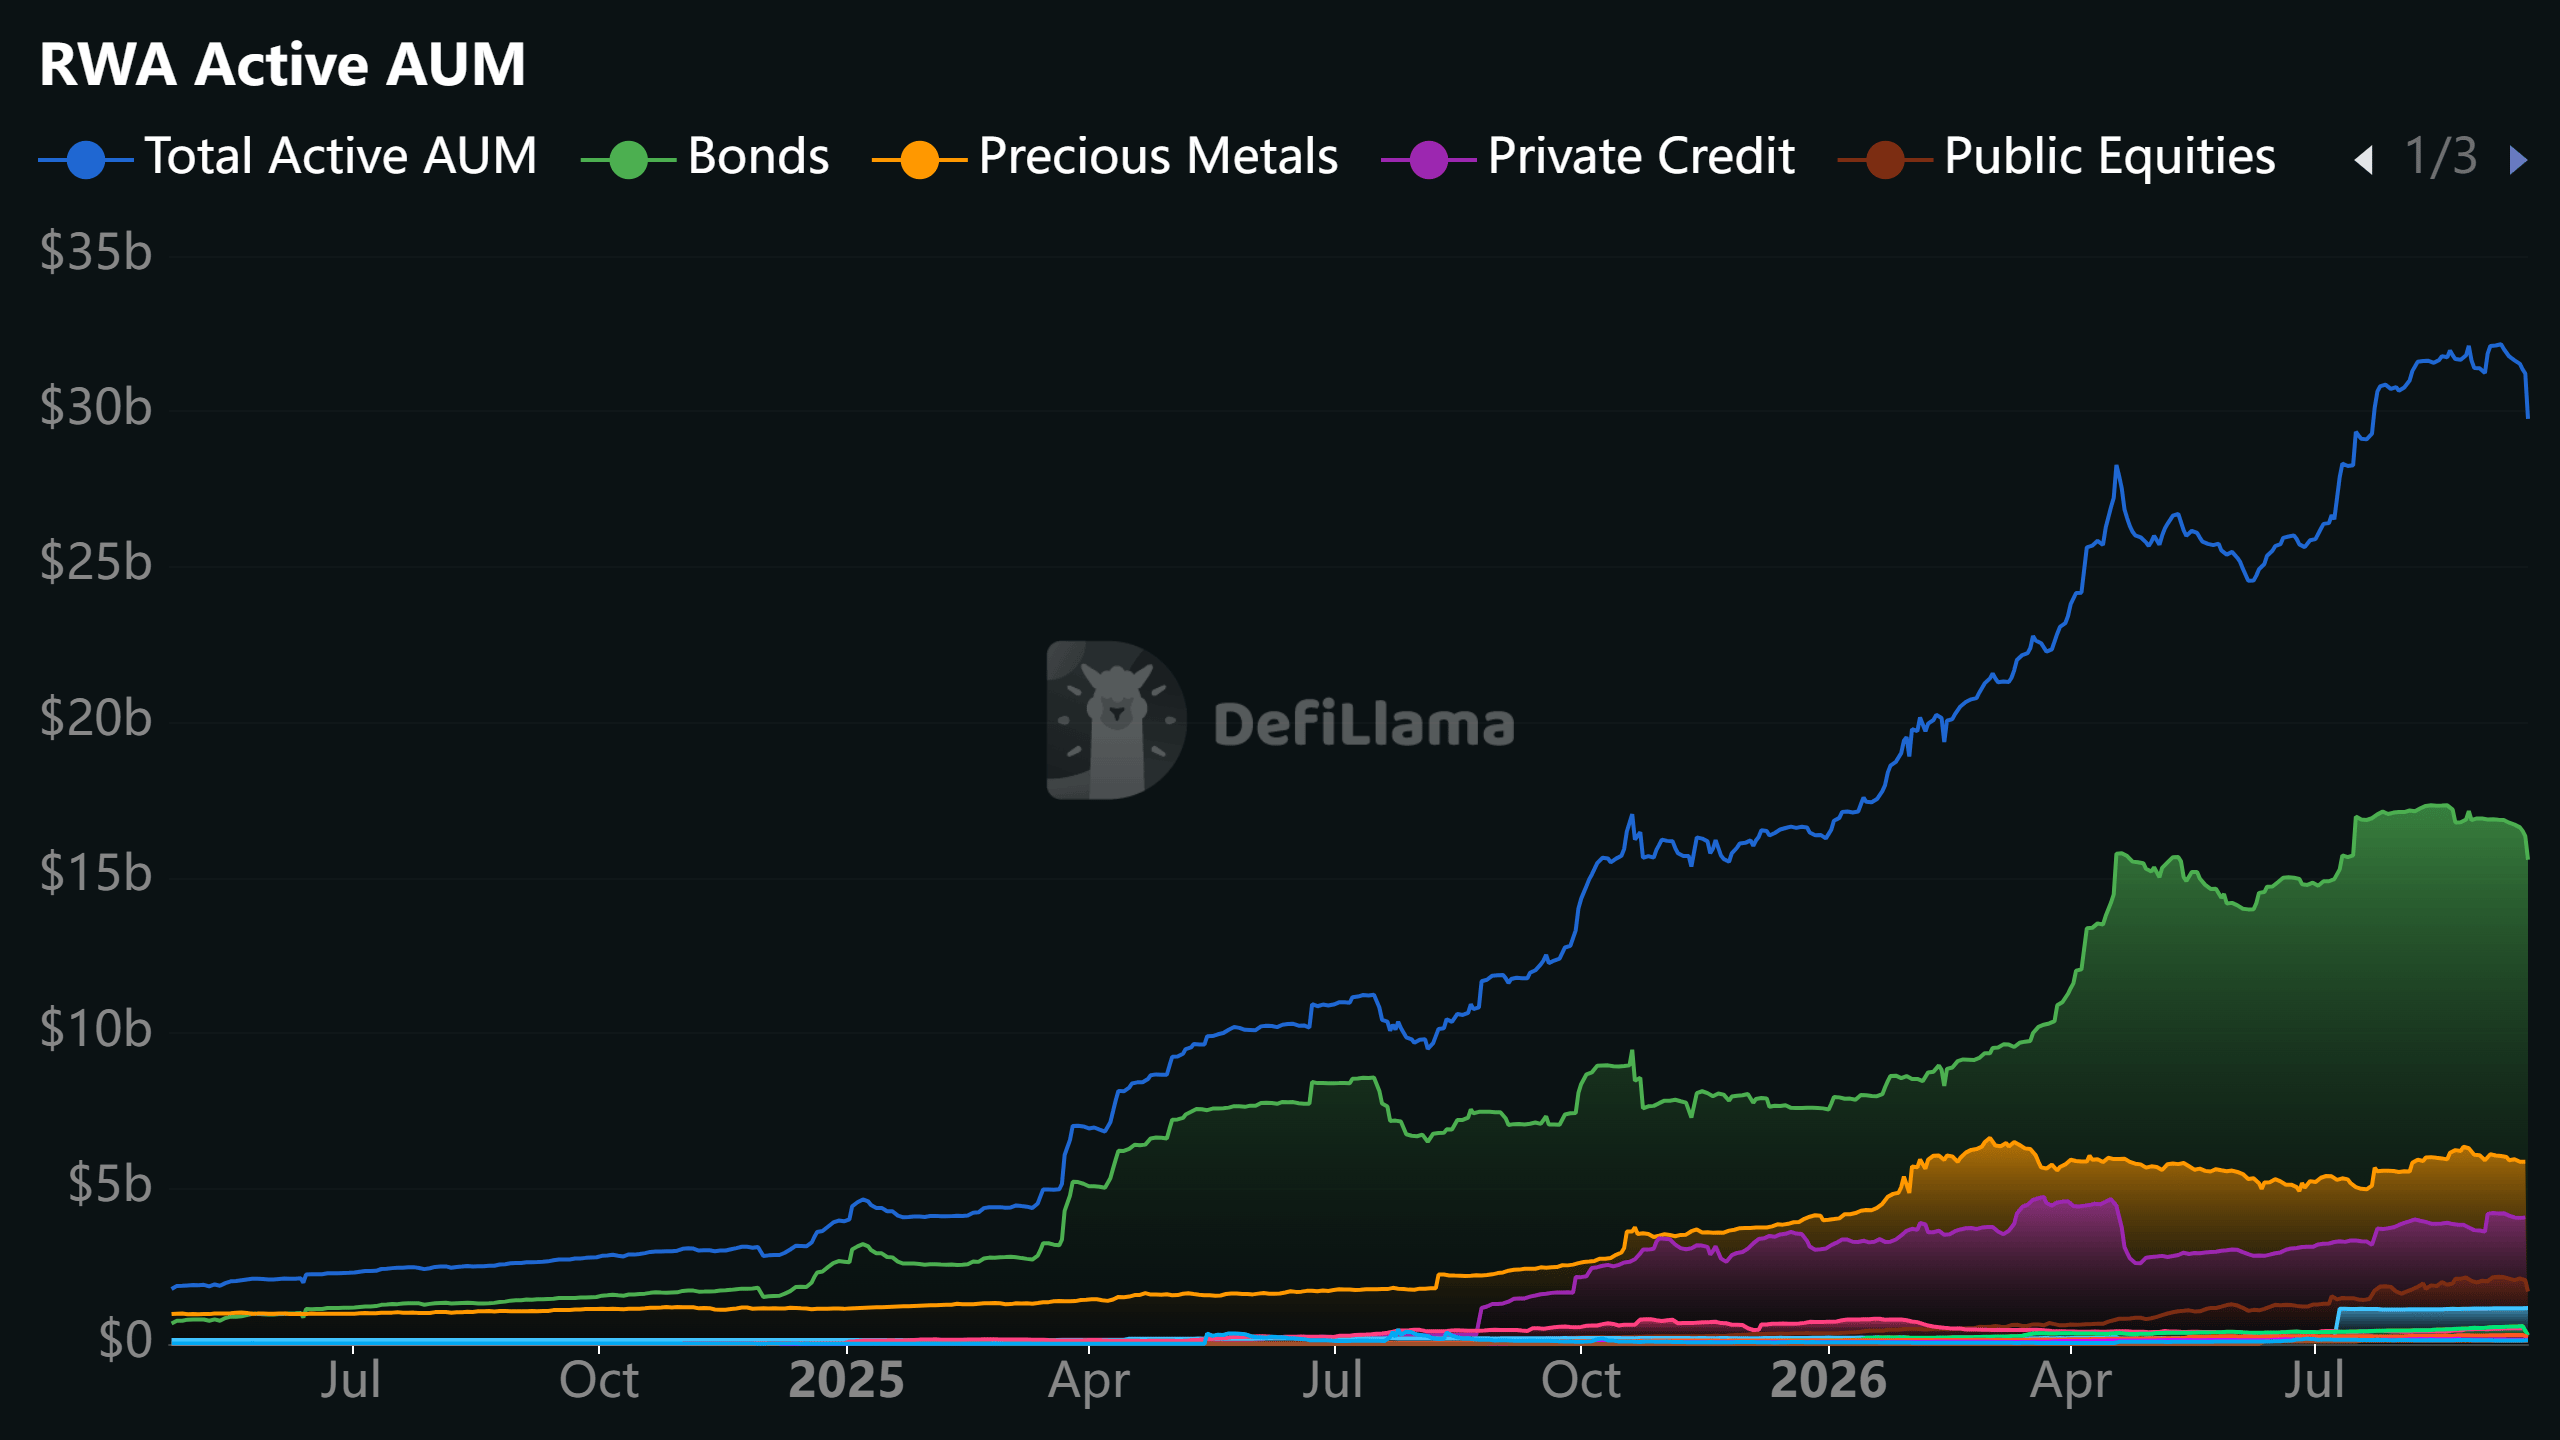
Since January 2025, total on-chain asset under management (AUM) of RWAs has surged nearly 8x to $34.092 billion. Bonds make up over half of that figure, followed by precious metals, private credit and public equities.
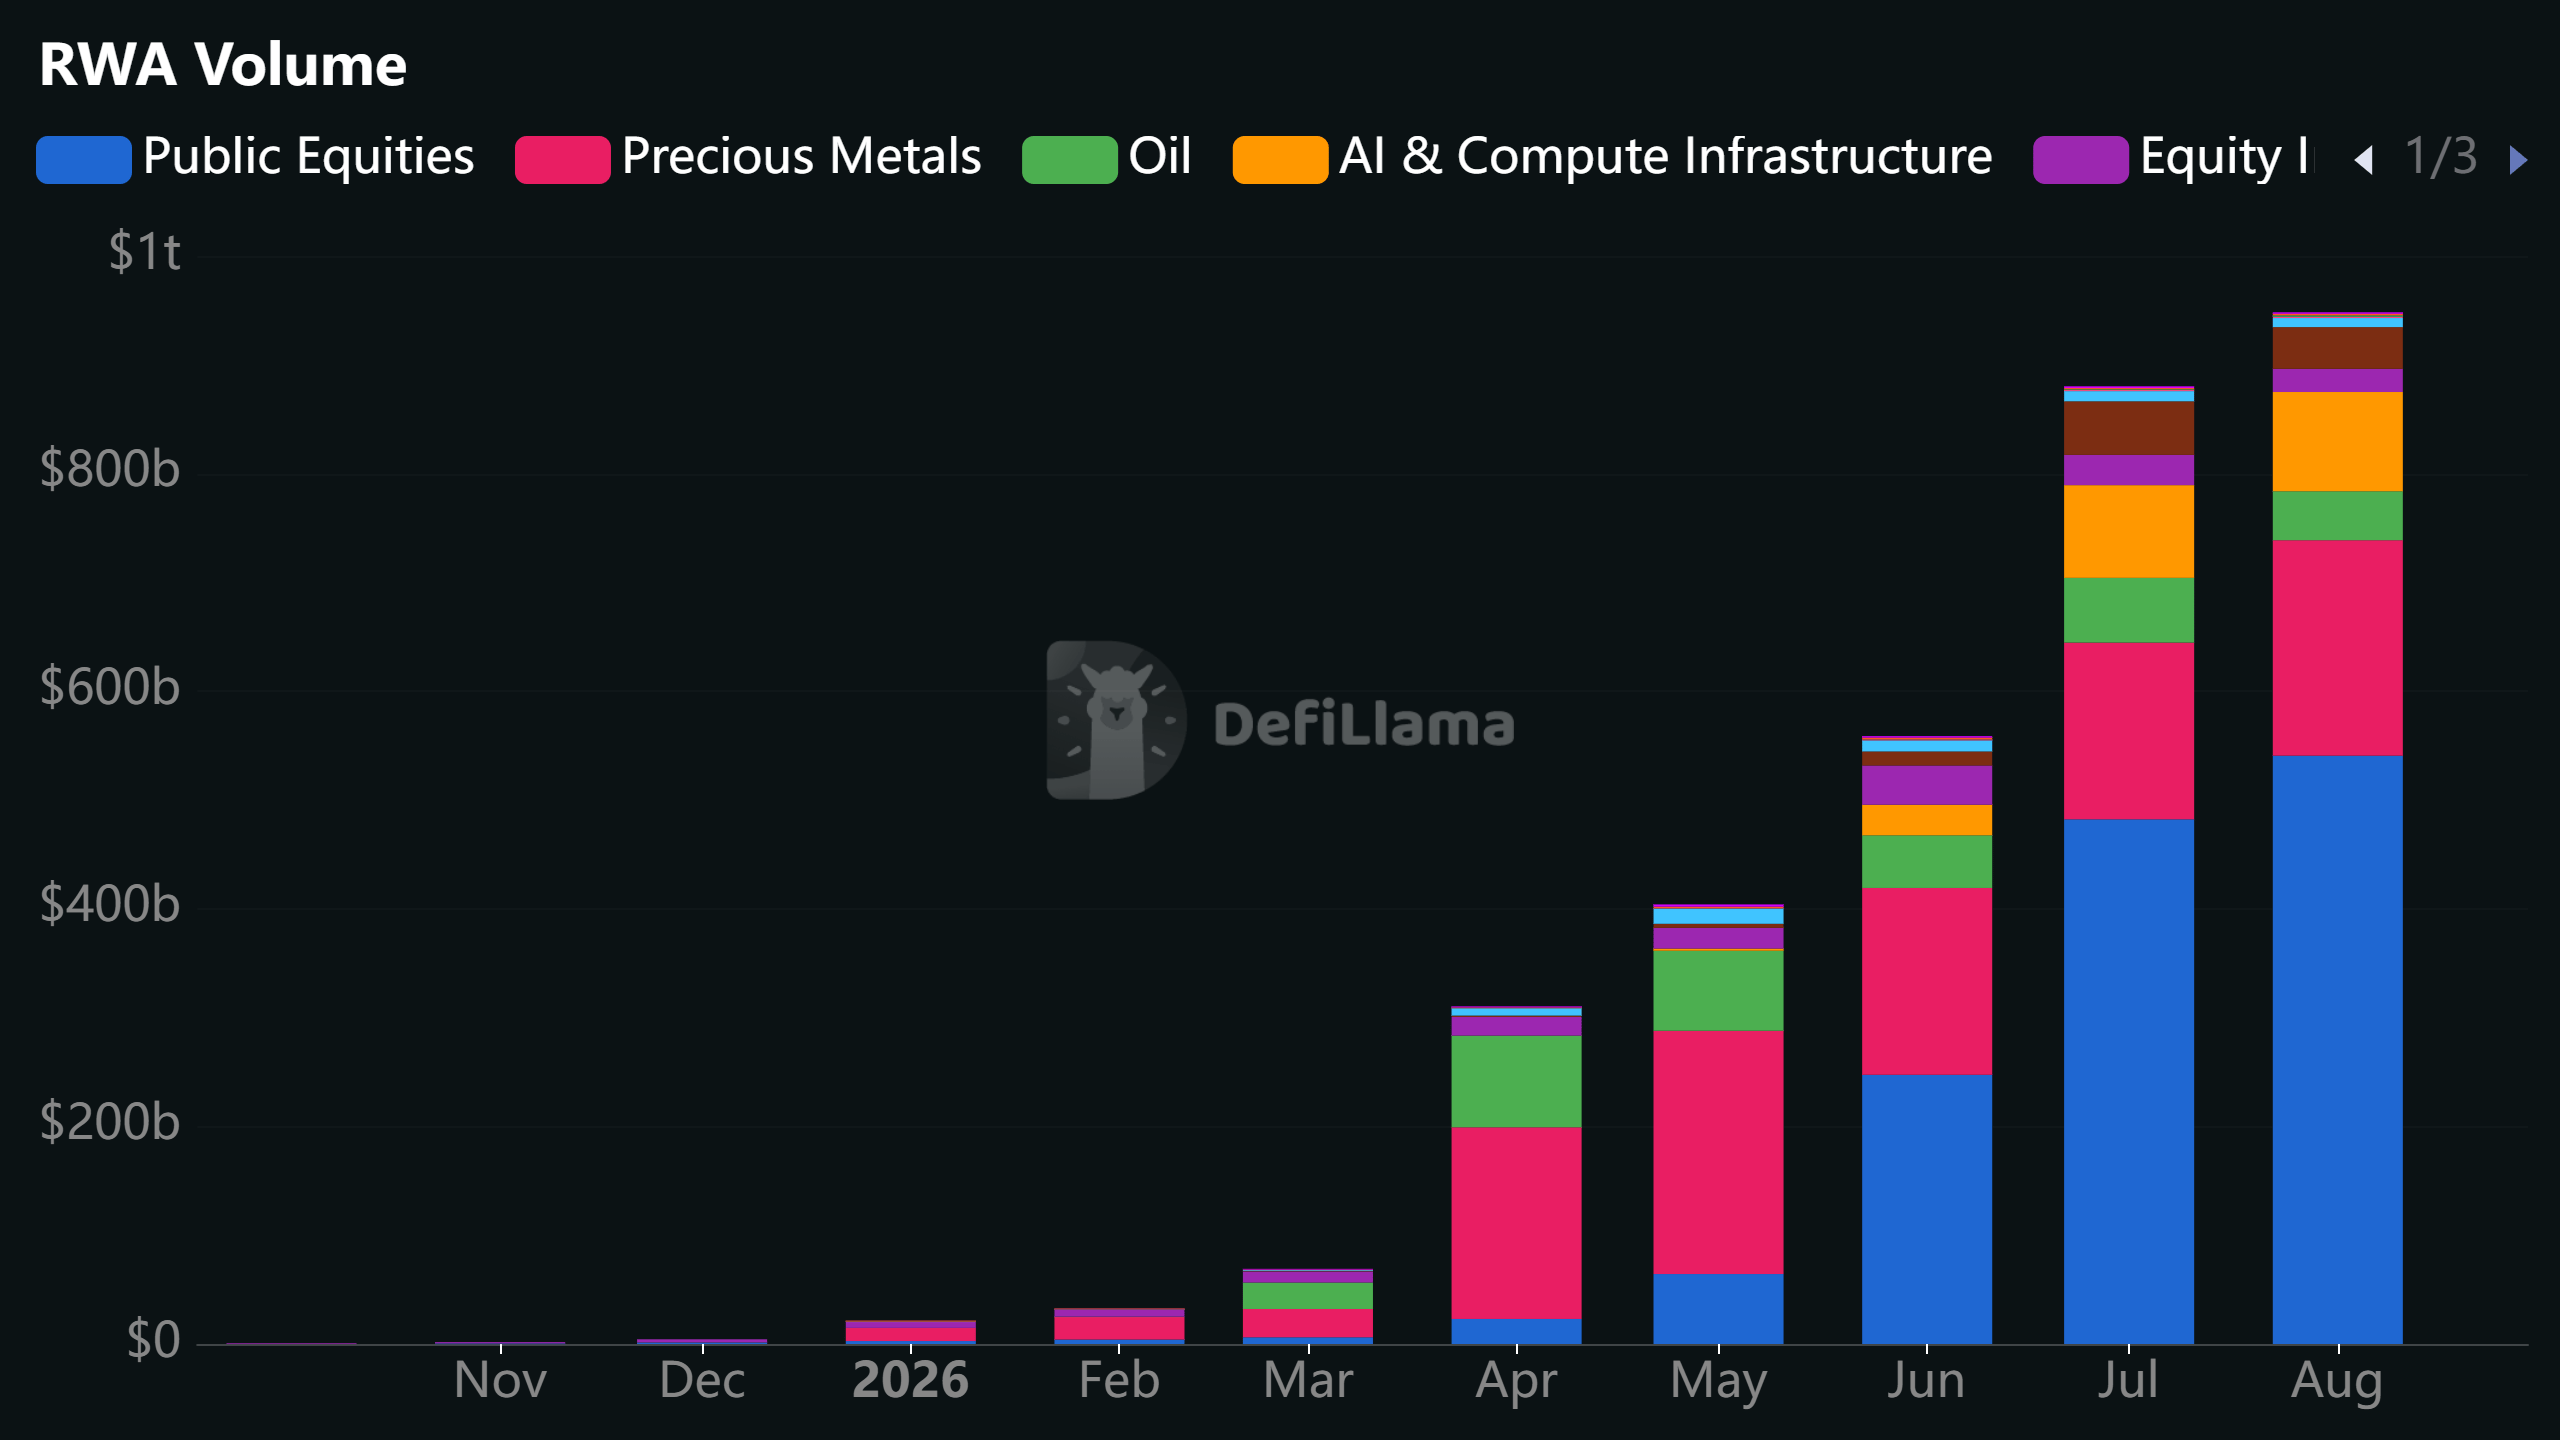
On the perpetual side, open interest of RWAs climbed from below $100 million to $15.903 billion during the same period. Public equities make up nearly 50% of the OI, followed by precious metals, Oil, and equity indices. Trading volume for these RWA perpetual products totaled $948.234 billion in August, up from less than $1 billion a year ago.
The growth comes despite almost the entire tokenized market being closed to US retail investors.
With such explosive growth, altcoins should have seen a mega rally if RWAs were truly meant to be a structural driver for an altcoin season. Ironically, the opposite is true.
As RWAs expanded, altcoins declined, with their total market cap falling from $1.49 trillion in October 2025 to a low of $540 billion in June before a slight recovery above $800 billion in August.
What prevented altcoins from capturing value from the RWA boom?
Let's re-examine altcoin trading behavior to see what changed.
In previous cycles, after Bitcoin saw an extended uptrend, investors took profits and reallocated capital to altcoins to chase high-beta returns. But not this time around.
Instead of reallocating capital to altcoins, investors switched toward tokenized and perpetual RWAs. Global market conditions at the time proved perfect for this setup.
The largest crypto liquidation in history on October 10, 2025, worth around $30-40 billion, sent panic across the crypto market and ignited a bear season. No one would think of chasing high-beta plays after experiencing that heavy liquidation shock. This is unlike previous cycles where capital slowly rotated out of Bitcoin. Instead, much of the market moved to the sidelines.
With crypto investors in overly cautious mode concerning Bitcoin and altcoins, Hyperliquid launched its HIP-3 platform, enabling the permissionless creation of perpetual markets.
At the time, Gold was roaring to new highs, prompting investors who wanted to stay in crypto to turn toward tokenized Gold and perpetual Gold contracts that offer leverage.
In February, following the escalation of the US-Iran crisis, crypto investors flocked toward perpetual Oil contracts on onchain platforms HIP-3, Lighter and Aster.
In April, US equities began to rally, with the S&P 500 soaring to new highs, while the crypto market remained subdued. As a result, crypto investors continued to ignore altcoins, flipping exposure to equities and pre-IPO markets. They carried out these moves without leaving the crypto market.
Hyperliquid became the major beneficiary, generating over $429 million in protocol revenue since January as it largely facilitates most RWA trading activity. For comparison, that's larger than the average market cap of an altcoin outside the top 100.
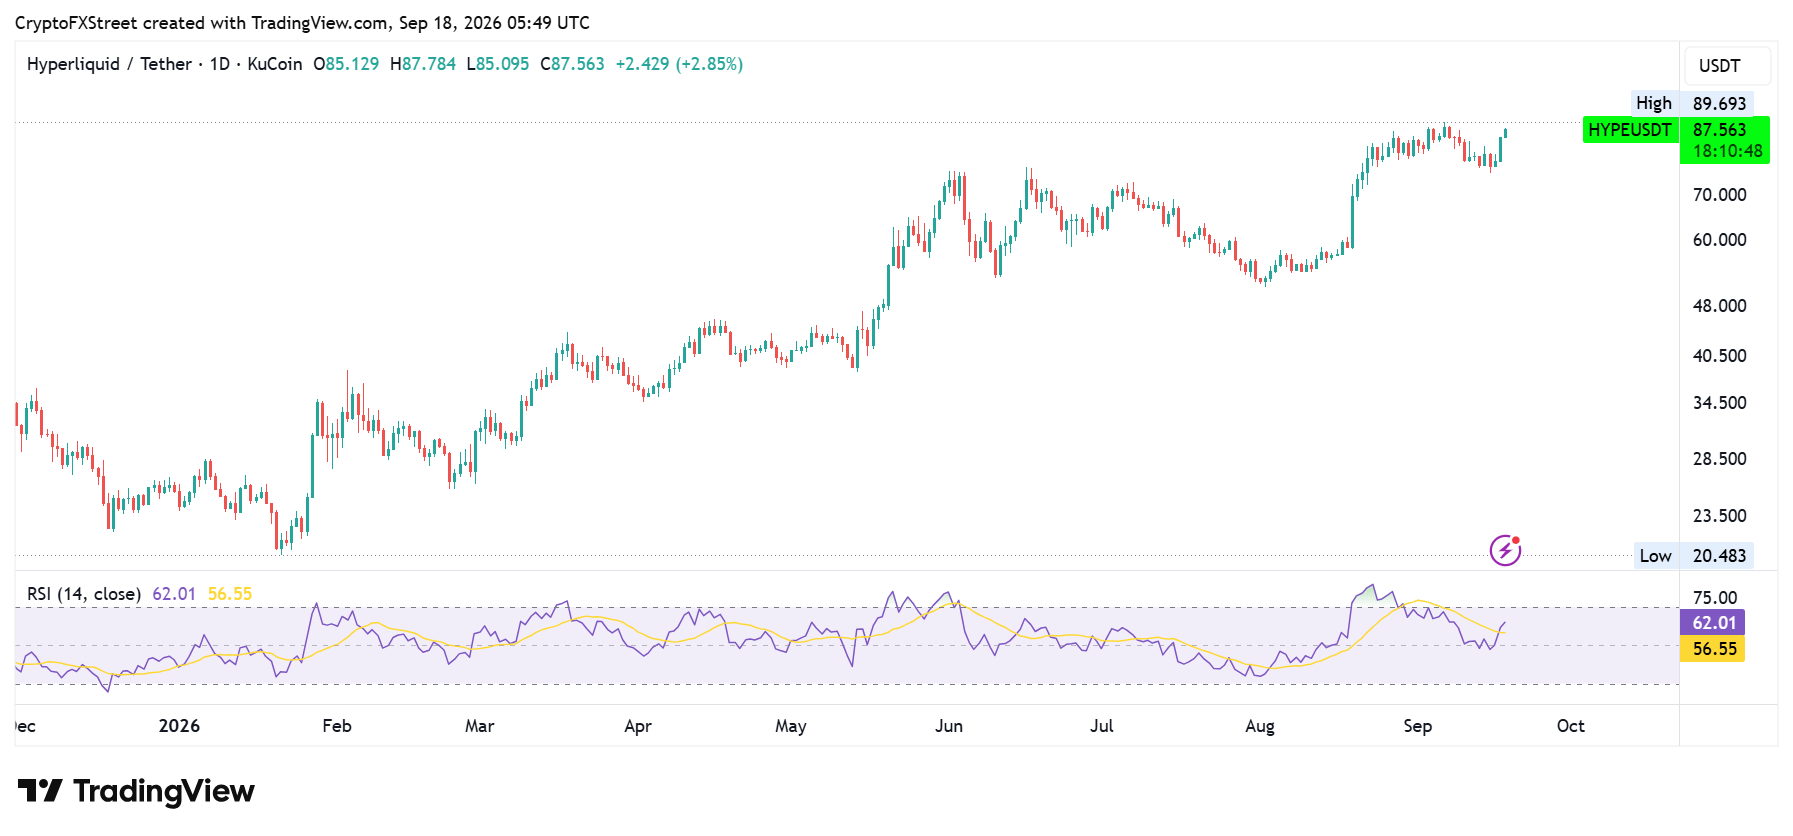
Its HYPE token has surged more than 4x since January to an all-time high of $89.6, giving it a market cap of $17.9 billion.
With Hyperliquid's revenue rising and cryptocurrency trading volume plunging, centralized crypto exchanges joined the RWA action, with Binance, OKX, Gate, MEXC and others launching tokenized and perpetual RWA markets.
CEXs now dominate these markets in both Open Interest (OI) and volume by 64% and 87%, respectively.
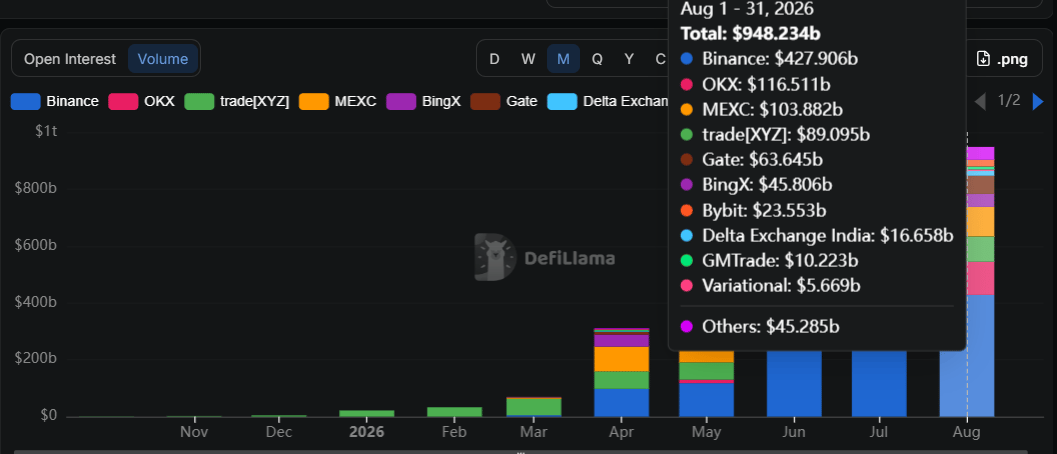
It is now clear that the RWA trend pushed by major crypto leaders isn't primarily driven by growth expectations for altcoins, but by a desire to capture more revenue from trading volume.
No doubt, the crypto market expanded with the launch of tokenized and perpetual RWAs, but it came at the expense of altcoins. Bringing traditional markets into crypto hasn't attracted an influx of massive capital toward altcoins that many predicted.
Instead, it sucked mindshare away and shifted crypto investors toward TradFi, creating new liquidity entry points for the already established bonds, equity and commodities markets.
But RWAs aren’t the only show stealer.
Prediction markets and PvP memecoins grabbed their share too
High-beta also implies higher risk, and many altcoin investors have a huge appetite for it. Rather than focus on altcoins, which largely underperformed, these investors saw prediction markets and memecoins as an opportunity to chase higher returns.
I mean, these investors often deploy capital in altcoins almost with the same framework as gambling. They place several bets across tens of altcoins with several promised use cases, knowing fully well these promises have little chance of survival. But they invest regardless, anticipating that one out of 20 bets will yield a "cryptonomic" return (7x, 8x and the like) that can cover the other losses and potentially turn them into millionaires.
With prediction markets and token launchpads gaining mainstream attention, along with their onchain processes, they have become the perfect venue for these altcoin investors to apply their investing framework.
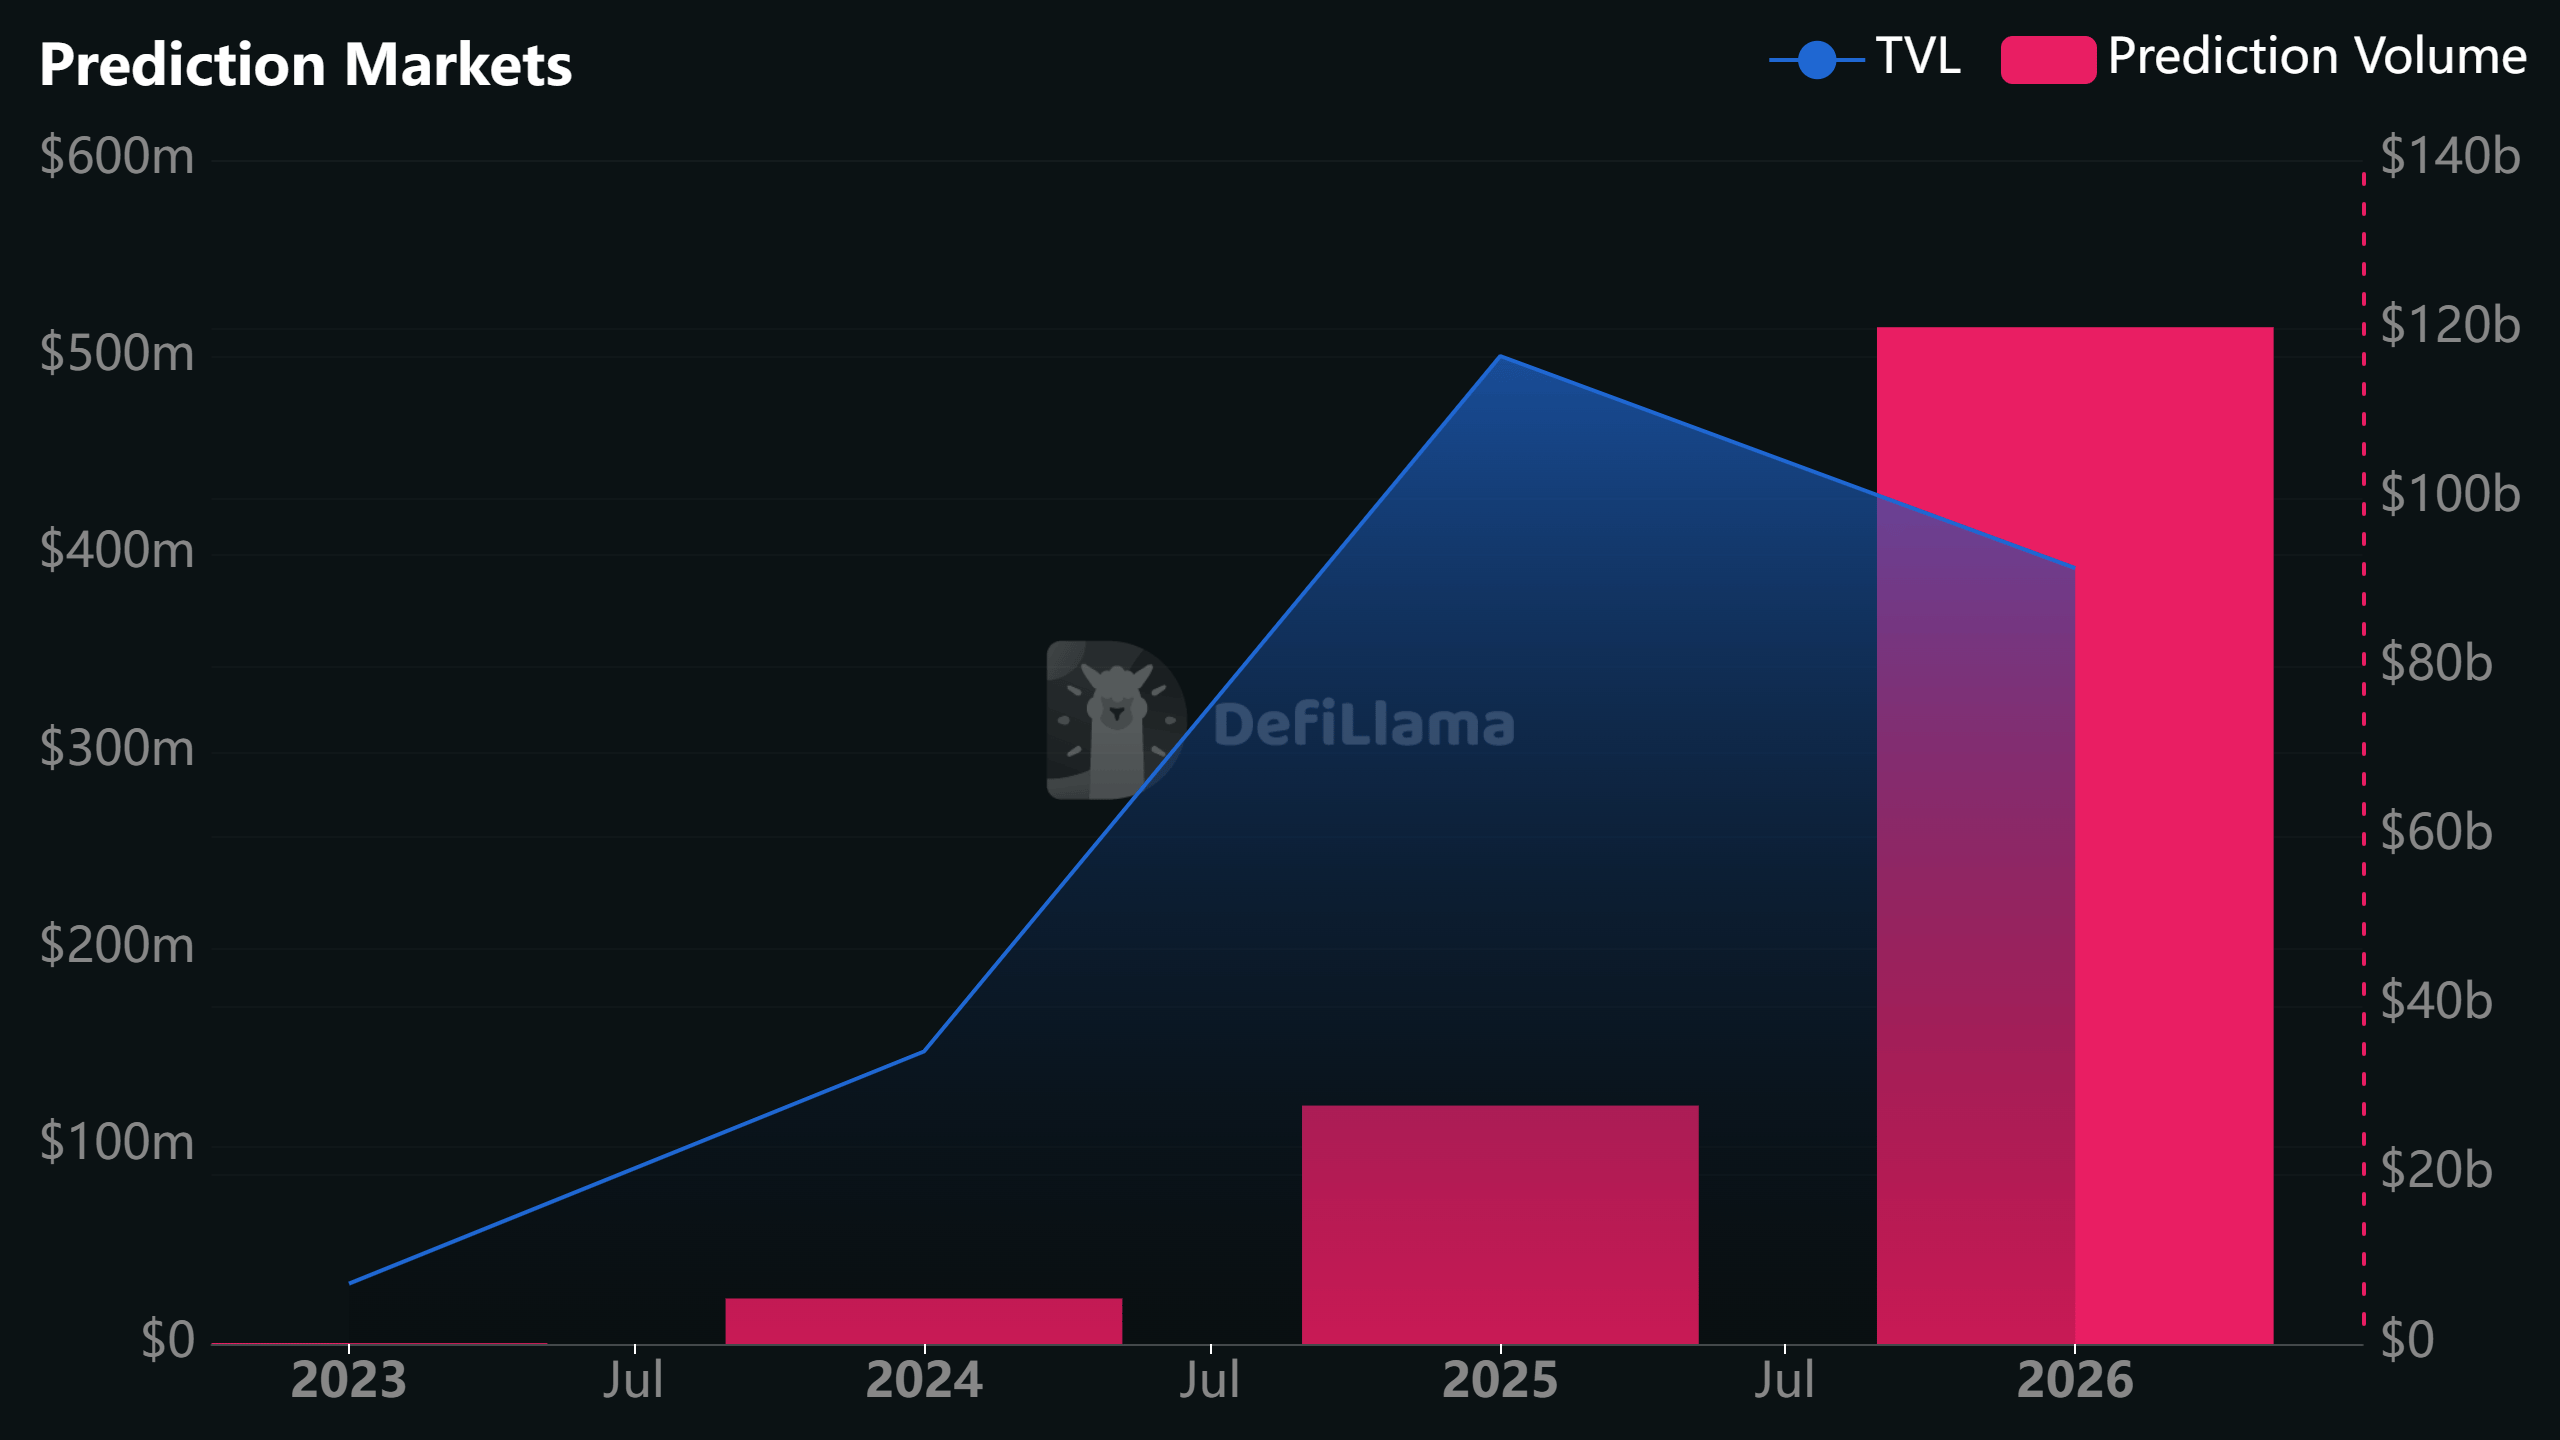
Since the beginning of the year, prediction markets have racked up $120.23 billion in trading volume, dominated by Kalshi and Polymarket, per DefiLlama data. Their ratio to spot crypto trading volume peaked at nearly 8% in July before easing to 6.21%.
Similarly, memecoin token launchpads across Solana, Base, BNB Smartchain and more recently Robinhood Chain also stole the spotlight from altcoins.
These platforms, spearheaded by Pump.fun, sparked a player-versus-player (PvP) memecoin culture where traders compete to secure profits at the expense of late buyers.
As of October 2025, Pump.fun accounted for 12.9 million of the 32 million tokens on Solana, according to a Galaxy Digital report. At the time, their median hold time was 100 seconds. Trading volume on these token launchpads peaked at $19.57 billion over a year ago, according to DefiLlama data.
Compared to the previous cycle, when the total number of cryptocurrencies was less than 30,000, token saturation through these launchpads fragmented liquidity across millions of tokens, hurting altcoins' chances of attracting meaningful capital.
Conclusion
In the long term, tokens of major L1s and applications that host tokenized and perpetual RWAs could benefit as tokenization and TradFi perps expand, but this growth may continue at the expense of altcoins.
I fear there may be no crypto market like we used to know. The crypto landscape could evolve into Bitcoin, Ethereum, tokenized and perpetual RWAs, the tokens of these L1s and the applications that support them, and prediction markets…until traditional altcoins find another structural driver to spur an altcoin season.
추천 기사


