


Half of the record Japanese Yen intervention is already gone
- USD/JPY trades at 159.50, the exact midpoint of the intervention move.
- Roughly 13.75 trillion Yen of official buying, half of it already retraced.
- Japanese policy rate 1.00% against inflation that last printed at 1.7%.
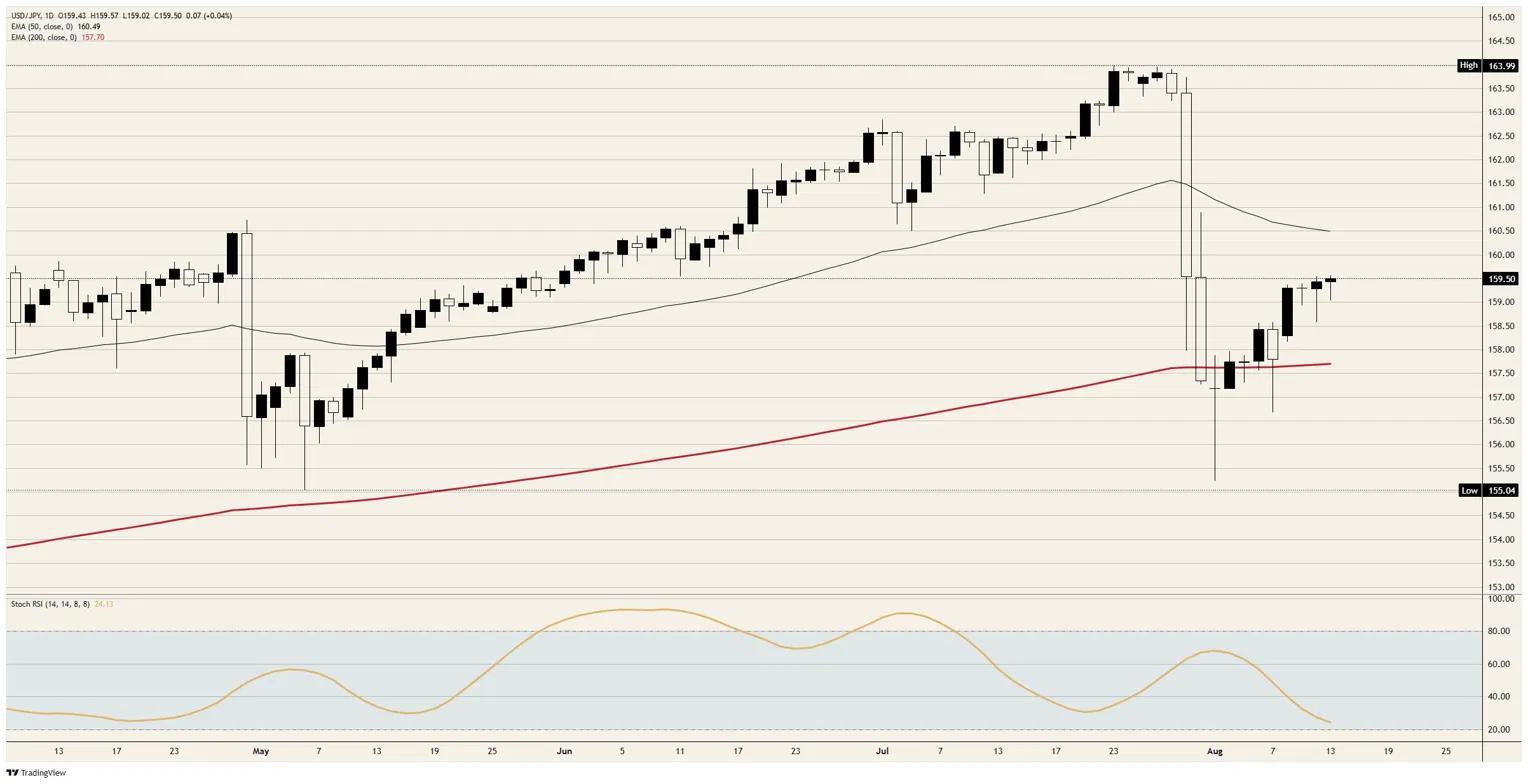
The Dollar changes hands at 159.50 against the Yen on Thursday, a fraction higher on the session inside a range of barely 55 pips. The level matters more than the move, because 159.50 sits almost exactly halfway between the pre-intervention peak just short of 164.00 and the low just above 155.00 that Tokyo and Washington bought together at the start of the month.
Seven sessions on from the largest Yen-buying operation ever mounted, half of it has been handed back. No fresh operation has been announced and none has been required, because the market has unwound the move without anyone standing in its way.
The most expensive floor in history is half gone
Estimates put the opening solo operation near 8.45 trillion Yen in a single session, the largest on record, with roughly 5.3 trillion more the following day alongside the US Treasury. That second leg was the first joint Yen-buying operation with Washington since 1998, and both capitals said afterwards that they would not hesitate to repeat it.
The combined effect was a drop from just short of 164.00 to just above 155.00, close to nine Yen inside two sessions. The pair now trades at 159.50, which puts four and a half of those nine Yen back into the hands of the people the operation was aimed at. Official buying purchased a level, not a trend.
The tally itself will not be public for another two weeks. Japan's Ministry of Finance publishes intervention totals monthly with a cut-off near the 28th, so the bill for the operation arrives at the end of August. Traders will read that number with the exchange rate nearer to where the buying started than to where it stopped.
One detail from the announcement deserved more attention than it received. Tokyo signalled it would fund future operations through the Federal Reserve's repo facility for foreign monetary authorities rather than by selling Treasuries, which removes the constraint that historically capped how much it could spend. Money was never the limit here, which is what makes a half-retraced operation such an awkward result.
A Dollar-negative session the Yen still lost
The July Producer Price Index (PPI) landed flat MoM against 0.2% expected, with the YoY rate down to 4.7% from 5.5% and the core measure up 0.2% against 0.3%. Initial jobless claims came in at 209K against 202K expected and 200K previously. Every one of those readings argues for a weaker Dollar.
Rate futures now put a September 16 hold at 65.2%, leaving a hike tail of 34.8% at a meeting that was a coin flip on August 10. December 9 gives the current range a 34.1% chance of surviving the year, and the cut column is empty at every 2026 meeting. The Dollar was handed a softer rate path on the day and the Yen still lost ground to it.
The carry trade does not need the Federal Reserve to hike. It needs Japan's real policy rate to stay negative, and with policy at 1.00% against inflation that last printed at 1.7%, it is comfortably there. A quarter point in Washington changes the size of that gap and nothing whatever about its direction.
Energy is doing the rest of the work against this currency. Talks on reopening the Strait of Hormuz are deadlocked, transits ran eight vessels on Tuesday against roughly 130 before the war, and Japan imports almost all of the crude it burns. An energy shock is a terms-of-trade tax on a net importer, which is the one bearish argument for the Yen that no amount of official buying can touch.
What lands next
Friday brings US retail sales for July at 12:30 GMT, with the headline expected at 0.1% against 0.2% previously, followed at 14:00 GMT by the preliminary University of Michigan sentiment index at 54.5 against 55.2. The inflation expectations components matter more than the headline given where September pricing now sits.
Japan's own calendar carries the heavier weight. Preliminary second-quarter Gross Domestic Product (GDP) lands late on Sunday August 16 at 23:50 GMT, with quarterly growth expected at 0.5% and the annualised rate at 2% against 1.8% previously. July trade figures follow on August 19 and national inflation on August 20, where the headline last printed at 1.7% and the measure excluding fresh food at 1.6%.
Those inflation figures decide whether the Bank of Japan has cover to follow June's move to 1.00% with another one. A print anywhere near 1.7% leaves the real rate deeply negative and leaves the Ministry of Finance defending a level that its own central bank is not helping it defend. The Federal Open Market Committee (FOMC) minutes on August 19 sit in the same window.
Levels
Resistance: The 50-day Exponential Moving Average (EMA) just short of 160.50 is the first ceiling and it is declining into price, with the 160.00 handle the marker beneath it. Above there, the pre-intervention peak just short of 164.00 is the only structure left on the chart.
Support: The 159.00 area held on the session, with 158.00 and the rising 200-day EMA just beneath it as the next shelf. Under that sits the intervention low just above 155.00, the floor the operation paid for.
Bias: Bullish while 158.00 holds, with 160.50 the objective and a daily close above it re-opening the 162.00 area. Invalidation on a daily close beneath 158.00, which would put the recovery back into official hands. Daily momentum argues for patience rather than chasing, with the Stochastic Relative Strength Index (Stoch RSI) near 24 and falling while price grinds higher.
USD/JPY daily chart
Japanese Yen FAQs
The Japanese Yen (JPY) is one of the world’s most traded currencies. Its value is broadly determined by the performance of the Japanese economy, but more specifically by the Bank of Japan’s policy, the differential between Japanese and US bond yields, or risk sentiment among traders, among other factors.
One of the Bank of Japan’s mandates is currency control, so its moves are key for the Yen. The BoJ has directly intervened in currency markets sometimes, generally to lower the value of the Yen, although it refrains from doing it often due to political concerns of its main trading partners. The BoJ ultra-loose monetary policy between 2013 and 2024 caused the Yen to depreciate against its main currency peers due to an increasing policy divergence between the Bank of Japan and other main central banks. More recently, the gradually unwinding of this ultra-loose policy has given some support to the Yen.
Over the last decade, the BoJ’s stance of sticking to ultra-loose monetary policy has led to a widening policy divergence with other central banks, particularly with the US Federal Reserve. This supported a widening of the differential between the 10-year US and Japanese bonds, which favored the US Dollar against the Japanese Yen. The BoJ decision in 2024 to gradually abandon the ultra-loose policy, coupled with interest-rate cuts in other major central banks, is narrowing this differential.
The Japanese Yen is often seen as a safe-haven investment. This means that in times of market stress, investors are more likely to put their money in the Japanese currency due to its supposed reliability and stability. Turbulent times are likely to strengthen the Yen’s value against other currencies seen as more risky to invest in.
추천 기사


