


CME vs. Toast: Which Financial Stock Is a Better Buy for 2027?
Key Points
CME Group maintains a dominant position in global derivatives with exceptionally high net margin levels.
Toast is rapidly expanding its restaurant technology ecosystem and has recently achieved consistent profitability.
Which of these financial infrastructure providers is the better choice for your long-term portfolio?
- 10 stocks we like better than CME Group ›
Investors often weigh the stability of established financial giants against the high-growth potential of modern software platforms. Choosing between CME Group (NASDAQ:CME) and Toast (NYSE:TOST) requires balancing the two paths.
CME Group operates a global exchange for futures and options, serving as a critical piece of market infrastructure. Toast provides the digital backbone for restaurants, handling everything from payments to point-of-sale hardware. Both companies play essential roles in the financial stocks landscape but face distinct growth drivers as we look toward 2027.
The case for CME
CME Group operates the world's most diverse derivatives marketplace, offering trading for asset classes ranging from equities to energy and agriculture. The company generates revenue by charging fees for every contract traded and cleared on its platforms, serving professional traders, institutional investors, and central banks. In its latest annual report, filed for the fiscal year 2025, the company noted that 85% of its derivatives contract volume came from exchange members.
In fiscal 2025, revenue reached nearly $6.5 billion, representing a growth rate of approximately 6.4% over the prior year. This revenue supported net income of close to $4 billion, resulting in a robust net margin of roughly 62%. The company has consistently demonstrated the ability to convert trading volume into high levels of profit as global market volatility drives demand for its hedging tools.
As of CME's December 2025 balance sheet, the company carries a debt-to-equity ratio of approximately 0.1. This ratio measures total debt relative to shareholders' equity, indicating a conservative approach to borrowing. The current ratio, which compares short-term assets to short-term liabilities, is roughly 1. For the same period, free cash flow totaled nearly $4.2 billion. FCF represents the cash remaining after the business pays for its operating activities and capital expenditures.
The case for Toast
Toast provides an integrated cloud-based platform specifically designed for the restaurant industry, covering point-of-sale software and hardware. The company primarily serves small and medium-sized businesses but is actively expanding into larger enterprise and mid-market restaurant segments. By the end of 2025, the company served over 170,000 locations across five countries, consolidating payments and operations into a single interface.
In fiscal 2025, revenue reached approximately $6.2 billion, reflecting a rapid growth rate of roughly 24.1% over the previous year. The company delivered net income of close to $342 million, achieving a net margin of nearly 5.6%. This performance marks a significant milestone, as the business transitioned from reporting annual losses to achieving sustainable profitability while continuing to gain market share.
As of Toast's December 2025 balance sheet, the debt-to-equity ratio is approximately 0, indicating the company has negligible total debt relative to its equity. The current ratio stands at roughly 2.8, suggesting a strong ability to cover short-term obligations with liquid assets. Free cash flow for the period was nearly $608 million. Note that stock-based compensation accounted for roughly 36.6% of operating cash flow, inflating reported cash generation, since SBC is a non-cash expense added back in the cash flow statement.
Risk profile comparison
CME Group faces significant regulatory risk, particularly concerning potential new laws governing digital assets and clearinghouse ownership structures. Competitive pressures are high from rival exchanges such as Intercontinental Exchange (NYSE:ICE) and Cboe Global Markets (NYSEMKT:CBOE), along with emerging crypto platforms. The company also relies on licensing agreements with third-party providers like S&P Global (NYSE:SPGI), which could present risks if terms become unfavorable or exclusive access is lost.
Toast is subject to an ongoing FTC lawsuit regarding the application of consumer protection acts to its business-to-business contracts. The company relies heavily on Amazon (NASDAQ:AMZN) for its cloud infrastructure and third-party partners for payment processing and lending. Furthermore, the restaurant industry is highly susceptible to macroeconomic downturns, which could directly impact Toast's transaction volumes if consumer spending on dining falls.
Valuation comparison
While Toast offers a significantly lower sales multiple, CME Group trades at a similar forward earnings premium despite its vastly superior net margin profile.
| Metric | CME Group | Toast |
|---|---|---|
| Forward P/E | 24.9 | 24.5 |
| P/S ratio | 15.9 | 2.5 |
Valuation metrics include sourcing from Financial Modeling Prep (FMP) and may differ from other data providers.
The forward P/E uses future earnings estimates to determine whether a stock is priced fairly relative to its expected profits. The P/S ratio measures the market value of a company against its sales over the past 12 months.
Which stock would I buy for 2027?
CME Group and Toast are at very different stages in their respective business life cycles. CME Group is a mature, established organization, with a staggering net margin that would be the envy of most companies. It has undergone several iterations, but the original business is well over 100 years old.
Meanwhile, Toast was founded just 14 years ago and only went public in 2021. So this is somewhat of an apples-to-oranges comparison.
Turning to the tape:
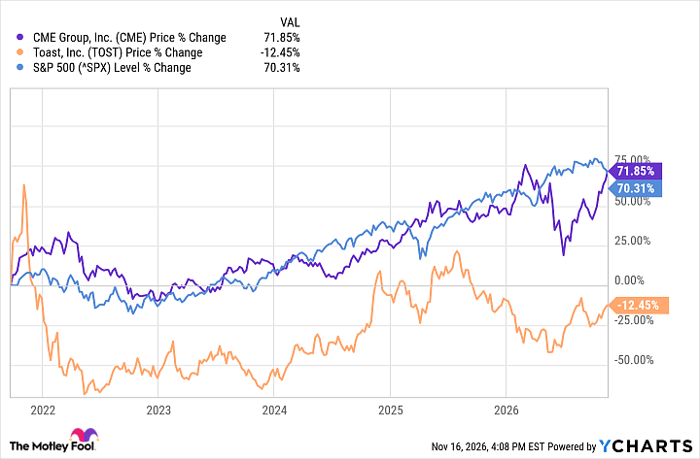
CME data by YCharts
Since going public, Toast has been a disappointing investment. But in that same time frame, CME Group stock has barely outperformed the S&P 500 (SNPINDEX:^GSPC). CME does at least pay a modest dividend yielding about 1.6%. Toast has posted much stronger revenue growth recently, but I would expect that from an up-and-coming company.
I think the choice here comes down to your comfort with risk. A young company like Toast is likely to have more growth opportunities ahead than a mature business like CME Group. But Toast is also less proven and faces significant competition from Square. I lean on the conservative side here: CME Group gets my vote for 2027 and beyond.
Should you buy stock in CME Group right now?
Before you buy stock in CME Group, consider this:
The Motley Fool Stock Advisor analyst team just identified what they believe are the 10 best stocks for investors to buy now… and CME Group wasn’t one of them. The 10 stocks that made the cut could produce monster returns in the coming years.
Consider when Netflix made this list on December 17, 2004... if you invested $1,000 at the time of our recommendation, you’d have $335,171!* Or when Nvidia made this list on April 15, 2005... if you invested $1,000 at the time of our recommendation, you’d have $1,000,640!*
Now, it’s worth noting Stock Advisor’s total average return is 823% — a market-crushing outperformance compared to 208% for the S&P 500. Don't miss the latest top 10 list, available with Stock Advisor, and join an investing community built by individual investors for individual investors.
See the 10 stocks »
*Stock Advisor returns as of November 17, 2026.
Erin Kennedy has positions in CME Group. The Motley Fool has positions in and recommends Amazon, CME Group, and Toast. The Motley Fool recommends Cboe Global Markets and Intercontinental Exchange and recommends the following options: long January 2028 $15 calls on Toast. The Motley Fool has a disclosure policy.
Recommended Articles


