


Anthropic is six times oversubscribed at $1.4 trillion while Nvidia is down 32% — the AI trade has two prices
On Thursday, Anthropic lists on Nasdaq under the ticker ANT: 825 million shares at $70 ~ $78, raising up to $64.4 billion at a target valuation near $1.4 trillion, with the book reportedly six times covered and up to 20% of the deal earmarked for retail. In the same six weeks, Nvidia's market value has fallen from $5.8 trillion in early October to $3.92 trillion, and the QQQ closed Friday at 679.89, 10.9% below its 6 October peak. Private capital and public markets are pricing the same AI complex at two very different numbers.
| Deal term | Detail |
|---|---|
| Ticker / venue | ANT, Nasdaq |
| Shares on offer | 825 million |
| Price range | $70 ~ $78 |
| Gross proceeds | Up to $64.4 billion |
| Target valuation | About $1.4 trillion |
| Book coverage | About 6x oversubscribed |
| Retail allocation | Up to 20% |
| Private placement | $26 billion at the IPO price |
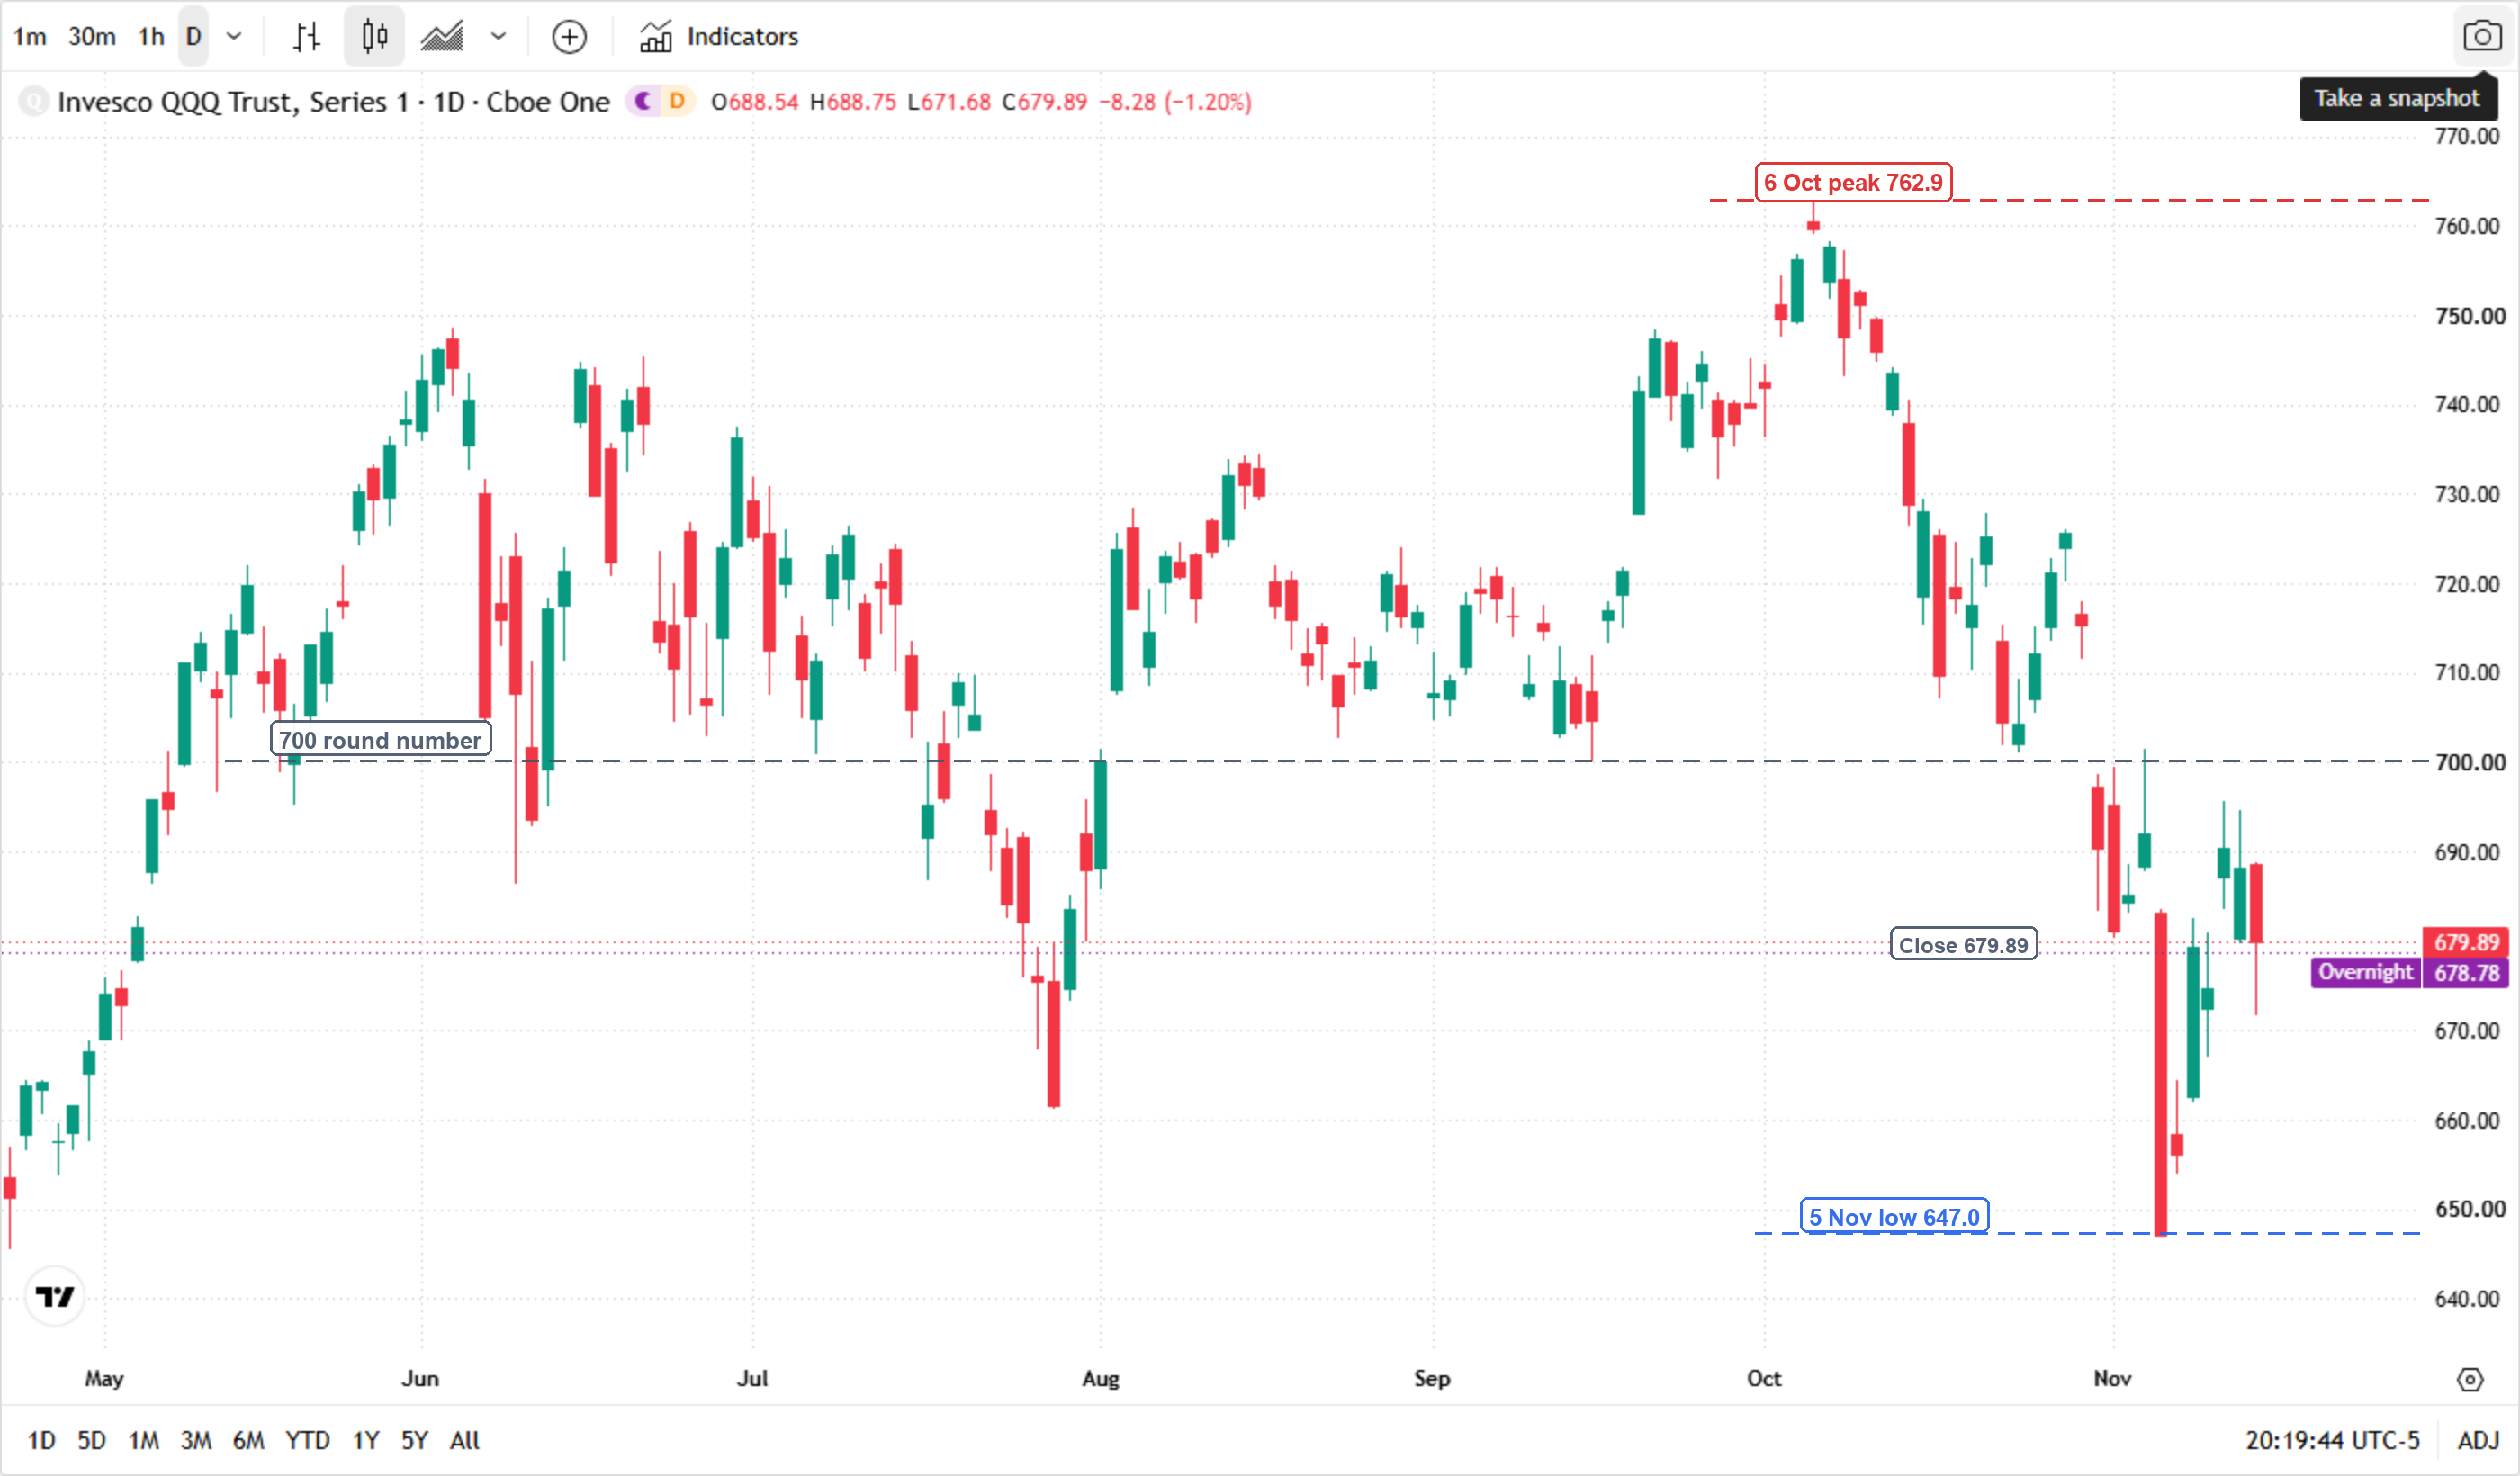
* Chart source: TradingView (QQQ daily, Cboe One feed)
Two prices for the same trade
The public tape has spent six weeks de-rating AI. The QQQ is down 10.9% from its 6 October peak, Nvidia is down 32% from its record, and the Philadelphia Semiconductor Index fell another 3.4% on Friday. The private tape is doing the opposite: Anthropic's book is covered six times, at a valuation that implies roughly 36 ~ 40 times trailing sales, or about 17 times its $81 billion October run-rate revenue.
Both numbers can be "right" at the same time, because they are set by different buyers. Public marks are set daily by anyone with a brokerage account. Private marks are set by strategic capital that also buys the product. The $26 billion private placement alongside the IPO has commitments from Google, Nvidia, AMD, Broadcom, Micron, Microsoft and TSMC at the IPO price. Those are the same companies that supply Anthropic's compute and, in several cases, buy its models.
The $26 billion anchor
That is the part of the deal that deserves the most attention. When your suppliers and customers are also your IPO anchor investors, the clearing price is not a pure market price — it is a strategic price. It tells you what the AI complex is willing to pay to keep the model layer inside its own ecosystem. It tells you less about what a public shareholder should pay on Thursday.
What the S-1 actually says
The operating numbers are extraordinary by any software standard. Q3 revenue was $16.96 billion, up 1,127% year on year, with $33.2 billion in the first nine months. 79% of revenue is usage-based, and more than half of the Fortune 500 pay at least $100,000 a year.
| Metric | Figure |
|---|---|
| Q3 revenue | $16.96 billion (+1,127% YoY) |
| First nine months revenue | $33.2 billion |
| Usage-based share of revenue | 79% |
| Trailing-sales multiple | About 36 ~ 40x |
| October run-rate revenue | $81 billion |
| Total spending commitments | About $900 billion |
| Commitments due by 2030 | $451.6 billion |
The balance sheet is where the argument starts. Total spending commitments are around $900 billion, of which $451.6 billion is due by 2030, mostly compute and infrastructure. That is an asset-liability mismatch: revenue is growing fast, but the obligations are long-dated and contracted while the revenue is not.
The bull case and the bear case
The bull case is that Anthropic is the fastest-scaling enterprise software company ever taken public, with usage-based pricing that expands with model capability, a customer base that already includes most of the Fortune 500, and a listing that could re-rate the whole AI complex the way a successful mega-cap IPO often does. The IPO's halo effect is real: a strong debut gives public investors a benchmark for AI revenue that does not depend on Nvidia's guidance.
The bear case is that the $1.4 trillion tag is being set at the exact moment the public market is cutting the same trade by a third, that the $900 billion commitment stack turns operating leverage into financing risk, and that the IPO is partly a liquidity event for strategic holders who cannot sell otherwise. At 36 ~ 40 times trailing sales, there is no room for a single quarter of deceleration.
Thursday's print is a sentiment gauge for the whole complex
The first trade on Thursday is not really about Anthropic. It is about whether public investors will pay a private-market price for AI while the public AI index is 11% off its high. Two branches:
If ANT opens above the $78 top of the range and holds, it gives the AI complex an external validation it has not had since October. The read-across is straightforward: Nvidia's Tuesday print lands into a friendlier tape, and the QQQ's 700 line comes back into play.
If ANT opens at or below issue and fades, the message is that the private mark was a strategic price, not a market price. In that case the public AI complex loses its last external bid, and the QQQ's 647 November low becomes the level to watch rather than 700.
Either way, the tell is the same: watch the first-day close, not the first print. A 20% retail allocation means the float will be noisy in the first hour.
Read more
* The content presented above, whether from a third party or not, is considered as general advice only. This article should not be construed as containing investment advice, investment recommendations, an offer of or solicitation for any transactions in financial instruments.


