


Nvidia reports tomorrow with an interim CEO — $108 billion is the easy number
Nvidia closed Friday at $162.85, down 2.01% on the day and 12.75% on the week — its sixth straight weekly loss, the longest streak since October 2012. The stock is 32% below its 6 October record of $239.24 and market value has fallen from $5.8 trillion to $3.92 trillion. Interim CEO Colette Kress reports Q3 after Tuesday's close. The revenue bar is $108 billion ±2%. The number that decides the reaction is 71 ~ 72%.
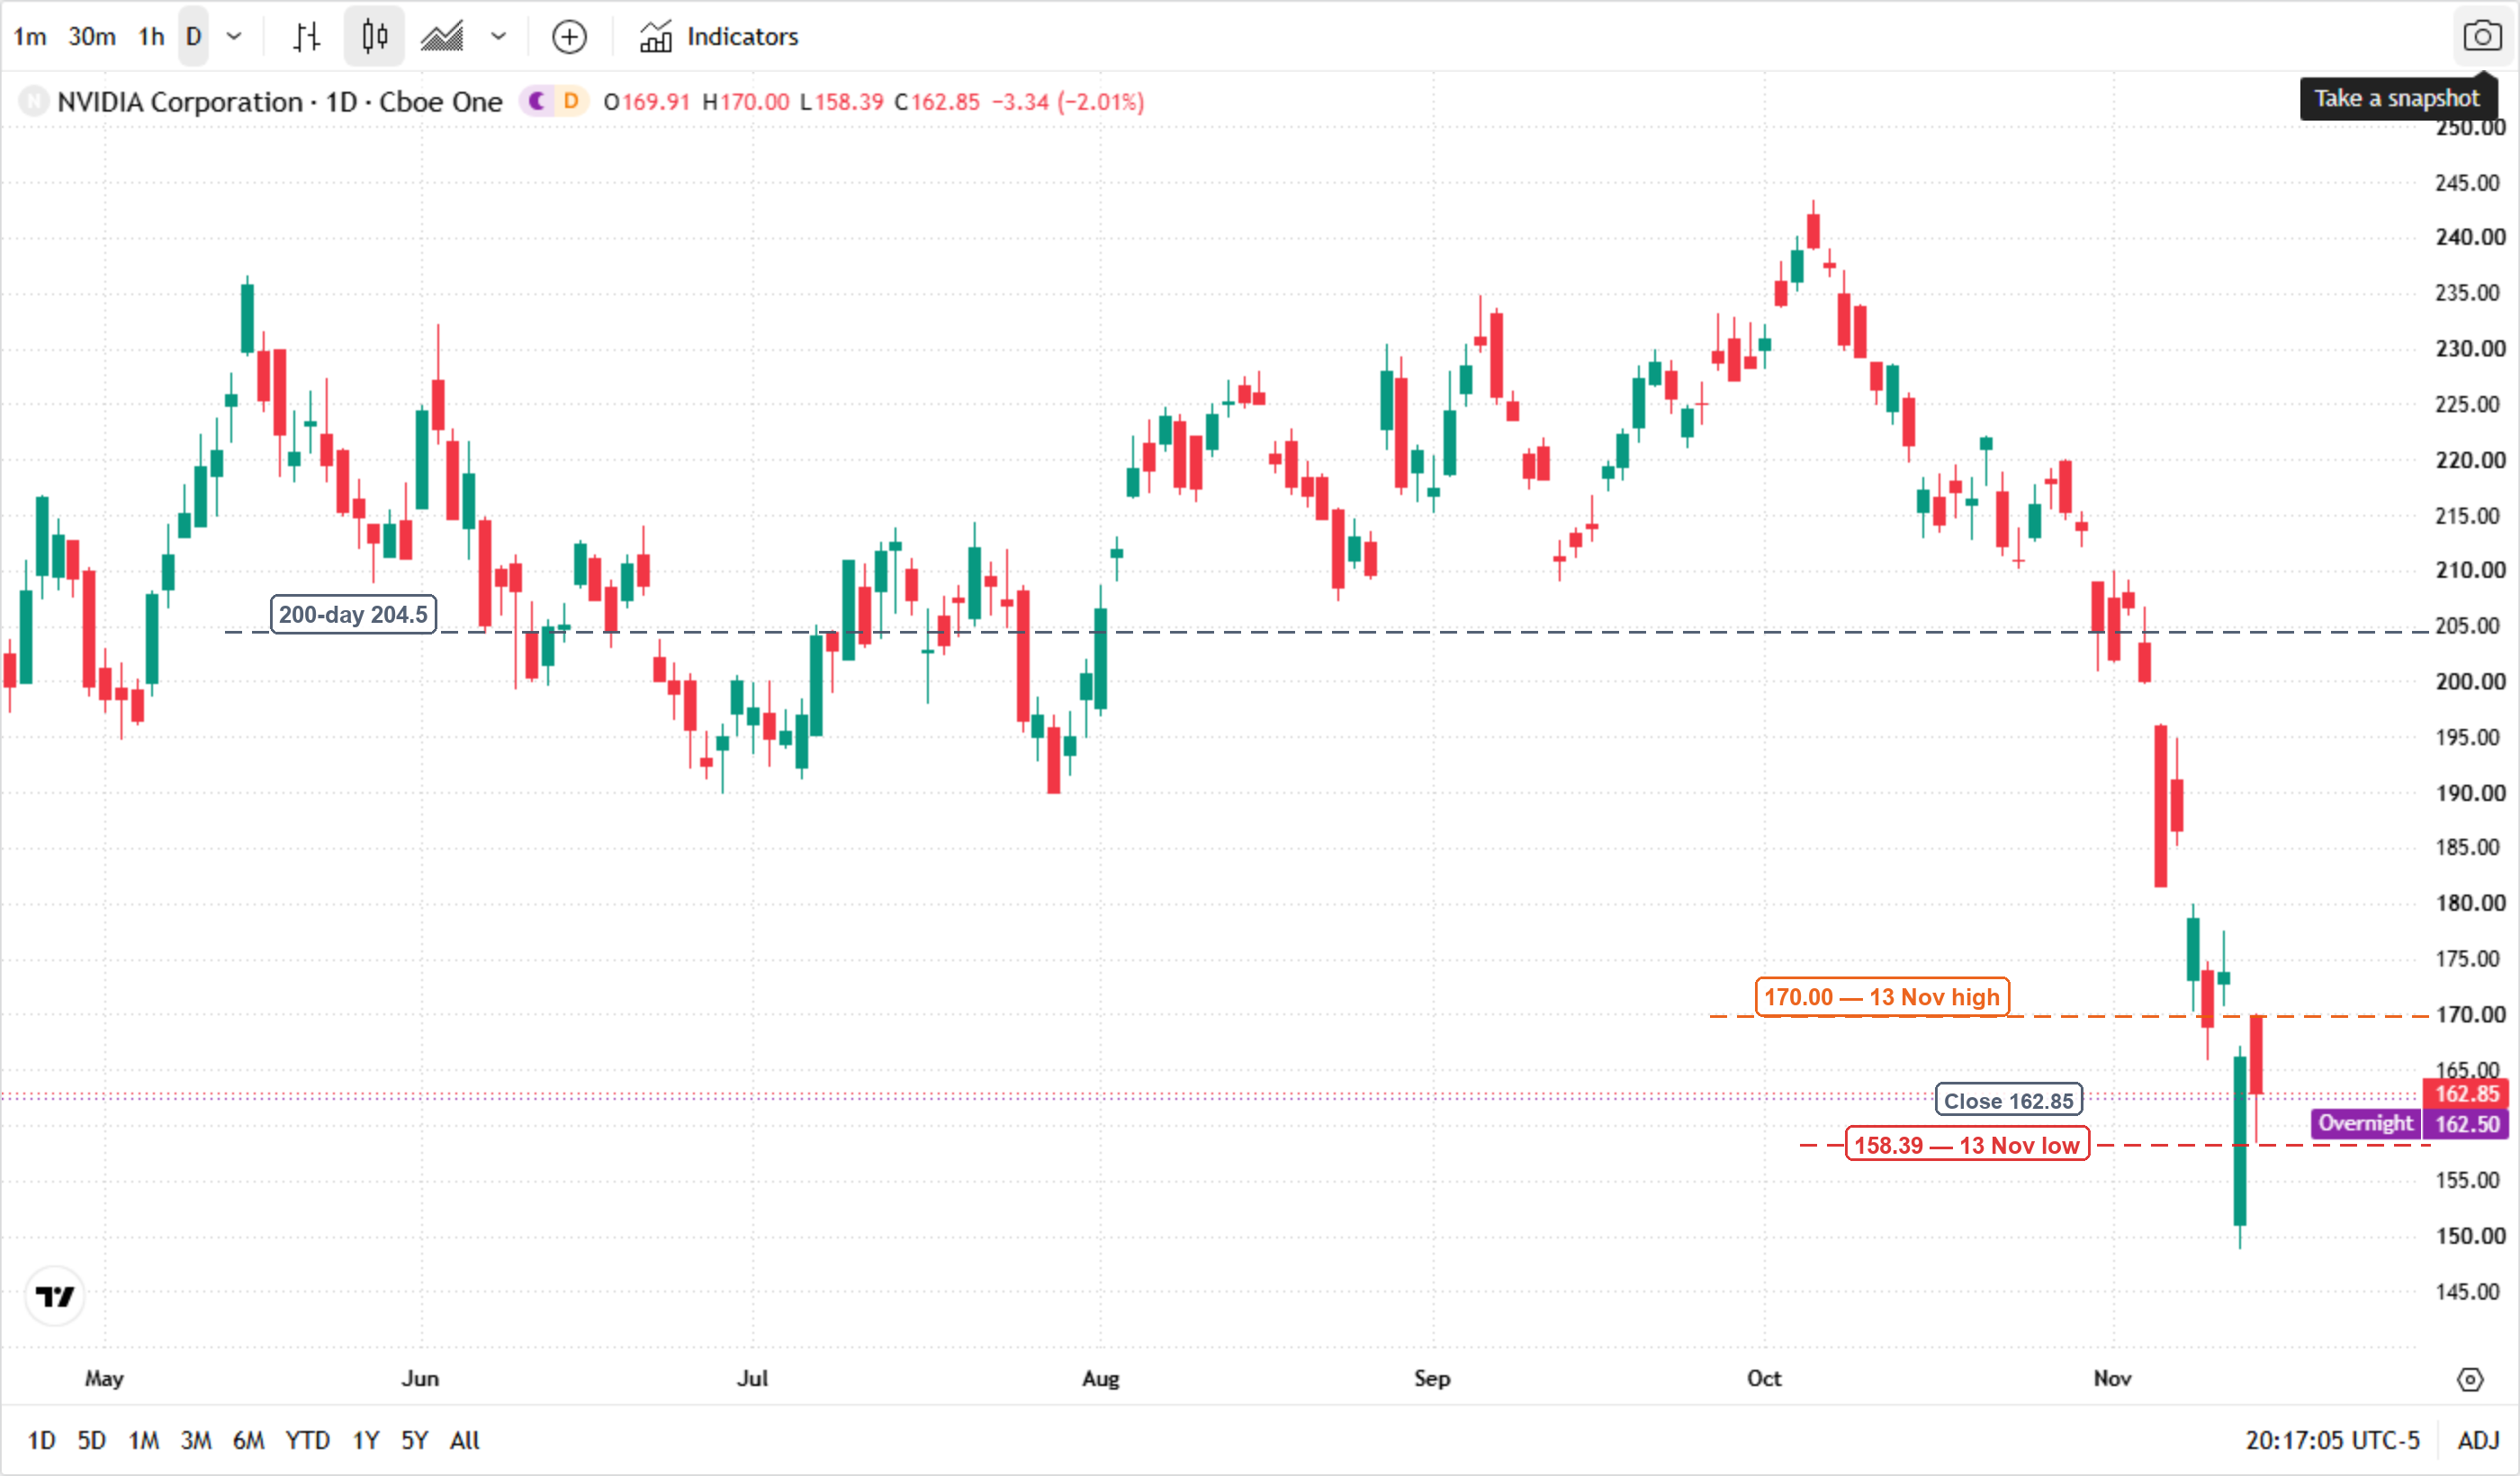
* Chart source: TradingView (NVDA daily, Cboe One feed)
$162.85 already prices a miss
Start with what is already in the price. Eight brokerages cut ratings or targets this week. The median target is now $275 — still 69% above Friday's close. Citi kept Buy but trimmed its target to $285 from $315, expecting a modest EPS beat offset by memory-driven margin pressure. GF Securities went the other way, downgrading to Hold with a $188 target. Retail investors bought roughly $1.6 billion of the dip through Thursday.
That is the shape of a de-risked print: the stock has fallen 32% in six weeks, the sell side has already reset, and the bar for a positive surprise on revenue is low. The risk has moved from "will they beat" to "what do they guide".
What the sell side changed this week
The cuts were not about demand. They were about the two things a new CEO cannot answer on day one: how much of the $145 billion supply commitment is defensible, and how far margins fall before memory pricing normalises. Both sit below the revenue line.
71% is the number, not $108 billion
Company guidance is $108 billion ±2%, gross margin 74% ±50bp, non-GAAP opex around $9.0 billion, and zero China data-center compute revenue. Consensus has revenue at $108.7 ~ 108.8 billion (+90% year on year), EPS of $2.47, data center at $101.8 billion, and a Q4 guide of $124.9 billion.
For context, Q2 delivered $96.2 billion (+106%), data center $89.0 billion (+117%, 92.5% of revenue), a 75% non-GAAP gross margin and record free cash flow of $49 billion. The revenue trajectory is not the problem.
The margin is. Kress previously guided gross margin to bottom at 71 ~ 72% in Q4 before recovering to 72 ~ 73% in FY2028 on memory pricing. A trough below 71% would likely outweigh any revenue beat, because it resets the FY2028 earnings power that the $275 median target is built on.
The Q4 guide and the FY28 frame
The single biggest stock mover is the preliminary FY2028 outlook of roughly 70% revenue growth, which the company has described as supply-constrained. Consensus had been around 44%. That gap — 70% versus 44% — is the entire bull case in one number, and it is also the most fragile: it assumes memory supply and customer financing both hold.
Here is the uncomfortable counter-evidence. Days sales outstanding have stretched to 60 days, and third-party capital commitments have climbed toward $500 billion, with up to $125 billion of company-backed guarantees. If end demand were as strong as the FY2028 frame implies, receivables and guarantees should not be stretching this quickly.
158.39 is the line
The chart is simple. The 200-day average sits at 204.5, 26% above Friday's close — the trend is broken. Friday's range was 158.39 to 170.00, and the close landed near the low. A close below 158.39 opens 150, the 12 November intraday low. Reclaiming 170 is the first sign the print was absorbed; 204.5 is where the trend would actually repair.
| Level | Price | What it means |
|---|---|---|
| 200-day average | 204.5 | Trend repair only above here |
| 13 Nov high | 170.00 | First absorption signal |
| 13 Nov close | 162.85 | The print is priced from here |
| 13 Nov low | 158.39 | The line that decides the week |
| 12 Nov intraday low | 150.00 | Next support if 158.39 breaks |
What would change the call
The print resolves into three branches. The table keeps the two-way scenario requirement in one place:
| Scenario | What has to happen | Q4 guide | Stock path |
|---|---|---|---|
| Beat and guide up | Revenue > $110B, GM ≥ 74%, Q4 above $125B | Above $125B | 170 → 175, then 204.5 in play |
| In line | Revenue $108 ~ 109B, GM 74%, Q4 $124 ~ 125B | $124 ~ 125B | 158 ~ 165, range holds |
| Miss or margin break | Q4 GM trough below 71% or Q4 guide below $120B | Below $120B | 150, then 145 |
The asymmetry is deliberate: the stock has already paid for a miss, so the downside from an in-line print is limited; the upside needs the FY2028 frame to survive the call. That frame is a margin story, not a revenue story.
Read more
* The content presented above, whether from a third party or not, is considered as general advice only. This article should not be construed as containing investment advice, investment recommendations, an offer of or solicitation for any transactions in financial instruments.


