


With a Nearly 7% Yield, Is Energy Transfer Stock a Buy as It Looks to Turbocharge Growth?
Key Points
Energy Transfer turned in strong Q3 results, helped by continued energy market volatility.
The company is ramping up growth and is the cheapest stock in the space.
- Motley Fool Issues Rare "Total Conviction" Buy Alert ›
Energy Transfer (TXSE: ET) is one of the best companies in the world at profiting from energy market volatility, and that continued in Q3, leading the company to report outstanding results. Meanwhile, the master limited partnership (MLP) plans to turbocharge its growth capital expenditures (capex), given the opportunities it sees.
As it's one of the midstream stocks with the best growth outlooks and cheapest valuations, it now looks like a great time to buy this high-yield stock. Let's take a closer look at its Q3 results and prospects.
Missed AI’s "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our analysts, we’re only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
Image source: The Motley Fool.
Strong growth
Energy Transfer turned in an outstanding quarter, with its adjusted earnings before interest, taxes, depreciation, and amortization (EBITDA) soaring by 31% year over year to $5.03 billion. It saw strength across its seven operating segments, with record intrastate and midstream gathering volumes.
Meanwhile, EBITDA from its Sunoco subsidiary more than doubled to $1.05 billion, bolstered by strong refining margins. Its largest segment, NGL (natural gas liquids) and refined products, saw adjusted EBITDA rise 16% to $1.22 billion. Its NGL segment results benefited from a $177 million increase in marketing margin from favorable market conditions.
Distributable cash flow (DCF) to partners, which is operating cash flow minus maintenance capex, jumped 33% to $2.52 billion, up from $1.9 billion a year ago. It paid out $1.18 billion in distributions in the quarter, for a coverage ratio of 2.1x. Energy Transfer also raised its quarterly distribution by 3% year over year to $0.3425 per unit.
The company also once again meaningfully raised its full-year EBITDA forecast, taking it to a range of $19.7 billion to $19.9 billion. That's up from an earlier forecast of $18.8 billion to $19.1 billion and well above its original projection of $17.3 billion to $17.7 billion. Its Q4 results will benefit by roughly $285 million from previously disputed natural gas purchases that will now be recognized next quarter.
Energy Transfer has a large and growing project backlog, with plans to spend between $5.4 billion and $5.6 billion in growth capex this year. Meanwhile, it said it plans to spend approximately $7 billion in 2027. These projects are largely contracted under long-term commitments with expected mid-teen returns
Energy Transfer's biggest projects are its $2.7 billion Hugh Brinson Pipeline and $5.6 billion Desert Southwest pipeline. Phase 1 of its Hugh Brinson project came online earlier this year, while Phase 2 is expected to come online in Q1 of next year. Meanwhile, its other major Permian natural gas takeaway project, Desert Southwest, is scheduled to enter service by the end of 2029. It also announced that it will proceed with its $1.6 billion South Mississippi Pipeline.
A top high-yield stock to buy now
Demand for natural gas is booming due to AI data centers, population growth, the continued conversion of coal-fired power plants to natural gas, and international exports. As one of the largest liquid natural gas exporters in the U.S. and with a strong position in the Permian Basin, which has some of the country's cheapest associated natural gas, Energy Transfer is involved in numerous high-return projects.
While the company is currently experiencing strong growth, bolstered by energy market volatility, these projects will drive more sustainable long-term growth. The stock also currently offers an attractive 6.8% yield and a growing distribution, which is well covered by its DCF.
Data by YCharts.
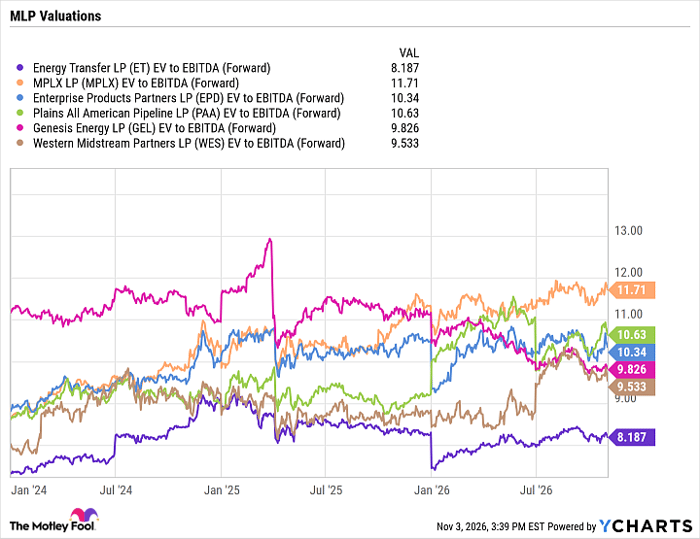
Despite its growth pipeline and well-covered distribution, Energy Transfer remains the cheapest midstream MLP by a wide margin, trading at a forward enterprise value-to-EBITDA multiple of just 8.2 times. That provides the stock with plenty of upside potential over the next few years, as it has the potential to not only see strong EBITDA growth from its project backlog but also multiple expansion.
As such, Energy Transfer is the top midstream stock to own in my view.
Should you buy stock in Energy Transfer right now?
Before you buy stock in Energy Transfer, consider this:
The Motley Fool Stock Advisor analyst team just identified what they believe are the 10 best stocks for investors to buy now… and Energy Transfer wasn’t one of them. The 10 stocks that made the cut could produce monster returns in the coming years.
Consider when Netflix made this list on December 17, 2004... if you invested $1,000 at the time of our recommendation, you’d have $358,037!* Or when Nvidia made this list on April 15, 2005... if you invested $1,000 at the time of our recommendation, you’d have $1,229,708!*
Now, it’s worth noting Stock Advisor’s total average return is 897% — a market-crushing outperformance compared to 211% for the S&P 500. Don't miss the latest top 10 list, available with Stock Advisor, and join an investing community built by individual investors for individual investors.
See the 10 stocks »
*Stock Advisor returns as of November 6, 2026.
Geoffrey Seiler has positions in Energy Transfer, Enterprise Products Partners, Genesis Energy, Sunoco, and Western Midstream Partners. The Motley Fool recommends Enterprise Products Partners. The Motley Fool has a disclosure policy.
Recommended Articles


