



Indian Rupee gains as oil prices remain broadly in corrective phase
- The Indian Rupee holds its ground against the US Dollar as oil prices remain in a corrective phase.
- Market experts see limited downside for oil prices amid ongoing tensions between Saudi Arabia and Iran-backed Houthis.
- The US Dollar outperformed on strong hawkish Fed expectations.
The Indian Rupee (INR) opens higher again versus the US Dollar (USD) on Tuesday. The USD/INR pair drops to near 95.65 as the Indian currency gains due to the consistent decline in oil prices.
In the opening session, the MCX Crude Oil contract expiring on October 19 is up 1.2% to near Rs. 8,940, but is still close to its 12-day low of Rs. 8,753 posted on Monday.
Lower oil prices bode well for currencies from economies, such as India, which rely heavily on oil imports to meet their energy needs.
Oil prices have remained under pressure amid optimism that the supply of energy products from Saudi Arabia would improve, as the nation vowed to explore alternatives to increase oil shipments. However, financial market experts warn that the recent decline in oil prices could be limited due to ongoing tensions between Saudi Arabia and Iran-backed Houthis.
Saudi attacks keep oil downside in check
Analysts at OCBC suggest that crude prices may find "some renewed support after fresh attacks on Saudi Arabia over the weekend," with Houthis claiming missile and drone strikes on Riyadh and an Aramco facility at Yanbu. They note that Saudi authorities reported the attacks on Yanbu and several other locations were "thwarted, with no fresh damage to oil infrastructure" so far. Even so, OCBC argues that "weekend attacks on Saudi Arabia keep supply/geopolitical risks alive, potentially limiting near-term downside in oil prices," and that "further downside in oil may be limited unless Saudi flows normalise and attacks on energy infrastructure subside."
Investors await meeting between US and Gulf leaders
Later in the day, leaders from Gulf nations and the United States (US) are likely to have a meeting on the sidelines of the United Nations (UN) General Assembly in New York. Related parties are expected to discuss possible ways to increase the oil supply through the Middle East. US President Donald Trump is also expected to meet Iranian President Masoud Pezeshkian to talk about ongoing conflicts.
A positive outcome of these meetings would be unfavorable for the oil price, which in turn, would ease fears of high inflation expectations globally.
Firm hawkish Fed expectations need to be validated by US data
A string of market experts has explicitly said that the recent strength in the US Dollar is backed by Federal Reserve’s (Fed) interest rate hike expectations. Last week, the Fed hiked interest rates by 25 basis points (bps) to 3.75%-4.00% and signaled at least one more this year.
Experts believe that firm hawkish Fed expectations need validation by upcoming US data.
Analysts at HSBC note that the USD “strengthened following the decision.” They highlight that “the median 2026 ‘dot’ implies one additional hike before year-end,” with “a significant minority of participants still anticipating a further rate rise in 2027.” HSBC argues that “this path is more hawkish than a ‘one-and-done’ outcome but remains below current market pricing,” meaning they “do not expect a major repricing of rate expectations or the USD.” Instead, the bank expects that “the market’s attention is likely to focus on whether incoming data validate the final projected increase this year,” suggesting any further Dollar gains will hinge on how the data track against the Fed’s projected path.
USD/INR Technical Analysis
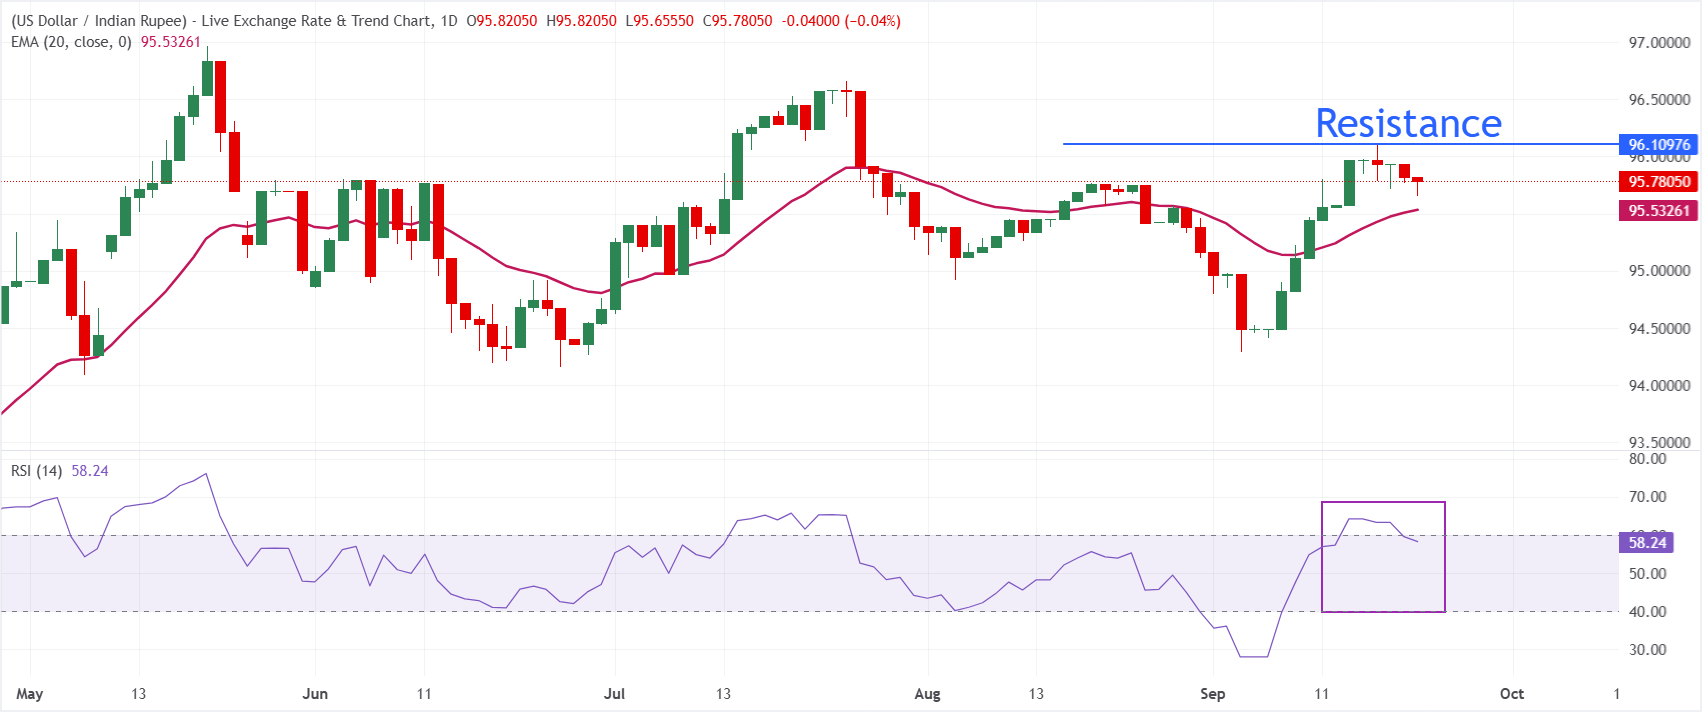
In the daily chart, USD/INR trades at 95.65, keeping a constructive bullish bias as it holds above the 20-day exponential moving average (EMA) at 95.53. The pair has reclaimed short-term trend support, and the Relative Strength Index (14) near 58 suggests firm but not overextended upside momentum, hinting that buyers remain in control while avoiding overbought conditions.
On the downside, immediate support is seen at the 20-day EMA at 95.53, followed by 95.00. Looking up, the previous week's high near 96.00 is the key hurdle.
(The technical analysis of this story was written with the help of an AI tool. Know more.)
Indian Rupee FAQs
The Indian Rupee (INR) is one of the most sensitive currencies to external factors. The price of Crude Oil (the country is highly dependent on imported Oil), the value of the US Dollar – most trade is conducted in USD – and the level of foreign investment, are all influential. Direct intervention by the Reserve Bank of India (RBI) in FX markets to keep the exchange rate stable, as well as the level of interest rates set by the RBI, are further major influencing factors on the Rupee.
The Reserve Bank of India (RBI) actively intervenes in forex markets to maintain a stable exchange rate, to help facilitate trade. In addition, the RBI tries to maintain the inflation rate at its 4% target by adjusting interest rates. Higher interest rates usually strengthen the Rupee. This is due to the role of the ‘carry trade’ in which investors borrow in countries with lower interest rates so as to place their money in countries’ offering relatively higher interest rates and profit from the difference.
Macroeconomic factors that influence the value of the Rupee include inflation, interest rates, the economic growth rate (GDP), the balance of trade, and inflows from foreign investment. A higher growth rate can lead to more overseas investment, pushing up demand for the Rupee. A less negative balance of trade will eventually lead to a stronger Rupee. Higher interest rates, especially real rates (interest rates less inflation) are also positive for the Rupee. A risk-on environment can lead to greater inflows of Foreign Direct and Indirect Investment (FDI and FII), which also benefit the Rupee.
Higher inflation, particularly, if it is comparatively higher than India’s peers, is generally negative for the currency as it reflects devaluation through oversupply. Inflation also increases the cost of exports, leading to more Rupees being sold to purchase foreign imports, which is Rupee-negative. At the same time, higher inflation usually leads to the Reserve Bank of India (RBI) raising interest rates and this can be positive for the Rupee, due to increased demand from international investors. The opposite effect is true of lower inflation.
Recommended Articles


