


CoreWeave Stock Is Down 70% From Its High. Could a Huge Rebound Come in 2027?
Key Points
Nvidia may no longer be backing CoreWeave following a change in leadership.
CoreWeave is spending big to generate huge growth -- and that brings risks.
- 10 stocks we like better than CoreWeave ›
CoreWeave (NASDAQ:CRWV) investors have been left wanting more for a long time. Its stock peaked shortly after its initial public offering in the summer of 2025, and it has struggled since then.
To make matters worse, CoreWeave's biggest backer, Nvidia (NASDAQ:NVDA), may have just lost its biggest supporter with Jensen Huang resigning from the CEO role. This could cause CoreWeave's future to be in jeopardy, and the market has responded accordingly.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
But is there more to the picture here? Let's take a look at CoreWeave's stock and see if 2027 could be a year for a major rebound.

Image source: Getty Images.
The neocloud segment is in question
CoreWeave is what's known as a neocloud company. It's very similar to a cloud computing firm, except that all of its computing power is dedicated to AI workloads. The core concept makes a lot of sense: Build out AI computing capacity, then rent that back to the AI hyperscalers. This business model has worked for cloud computing providers; why couldn't it work for a start-up like CoreWeave? The biggest problem is funding.
CoreWeave doesn't have any other businesses to fund its build-out. The major cloud computing providers do. Instead, it must rely on external funding, be it through issuing shares or by taking on debt. That makes CoreWeave a very risky business, as it's racing the clock to build out enough infrastructure to be profitable and self-sustaining before enough AI computing capacity has been built out.
Last month, the market was pricing CoreWeave's debt like it was about to run out of time, as the yields on these bonds reached distressed levels. This means that the market is pricing in a high likelihood of CoreWeave not being able to repay its obligations, which could lead to bankruptcy. That is obviously a worst-case scenario, but the bulls would always point to being backstopped by Nvidia.
Nvidia was a major financier of CoreWeave and provides its computing units on favorable terms. Jensen Huang was a huge proponent of getting Nvidia's products into the hands of all sizes of companies, even if it wasn't the most financially profitable thing to do. With interim CEO Colette Kress, who comes from the CFO role and has a more financially conservative background, this practice may come to an end.
That could be a problem for CoreWeave, but just how close is it to becoming self-sustaining and not needing any outside intervention?
CoreWeave has a lot of growth on the table
What's not up for debate is how quickly CoreWeave is growing. During Q3, its revenue rose 168% year over year to $3.7 billion. Its revenue backlog also crossed $132 billion, showing it still has a lot of growth to come.
However, it's spending big to achieve this growth, as its capital expenditure bill was $14.5 billion in the quarter. That's a long payoff timeline, and CoreWeave could have some problems staying afloat long enough if it loses access to outside funding at decent rates.
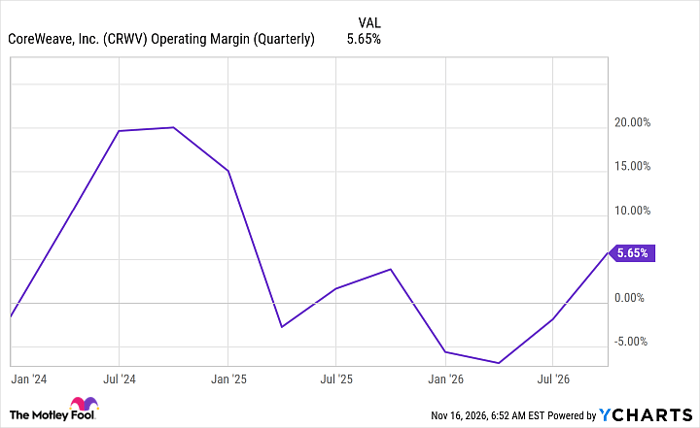
CRWV Operating Margin (Quarterly) data by YCharts
However, it has proven it can run profitably. At just over a 5% operating margin last quarter, CoreWeave can turn a profit. Still, all of that is quickly eaten up by massive capital expenditure bills, debt interest, and hardware depreciation, which is why CoreWeave posts a large net income loss each quarter.
This won't change anytime in the near future, and CoreWeave will take some time before it has reached a steady state where capital expenditure can be funded by the business. I think the market will view CoreWeave with skepticism until it can balance its expenditures with income.
That may be some time, so I think it's OK to steer clear of this stock for now.
Should you buy stock in CoreWeave right now?
Before you buy stock in CoreWeave, consider this:
The Motley Fool Stock Advisor analyst team just identified what they believe are the 10 best stocks for investors to buy now… and CoreWeave wasn’t one of them. The 10 stocks that made the cut could produce monster returns in the coming years.
Consider when Netflix made this list on December 17, 2004... if you invested $1,000 at the time of our recommendation, you’d have $327,620!* Or when Nvidia made this list on April 15, 2005... if you invested $1,000 at the time of our recommendation, you’d have $959,410!*
Now, it’s worth noting Stock Advisor’s total average return is 802% — a market-crushing outperformance compared to 205% for the S&P 500. Don't miss the latest top 10 list, available with Stock Advisor, and join an investing community built by individual investors for individual investors.
See the 10 stocks »
*Stock Advisor returns as of November 17, 2026.
Keithen Drury has positions in Nvidia. The Motley Fool has positions in and recommends Nvidia. The Motley Fool has a disclosure policy.
Recommended Articles


