


1 Unstoppable Stock-Split Stock to Buy Before It Joins Nvidia, Alphabet, Microsoft, and Apple in the $3 Trillion Club
Key Points
Facebook's parent company, Meta Platforms, is planning to execute a 2-for-1 stock split in January by introducing a new class of shares.
Meta is coming off a strong third quarter, with engagement on Facebook and Instagram hitting record highs, and the Muse artificial intelligence assistant attracting rapid adoption.
Meta has a market capitalization of $1.65 trillion, but it has a clear mathematical path to the ultra-exclusive $3 trillion club.
- Motley Fool Issues Rare "Total Conviction" Buy Alert ›
A high-quality company will typically create tremendous long-term value, sending its stock price soaring into the hundreds or even thousands of dollars. As a result, investors with small portfolios could find themselves priced out of owning one full share, which is why the company might decide to execute a stock split.
Stock splits work by increasing the number of shares in circulation, which reduces the price per share by a proportionate amount. The adjustment is entirely cosmetic, so it doesn't change the value of the underlying company. Facebook parent Meta Platforms (NASDAQ: META) just announced it will execute the equivalent of a 2-for-1 split by introducing a new class of shares.
Missed AI’s "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our analysts, we’re only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
Investors who currently own a single Meta Class A share worth $650 will end up with two shares after the record date: one Class A share with voting rights, and one Class C share with no voting rights, presumably worth $325 each. The prices I've described are merely hypothetical, because we don't know where Meta will be trading when the split eventually happens in January 2027.
In any case, Meta is likely to continue creating substantial value for investors over the long term. The company has a market capitalization of $1.65 trillion as I write this (Oct. 23), but here's why I think it could cross the $3 trillion milestone within the next few years, joining an exclusive club that currently only includes Nvidia, Alphabet, Microsoft, and Apple.

Image source: Getty Images.
Artificial intelligence is transforming Meta's social media apps
Meta's portfolio of social media apps includes Facebook, Instagram, Messenger, WhatsApp, and Threads. During the third quarter of 2026 (ended Sept. 30), a record 3.64 billion people used at least one of them every single day. That number represents almost half of the world's population, so it's getting harder for the company to find new users, especially sincee its apps are banned in populous countries like China.
As a result, Meta is focusing on engagement instead. If each existing user spends more time online, they will see more ads and generate more revenue for the company. Artificial intelligence (AI) plays a central role in this strategy by powering Meta's recommendation algorithms. It learns what type of content users like to see and shows them more of it to keep them locked in. It's working, because chief executive Mark Zuckerberg said engagement hit new record highs on Facebook and Instagram during the third quarter.
But Meta's AI strategy is evolving beyond social media entirely. The company launched a personal AI agent called Muse in September, and it has already attracted more than 10 million users. Zuckerberg says more than one-quarter of them are using it as a personal shopper, with an average purchase size of $200. Managing emails and calendars are other common use cases so far.
Zuckerberg wants Muse to eventually serve billions of people, who he hopes will use it to improve every facet of their lives -- whether they want relationship advice or want help building a business. This will significantly expand Meta's addressable market by creating an opportunity to divert internet traffic from entrenched platforms like Google Search.
Meta is growing rapidly, but AI spending is becoming a headwind
Meta generated $64.6 billion in total revenue during the third quarter, a 26% increase from the year-ago period. It was a strong result, but the company's bottom line is drawing more attention right now.
Meta spent $72 billion on building AI data centers in 2025, and it's on track to spend up to $145 billion this year. Capital expenditures can't be deducted up front because data centers have a useful life of several years, so the company has to depreciate the infrastructure over time. That means the money it spends today will affect its earnings in 2027, 2028, 2029, and beyond.
The impacts are already showing up, because Meta's third-quarter expenses soared by 68% year over year to $51.6 billion. That included a $9.9 billion charge from a legal settlement, but most of the growth was driven by AI infrastructure costs, including depreciation, cloud spending, and data center operations.
Meta still delivered a generally accepted accounting principles (GAAP) profit of $9.8 billion during the quarter, more than tripling from the year-ago period -- but only because the company took a one-time tax hit of $15.9 billion in the third quarter of 2025. Without that, Meta's recent Q3 result would have represented a year-over-year decline of 47%.
Meta's mathematical path to the $3 trillion club
Based on Meta's trailing 12-month GAAP earnings of $29.33 per share, its stock is trading at a price-to-earnings (P/E) ratio of just 22.1. The Nasdaq-100 index has a P/E ratio of 30.2, so Meta looks heavily undervalued compared to a basket of its big-tech peers.
Moreover, Wall Street's average forecast (provided by Yahoo Finance) suggests Meta's earnings could grow modestly to $33.82 per share in 2027, placing its stock at a forward P/E ratio of 18.7.
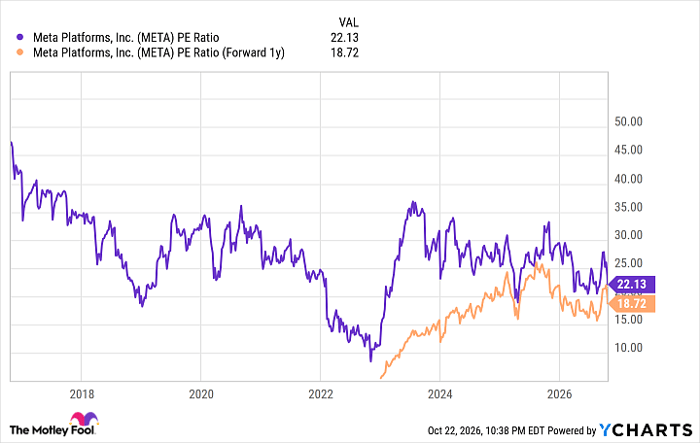
META PE Ratio data by YCharts
That suggests Meta stock would have to soar by 61% over the next 12 months or so just to match the P/E of the Nasdaq-100, which is possible given its P/E was over 30 for a significant part of the last decade. That alone would see Meta's market cap rise to $2.66 trillion, so even modest revenue growth of 13.5% in 2028 would be enough to justify a $3 trillion valuation.
There is no guarantee Meta's P/E will rise to 30.2, but I think it could get there if it shows a phenomenal return on investment on its AI infrastructure spending through the continued success of products like Muse. Alternatively, pulling back on capital expenditures would significantly prop up its earnings, and this is a strategy Zuckerberg used in 2022 when the company's virtual reality spending was getting out of hand.
Nevertheless, even if Meta doesn't join the $3 trillion club by 2028, I think it's likely to get there in the long run.
Should you buy stock in Meta Platforms right now?
Before you buy stock in Meta Platforms, consider this:
The Motley Fool Stock Advisor analyst team just identified what they believe are the 10 best stocks for investors to buy now… and Meta Platforms wasn’t one of them. The 10 stocks that made the cut could produce monster returns in the coming years.
Consider when Netflix made this list on December 17, 2004... if you invested $1,000 at the time of our recommendation, you’d have $355,124!* Or when Nvidia made this list on April 15, 2005... if you invested $1,000 at the time of our recommendation, you’d have $1,296,254!*
Now, it’s worth noting Stock Advisor’s total average return is 901% — a market-crushing outperformance compared to 210% for the S&P 500. Don't miss the latest top 10 list, available with Stock Advisor, and join an investing community built by individual investors for individual investors.
See the 10 stocks »
*Stock Advisor returns as of October 26, 2026.
Anthony Di Pizio has no position in any of the stocks mentioned. The Motley Fool has positions in and recommends Alphabet, Apple, Meta Platforms, Microsoft, and Nvidia. The Motley Fool has a disclosure policy.
Recommended Articles


