


Brent Crude Returns to $110 as Oil Outlook Focuses on Supply Risks and US-Iran Talk Prospects
TradingKey - On October 21 EST, Brent crude oil prices (UKOIL) briefly rose above $110 intraday, while WTI crude oil prices (USOIL) also moved higher, with an intraday gain of about 0.7%. Markets focused on shipping safety in the Strait of Hormuz, risks to Middle East energy facilities, and the impact of U.S.-Iran diplomatic contacts on crude supply expectations.
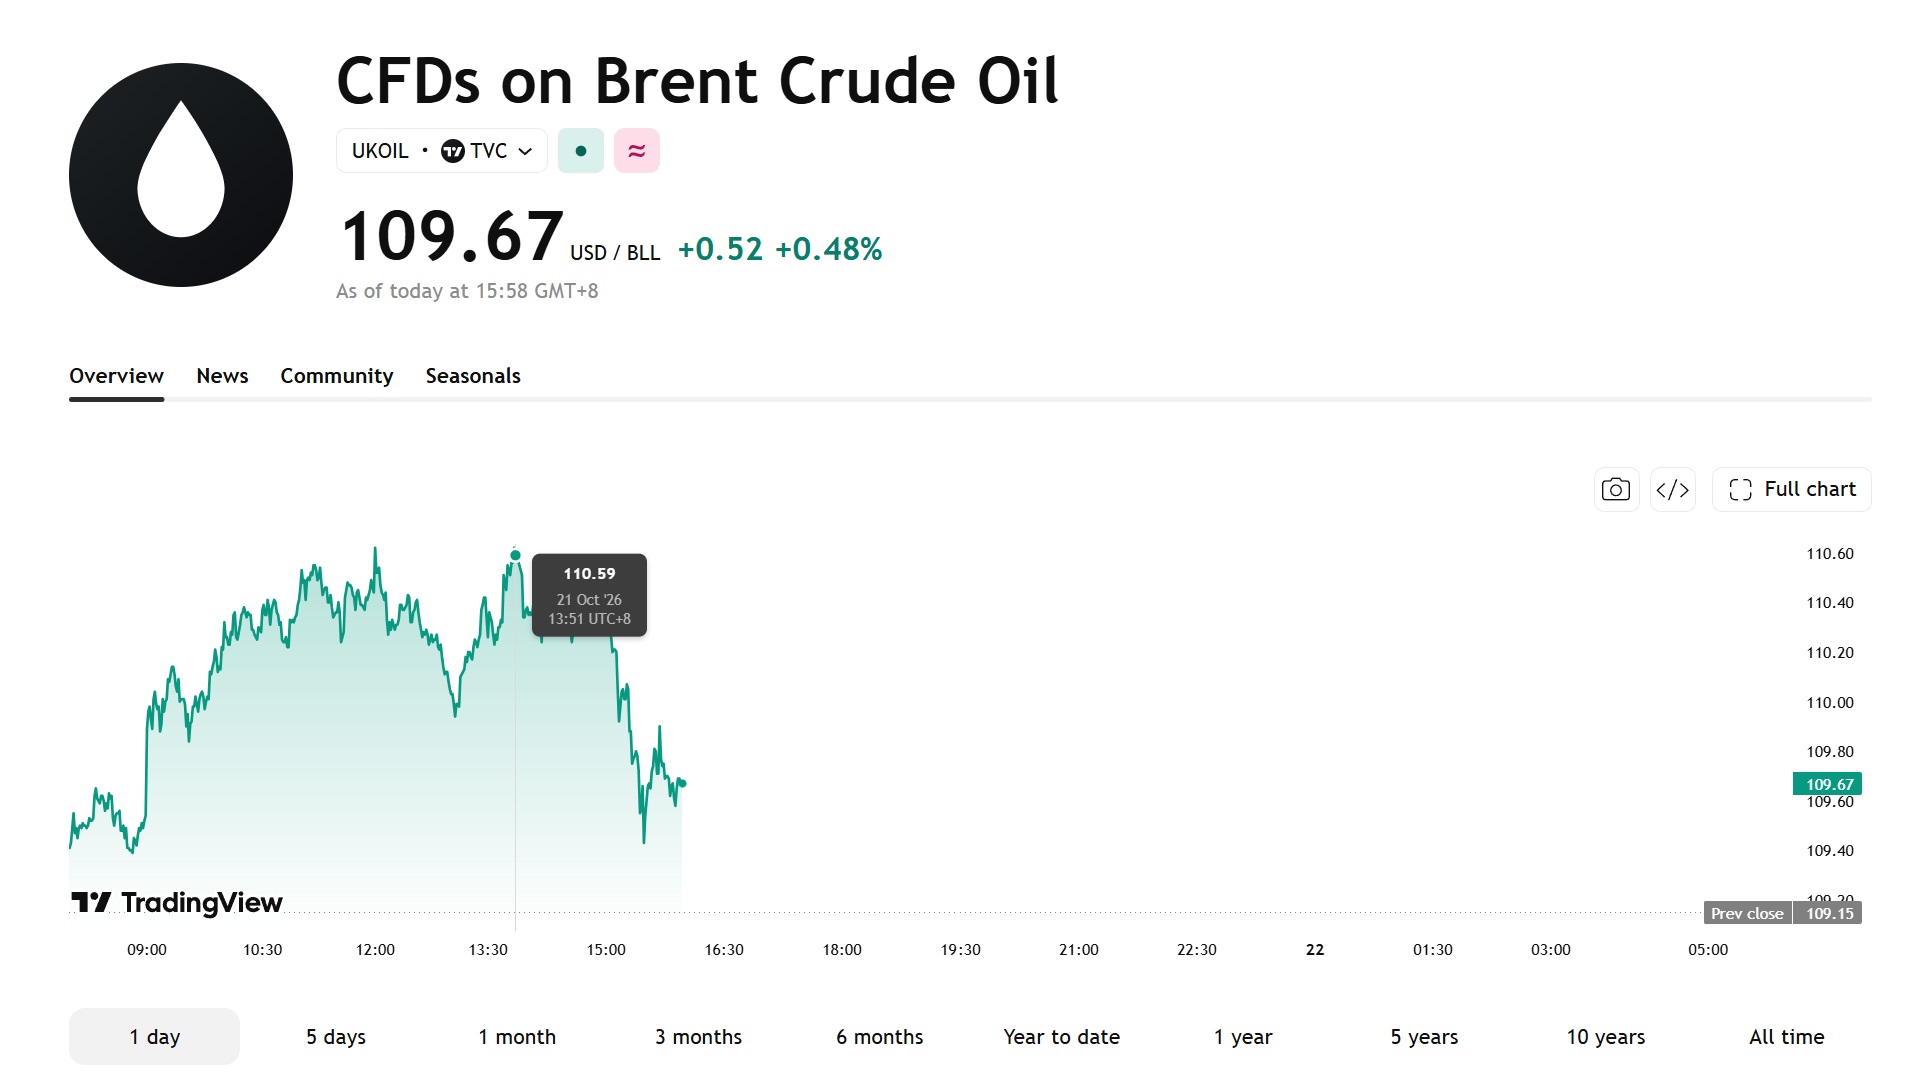
[Source: TradingView]
Strait of Hormuz Risks Support Oil Prices
The Strait of Hormuz is a vital global energy transit corridor. Recently, several vessels in the region have been attacked or affected by related incidents, raising market concerns over shipping disruptions that could impact Middle Eastern crude exports. According to reports, at least 18 vessels have been impacted over the past two weeks, heightening market fears of shipping disruptions and hindered crude exports from the Middle East.
At present, the market has not confirmed a significant drop in Middle Eastern crude supply, and regional crude flows generally maintain a degree of stability. Therefore, the recent rise in oil prices primarily reflects investor concerns over potential supply disruptions.
If shipping gradually recovers or exporters maintain supply through alternative routes, the geopolitical risk premium in crude oil prices may recede.
US-Iran Diplomatic Contacts Impact Supply Expectations
U.S.-Iran diplomatic contacts and negotiation prospects are key variables affecting oil prices. If progress is made in bilateral engagement, the market may lower concerns over regional conflicts and supply disruptions, and oil prices could give up part of their risk premium. Conversely, if the diplomatic process stalls and the Strait of Hormuz or surrounding energy infrastructure continue to come under attack, oil prices may continue to find support.
There are currently no clear signs that the situation has noticeably eased. On October 20, Brent crude prices briefly touched a multi-month high before pulling back amid shifting diplomatic headlines and intraday volatility, showing that the market is still reassessing oil prices between supply risks and expectations of supply recovery.
Inventory and Demand Impact Upside Potential
In the short term, oil prices will also be influenced by U.S. inventory data. Market surveys project that for the latest week, U.S. crude oil inventories fell by about 300,000 barrels, gasoline inventories remained largely flat, and distillate inventories declined by about 1.3 million barrels. If the actual inventory drawdown exceeds expectations, the market may revise up its assessment of short-term U.S. supply-demand tightness; if inventories unexpectedly increase, it could limit gains in oil prices.
Uncertainty remains on the demand side. High oil prices could push up transportation and manufacturing costs, weighing on economic growth and fuel demand through inflationary pressure. The International Energy Agency recently downgraded its crude oil demand growth forecast, indicating that while supply risks are rising, the global demand outlook is also coming under pressure.
What Is the Outlook for Oil Prices?
In the short term, whether Brent crude can hold near $110 will be jointly influenced by factors such as Strait of Hormuz shipping, the U.S.-Iran diplomatic process, and U.S. inventory data.
If geopolitical risks further translate into actual supply disruptions, oil prices may continue to rise; if shipping gradually recovers and diplomatic engagement makes progress, oil prices could give back part of their geopolitical risk premium.
In the medium term, investors also need to focus on global demand, U.S. crude inventories, and supply changes from oil producers. The U.S. Energy Information Administration projects that Brent crude will average around $105 in the fourth quarter of 2026, implying that current prices above $110 may already reflect a geopolitical risk premium.
Therefore, the key to subsequent market dynamics is not just whether the conflict escalates, but whether geopolitical risks cause actual supply disruptions and whether the speed of supply recovery falls short of market expectations.
Recommended Articles


