


ExxonMobil Stock Forecast: $4.5 Billion Refining Windfall Puts XOM at $179 Before Q3 Earnings
TradingKey - ExxonMobil (NYSE: XOM) closed at $178.98 on Friday, October 16, up 2.46% from Thursday. It is currently up about 49% in 2026, and Brent crude closed at $109.86 the same day as the attacks in the Strait of Hormuz escalated.
My thesis is that Exxon is going to have a strong Q3, likely from refining as opposed to crude. The main uncertainty is how long will the disruption in the Middle East keep margins elevated. The catalyst is confirmed: Exxon will report its Q3 results at 5:30 a.m. CT on Friday, October 30, and will hold an earnings call at 8:30 a.m. CT.
What Exxon's Q3 Preview Shows
On October 16, Exxon provided an advance preview of “market and other factors” impacting Q3 results, relative to Q2. The company states it is not an earnings estimate, and excludes operating performance.
Refining continues to be the primary driver. Energy Products margins are estimated to be approximately $4.5 billion. Specialty Products margins are estimated to be about $0.5 billion and Chemical Products margins are estimated to subtract about $0.6 billion. In the Upstream, lower liquids prices are estimated to negatively impact margins by approximately $1.3 billion, while higher gas prices add approximately $0.3 billion.
Planned and other factors, including maintenance, external operational impacts, extra days and approximately $0.9 billion of Upstream entitlements, timing and tax, are estimated to negatively impact results by approximately $1.0 billion. In my view, all of the above factors net to approximately $2.4 billion against Q2 adjusted earnings of $14.7 billion. Again, this is my view and not Exxon guidance.
Reported Earnings Will Look Different
The difference between reported and adjusted results attracts my attention. For Q3, Exxon expects approximately $2.5 billion of negative timing effects. Most of this is attributed to Energy Products, where hedges are marked to market but the physical barrels are not, and generally reverse in following quarters.
Exxon also mentioned a roughly $0.7 billion divestment gain. Based on the above, I think the adjusted results and cash flows, which I will see on October 30, are the appropriate results to analyze.
Q2 Set a High Bar
Q2 reported earnings were $14.5 billion, or $3.48 per share. The adjustments resulted in adjusted earnings of $14.7 billion, or $3.52 per share.
Exxon generated $23.6 billion of operating cash flow and $17.2 billion of free cash flow. The company repurchased $5.1 billion of stock and paid a dividend of $4.3 billion to shareholders. Cumulative structural cost savings versus 2019 were $16.3 billion.
Growth Assets: Permian and Guyana
Production from the Permian Basin was 1.8 million oil-equivalent barrels per day in Q2. Exxon expects 9% compound annual growth in Permian production through 2030. In Guyana, the fifth production vessel has set sail and is expected to begin operations in Q4 of this year. The vessel is expected to add 250,000 barrels of capacity per day.
Risks: Oil Price Dependence and Kashagan
The stock prices in a high oil environment, and the EIA expects Brent crude to average $84 in 2027. A ceasefire or reopened supply routes could reduce crude prices and also compress refining margins.
Legal risk is increasing. According to Bloomberg, Exxon Mobil blocked a proposed settlement to Kazakhstan’s $5.2 billion lawsuit for the Kashagan Field, where Exxon is a consortium partner. The consortium is challenging the fine.
Analysts are divided. Wells Fargo reduced its rating to Equal Weight with a price target of $182 on October 1. Conversely, on October 15, Morgan Stanley raised its target to $185. The average target price is about $175.
ExxonMobil Technical Analysis: XOM Tests $179.17 Resistance After Breaking Out Above $169.60
XOM closed at $178.98, up 2.46% for the day. The stock made a new high for the move and is testing the next target at $179.17. Overnight, the stock pulled back to $177.81. The move above the previous resistance zone at $169.60, has extended the uptrend from the lows of July. Price trades well above the red and blue moving averages at $163.24 and $157.65 respectively.
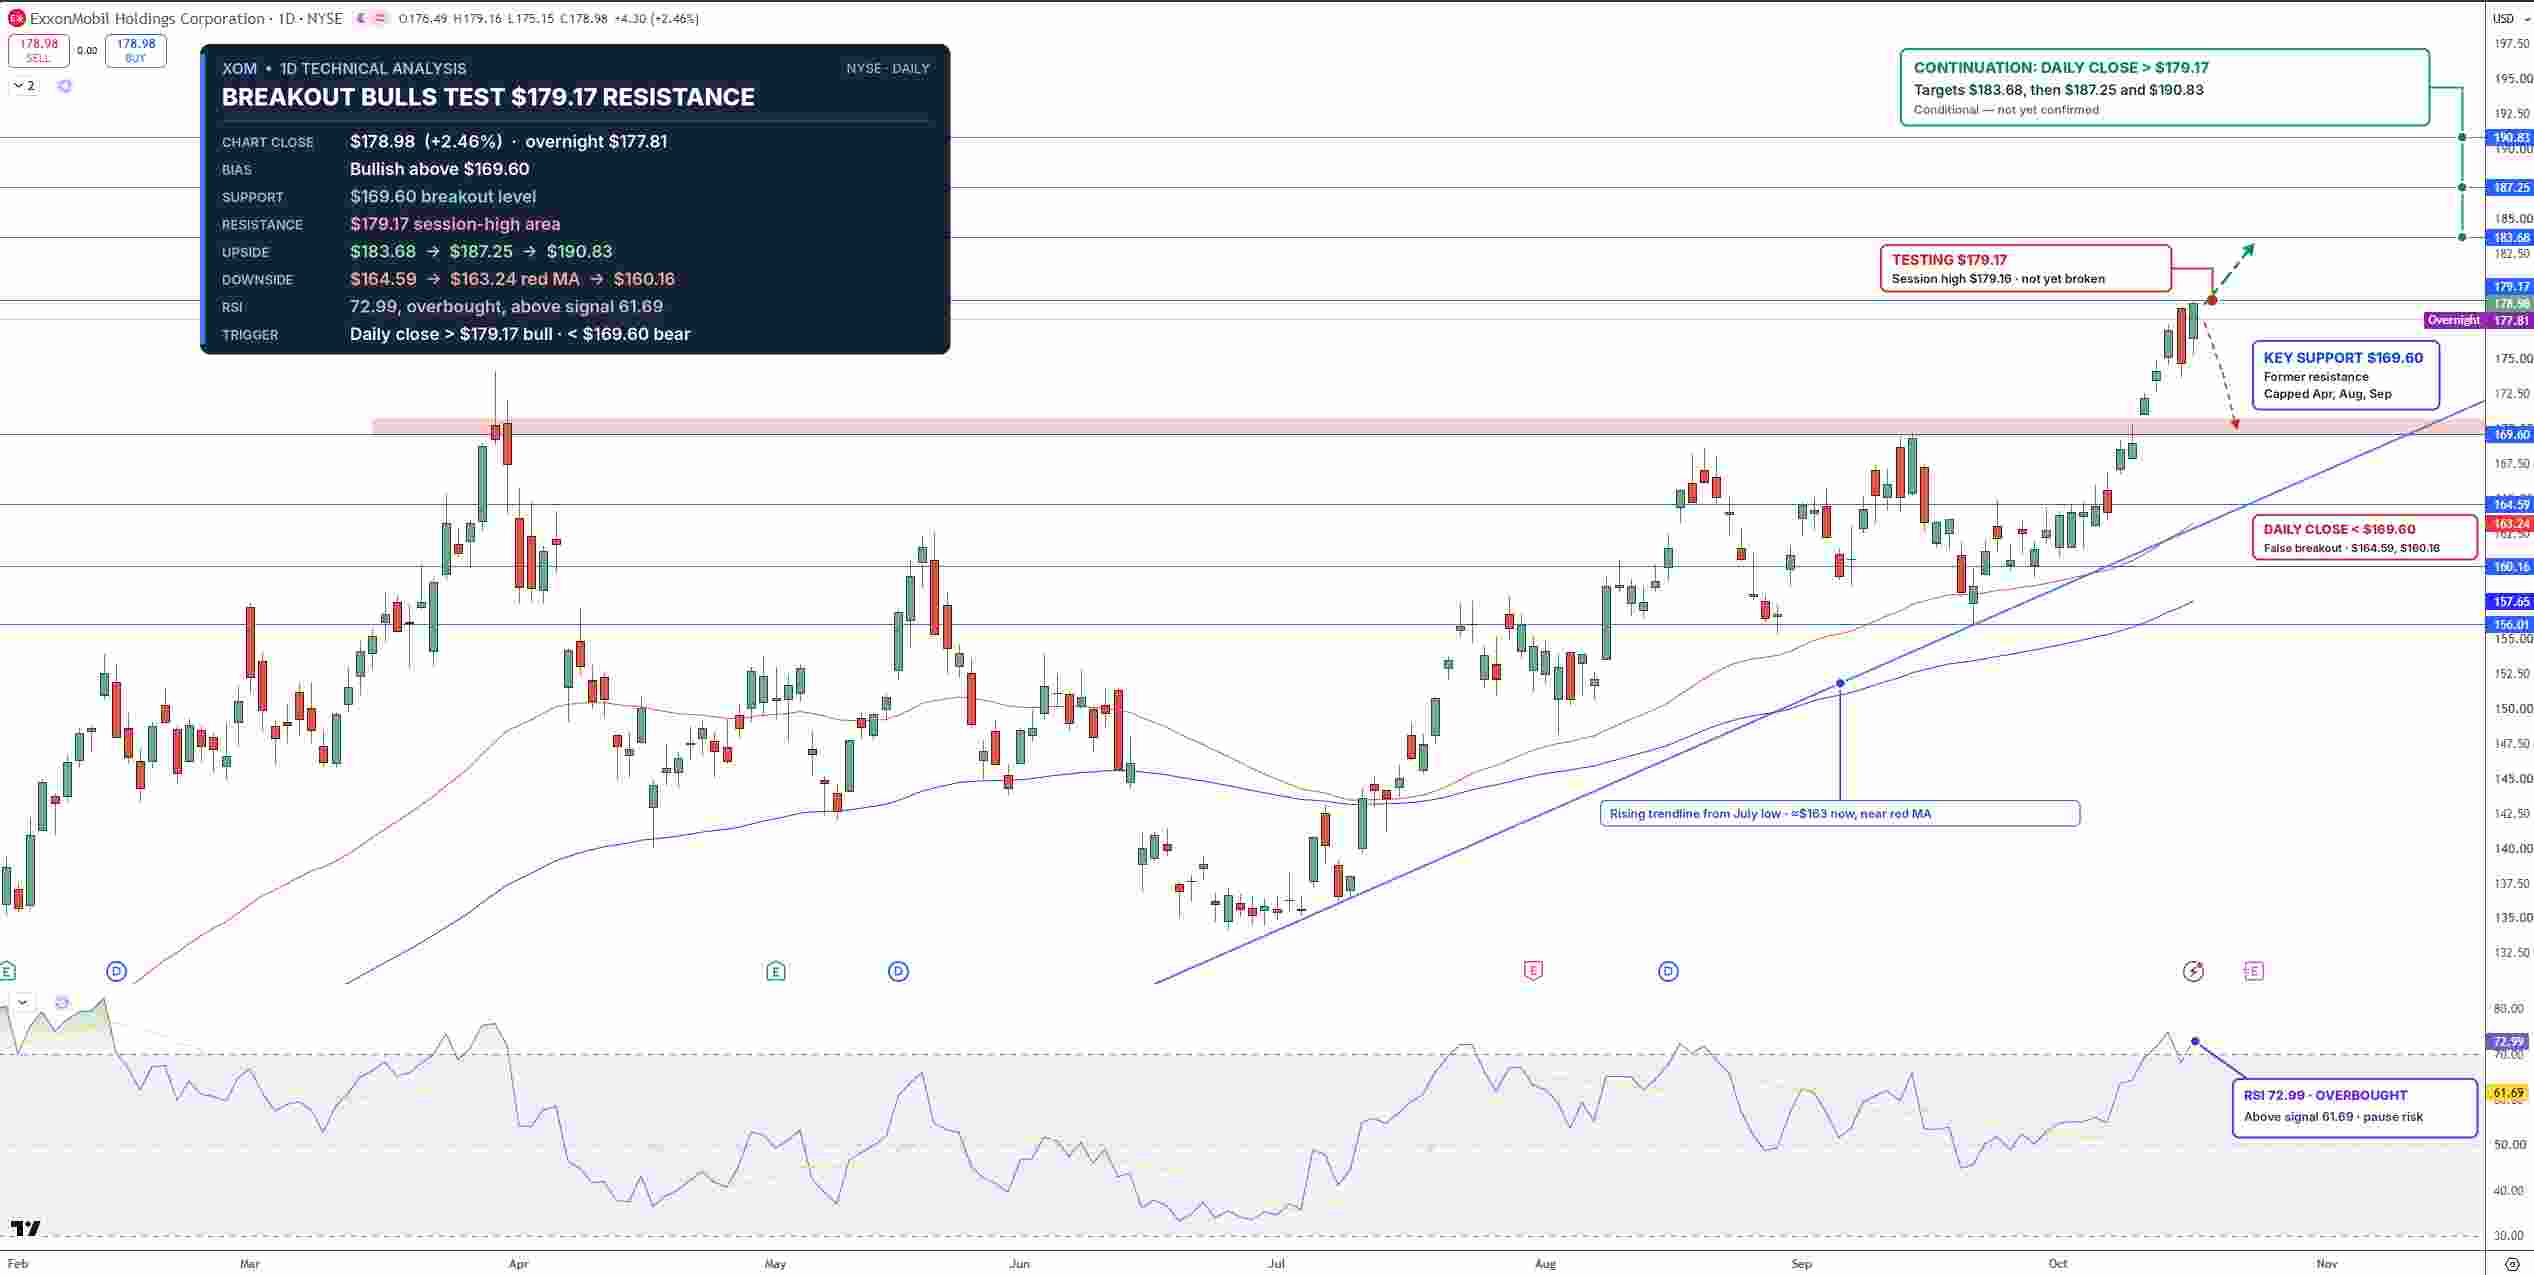
ExxonMobil Stock Price Chart - Source: Tradingview
The RSI is at 72.99, above its signal line at 61.69, and is in overbought territory. The momentum is in favor of the breakout, but the RSI is stretched and gives a signal of a possible consolidation.
XOM recently had a multi-year high and is currently up about 49% year to date. XOM looks poised to test $180 and then higher to the $183.68 level. Previous resistance at $169.60 should now act as support. A break below $164.59 would test the $163.24 level. I am currently bullish XOM and would expect a pullback to the $169.60 support area.
Key Levels
Last close: $178.98, up 2.46% on October 16
Support: $169.60, $164.59, $163.24, $160.16
Resistance: $179.17, $183.68, $187.25, $190.83
RSI: 72.99, above its 61.69 signal line
Bullish trigger: Daily close above $179.17
Bearish trigger: Daily close below $169.60
FAQs
What did ExxonMobil's Q3 2026 preview show?
Exxon said refining margins would likely boost Energy Products by about $4.5 billion in Q3, more than offsetting a $1.3 billion hit from lower liquids prices in the quarter. The company also said it expects about $2.5 billion of negative timing effects in the quarter.
What is the ExxonMobil stock forecast before earnings?
The bias is bullish above $169.60. A close above $179.17 would eye $183.68 and $187.25, and a close below $169.60 would suggest a fakeout down to $164.59.
Bottom Line
Exxon heads into earnings with a refining windfall, record Permian production and Guyana growth on track. The opportunity is a breakout to the upside toward $183.68 if the October 30 report confirms the margin boost. Kashagan, potential easing of Middle East tensions and weaker Q4 margins are the main risks. A close above $179.17 strengthens my case, while a close below $169.60 closes it.
Recommended Articles


