




Investors Are Missing the Boat as Nio Impressively Navigates Brutal Price War
Key Points
China's domestic automotive market, especially the electric vehicle market, is embroiled in a brutal price war.
The price war has eroded margins and hindered revenue growth, and many vehicle sales are currently tracking at a loss.
Nio has managed to offset the ongoing price war and margin pressure with recent launches and its mysterious "other sales" segment.
- 10 stocks we like better than Nio ›
If you haven't heard, there's a bit of a price war going on in China's automotive market. Here are a few statistics to chew on (they're pretty ugly).
In the first eight months of 2026, China's auto industry profits declined 16% from the prior year. As aggressive discounting spread across the industry, it wiped out an estimated $68 billion in revenue over a three-year span, and over 70% of domestic car sales in China are tracking at a loss. With stagnant demand, China's automotive factories are stuck running at a highly inefficient rate, making each vehicle even less profitable. It's not a good situation, and automakers are quickly exporting every sale they can.
Missed AI’s "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our analysts, we’re only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
Despite this margin-eroding price war, Nio (NYSE: NIO) has shone, and there's one obvious, yet still overlooked, reason why.
Image source: Getty Images.
Nio is demonstrating margin strength
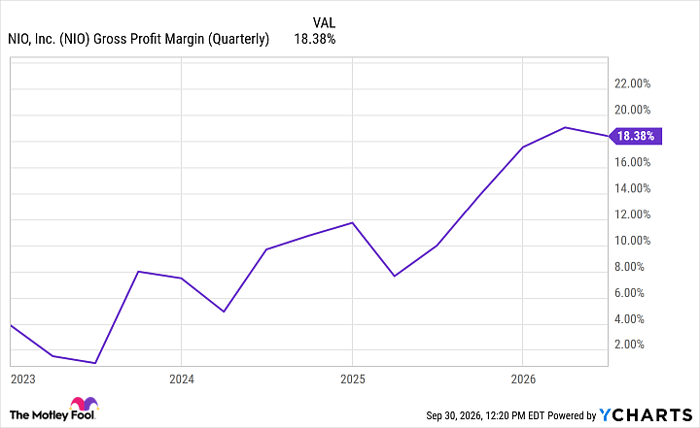
While the broader automotive industry is struggling to maintain margins, Nio has consistently excelled over the past few years and is proving more resilient to margin pressure even now. Here's a look at Nio's gross margins.
Data by YCharts.
Consider this: During the second quarter of 2026, Nio's vehicle deliveries jumped 49.4% compared to the prior year, but its vehicle sales revenue jumped a much more impressive 80.1%. Part of the explanation is that sales of higher-end SUVs, such as the ES8 and ES9, helped improve the sales mix and margins.
In fact, Nio's all-new ES8 five-seat SUV further established its foothold in the premium SUV market. The ES8 has exceeded expectations in sales momentum, recording its 140,000th delivery in 335 days. Nio's executive flagship SUV, the ES9, has made an impact in turning consumers away from gasoline-powered vehicles. The flagship SUV ranked first in sales among passenger vehicles priced above RMB 500,000 ($74,574) in China during June and July.
But Nio's margin strength goes beyond its flagship premium SUVs, which carry massive margins; in fact, it's one of the automaker's riskier assets that's finally paying off.
Battery swaps
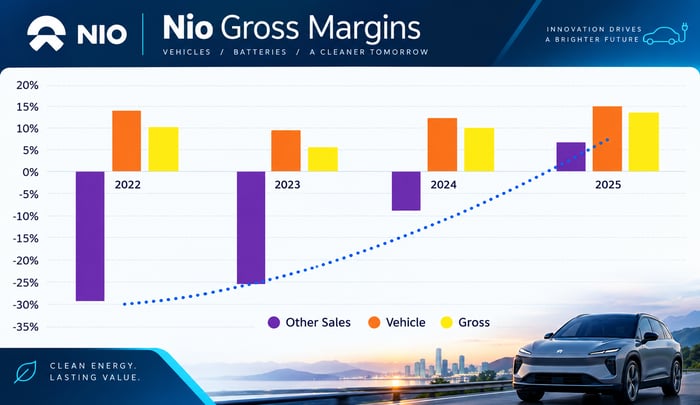
While Nio is supporting vehicle margins in any which way it can, what goes unnoticed is that Nio's "other sales" segment has quickly reversed from negative margins to positive, as you can see in the graph below.
Data source: Nio SEC filings. Chart generated with ChatGPT by author.
Nio operates the largest electric vehicle (EV) energy replenishment network in China. By the end of this year, Nio targets roughly 4,700 swapping stations and hopes to reach 10,000 by 2030. Now, the problem with Nio's battery-swapping network is simply that its capital intensive and expensive up front to build this network of stations, and with a battery-as-a-service (BaaS) user base that is simply limited to its number of cumulative vehicle sales over its young history, the stations can't do enough daily swaps to break even -- for now.
However, as Nio's sales continue to accelerate, including the recent launches of the more affordable sub-brands Onvo and Firefly, it is working to build partnerships and alliances to develop battery-swap standards. That would open the door for other manufacturers to offer Nio's battery-swap network to its customers, instantly ballooning Nio's potential user base and battery-swap demand, which would help develop a rare economic moat in the auto industry through switching costs for Nio.
What it all means for Nio investors
For investors, this might be the inflection point at which Nio's riskiest and most expensive asset, its battery-swap network, becomes a positive driver for the company's business and bottom line. Making it even more interesting was the recent announcement that massive Chinese automaker Geely will buy a 30% stake in Nio's battery-swapping subsidiary, Nio Power.
Geely will fold in its own commercial vehicle battery-swap network and pay about $95 million in cash for its stake. In a second transaction, Nio will purchase a 10% stake in Geely's Haohan Energy, the entity that operates Geely's fast-charging network.
The two Chinese automakers not only benefit from the coverage and synergy created by their combined ecosystems, but it also pushes Nio to the forefront of developing battery-swap standards and becoming the gold standard in China. That could be a lucrative, long-term development for Nio's bottom line.
Should you buy stock in Nio right now?
Before you buy stock in Nio, consider this:
The Motley Fool Stock Advisor analyst team just identified what they believe are the 10 best stocks for investors to buy now… and Nio wasn’t one of them. The 10 stocks that made the cut could produce monster returns in the coming years.
Consider when Netflix made this list on December 17, 2004... if you invested $1,000 at the time of our recommendation, you’d have $365,910!* Or when Nvidia made this list on April 15, 2005... if you invested $1,000 at the time of our recommendation, you’d have $1,418,530!*
Now, it’s worth noting Stock Advisor’s total average return is 930% — a market-crushing outperformance compared to 211% for the S&P 500. Don't miss the latest top 10 list, available with Stock Advisor, and join an investing community built by individual investors for individual investors.
See the 10 stocks »
*Stock Advisor returns as of October 2, 2026.
Daniel Miller has no position in any of the stocks mentioned. The Motley Fool has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy.
Recommended Articles


