




Oracle Stock Is Down 60% From Its High. Here's Why I'm Still Not Buying.
Key Points
Oracle’s cloud infrastructure revenue jumped 121% in its latest quarter.
Its $664 billion backlog points to demand, but building the cloud computing capacity to serve it is costly.
Oracle's debt, lease commitments, and negative free cash flow make the stock too risky for me.
- 10 stocks we like better than Oracle ›
$800 billion.
That's how much just five technology megacaps are expected to spend in capital expenditures this year alone, with the vast majority earmarked for artificial intelligence (AI) projects. It turns out building AI data centers is fabulously expensive.
Missed AI’s "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our analysts, we’re only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
Four of those companies -- hyperscalers Microsoft, Amazon, Alphabet, and Meta Platforms -- are trading at less than 15% off their all-time highs.
One is not: Oracle (NYSE: ORCL). That tech giant's stock is now down nearly 60% from the record it set in September 2025. So, is this the perfect time to buy? Or is there a reason Oracle stock is the odd one out?
Oracle's growth isn't the problem
Let's be clear, Oracle stock has not tumbled because of slow business growth. The company's revenue has grown from $42.4 billion in its fiscal 2022 to $67.4 billion in fiscal 2026. Investors can thank its AI efforts for that. Check out the acceleration on its top line.
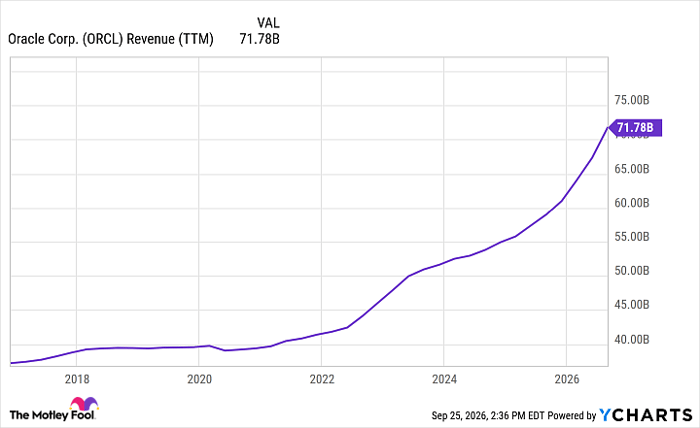
ORCL Revenue (TTM) data by YCharts.
A more granular look at its revenue by segment shows how much of this growth was fueled by AI, and specifically, the AI data center boom. Sales from Oracle Cloud Infrastructure (OCI) arm -- the unit that leases massive data centers and rents out AI compute -- jumped 121% to $7.4 billion in its most recently reported quarter, fiscal 2027 Q1. That unit brought in less than $1 billion in the same period of fiscal 2023.
Behind the strength of OCI, Oracle's companywide remaining performance obligation (RPO) -- contracted revenue for products and services it hasn't delivered yet -- reached an incredible $664 billion as of the end of last quarter.
The cost of growth
Growth is not the issue. Well, at least not that kind of growth. The issue is the costs that are ballooning alongside that sales growth, namely, capex. Oracle's share of that $800 billion figure is $95 billion. While that may be the lowest of the bunch, keep in mind that Oracle makes about a third of Meta's revenue, the next smallest in that group.
Oracle's spending spree is far outpacing its ability to pay for it with the cash the business actually generates. Oracle's free cash flow (FCF) -- the money left over after running the business and paying for capital projects -- was negative $5.4 billion in the latest quarter.
Currently, for every $1 Oracle is spending in capex, its business is only generating 60 cents. Until recently, that figure hadn't really been under $5 for more than 20 years. Take a look at the chart showing that relationship and the steep decline in the last few years.
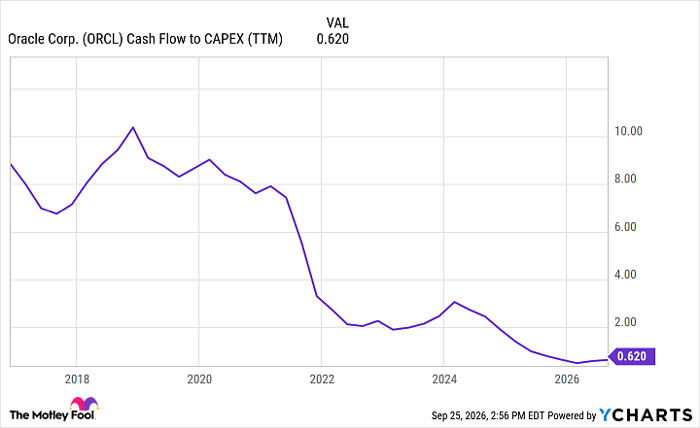
ORCL Cash Flow to CAPEX (TTM) data by YCharts.
Funding the gap with debt
Since it doesn't have nearly enough cash flowing from its operations to cover its capital spending needs, Oracle has turned to debt, and a lot of it. As of the end of August, the company had $125 billion in long-term debt on its books. (It has also been engaging in dilutive secondary stock sales.)
Image source: Getty Images.
And that debt figure doesn't reflect the $288 billion in data-center lease commitments that Oracle hasn't begun paying, and that don't show up on the balance sheet. There's also project-level financing that, although Oracle itself is not responsible for it, adds to the total leverage involved in its bet-the-farm AI build-out.
A data center delay shows the risk
That is especially relevant right now. Recently, the company was in the news for sending a legal notice to the developer of Project Jupiter, a massive data center campus, claiming "force majeure" in a bid to postpone when it starts making lease payments if the facility isn't ready and powered up by the project's March 2028 target date.
Simply, Oracle is attempting to legally shield itself from having to pay the rents it agreed to if Project Jupiter is delayed due to events outside of its control.
If the project's completion is delayed, and Oracle's legal maneuver falls flat, it could be stuck paying those rents without the income that is supposed to fund them. That would not be good for its cash flow picture.
Is Oracle stock worth the risk?
These aren't issues facing Oracle alone. The other tech giants have seen their own free cash flows plummet and have, to various degrees, begun borrowing. The main difference is in relative scale.
Oracle's financial picture is much more precarious than the other four hyperscalers, and if the AI boom slows down -- or worse -- the consequences it faces will be much more severe.
Now, if everything goes according to plan, that could mean there is more upside for Oracle stock. I still don't think it's worth the risk.
Should you buy stock in Oracle right now?
Before you buy stock in Oracle, consider this:
The Motley Fool Stock Advisor analyst team just identified what they believe are the 10 best stocks for investors to buy now… and Oracle wasn’t one of them. The 10 stocks that made the cut could produce monster returns in the coming years.
Consider when Netflix made this list on December 17, 2004... if you invested $1,000 at the time of our recommendation, you’d have $379,123!* Or when Nvidia made this list on April 15, 2005... if you invested $1,000 at the time of our recommendation, you’d have $1,396,103!*
Now, it’s worth noting Stock Advisor’s total average return is 933% — a market-crushing outperformance compared to 212% for the S&P 500. Don't miss the latest top 10 list, available with Stock Advisor, and join an investing community built by individual investors for individual investors.
See the 10 stocks »
*Stock Advisor returns as of September 30, 2026.
Johnny Rice has no position in any of the stocks mentioned. The Motley Fool has positions in and recommends Alphabet, Amazon, Meta Platforms, and Oracle. The Motley Fool has a disclosure policy.
Recommended Articles


