




Dell Stock Forecast: $95B AI Backlog Meets Rising Channel Support at $559
TradingKey - Dell Technologies (DELL) ended the week with its AI infrastructure solutions after a record-breaking quarter. Though, the company is setting up to go in a different direction. Dell’s stock ended the week down 3.5% and is up more than 17% since the beginning of the month. The company is also joining the S&P 100 on Monday. Exceeding expectations in the quarterly report caused the positive momentum. Dell reported $47 billion in quarterly revenue and updated its full year guidance to $192 billion from $167 billion.
AI Server Demand Is Outpacing Shipments
AI server demand is fueling Dell’s rapid growth. In the company’s second fiscal quarter of 2027, Dell disclosed it received orders worth $60.9 billion for AI servers, recognized $16.4 billion in AI server revenue, and finished the quarter with an AI server backlog worth $95 billion.
This compares to the first fiscal quarter of 2027, where Dell disclosed $24.4 billion in AI server orders and recognized $16.1 billion in revenue. Dell anticipates AI server revenue for the full year 2027 will be in the range of $74 billion, up from its previous estimate of $60 billion.
The difference between orders and recognized revenue is one of Dell’s strongest attributes right now. This tells me there is very strong demand for Dell’s products and services. Demand is outpacing Dell’s ability to fulfill it.
In the short-term, Dell needs to ensure it can meet demand by managing the supply of its components.
Neocloud Demand Looks More Durable Than Feared
Some investors are concerned about orders from neocloud customers because they believe that some of this spending may be speculative or less durable than demand tied directly to large end customers. Michael Dell stated that Dell looks past these customers to evaluate demand. He stated that Dell wants to see neocloud contracts tied to large end customers such as Anthropic, OpenAI, Microsoft, Google and Meta.
Clearly Dell has the opportunity to be a large systems integrator for AI infrastructure. This means that Dell would integrate and sell AI infrastructure consisting of components such as compute, storage, and networking as well as associated software.
The PC Business Adds a Second Earnings Engine
Dell’s Client Solutions Group reported a 20% increase in revenue to $15.0 billion, of which $13.2 billion was attributed to sales to businesses, a 22% increase. Revenue from sales to consumers increased by 7% to $1.8 billion, and operating income increased to $1.1 billion.
Being in the commercial PC business offers Dell a dose of business cycle risk mitigation, as companies reinvest in new PCs. Should the growth in AI servers stabilize, the PC cycle could boost revenues.
Guidance Has Been Reset Sharply Higher
Dell increased its full-year FY2027 revenue and non-GAAP EPS guidance to $192 billion and $25.50, respectively.
The Company expects revenue of $49 billion and non-GAAP EPS of $6.50 in the current quarter, representing 81% and 151% growth, respectively, from the prior year quarter.
Although it appears that Dell continues to sign large deals, I think the focus should be on the margins at which Dell converts the order backlog, which is currently $95 billion.
Working Capital Is the Main Fundamental Risk
During Q2, Dell’s cash flow from operations was $2.2 billion, and $6.3 billion in the first half of the year. However, cash flow from operations is not enough to evaluate Dell’s financial health because the company is using cash to buy AI hardware.
Working capital is the form of risk I am focusing on. Dell has to finance inventory of AI hardware before getting paid from customers. As long as Dell can collect from customers before the inventory of AI hardware turns stale, the business is financially healthy. However, if inventory turns stale and customers stop purchasing AI hardware, cash can quickly burn.
S&P 100 Inclusion Adds a Fresh Catalyst
As announced on September 4, Dell will join the S&P 100, replacing Honeywell Aerospace. Changes to tracked indices can require index-tracking funds to rebalance toward newly added shares.
Dell's quarter was strong. The company returned a record $4.3 billion to shareholders and declared another quarterly dividend of $0.63 per share.
Finally, Dell is trading at approximately 20 times forward earnings. Historically, this would be an expensive multiple for a hardware company. However, the current multiple looks warranted, given the company's strong recent growth.
Dell Technical Analysis: DELL Tests Rising Channel Support as $559.12 Becomes Critical
This week Dell closed at $568.06, from a high of $595.51 on Friday. This price move is near the chart level of $569.00. Because of this, the analysis on the 1 hour time frame still is applicable.
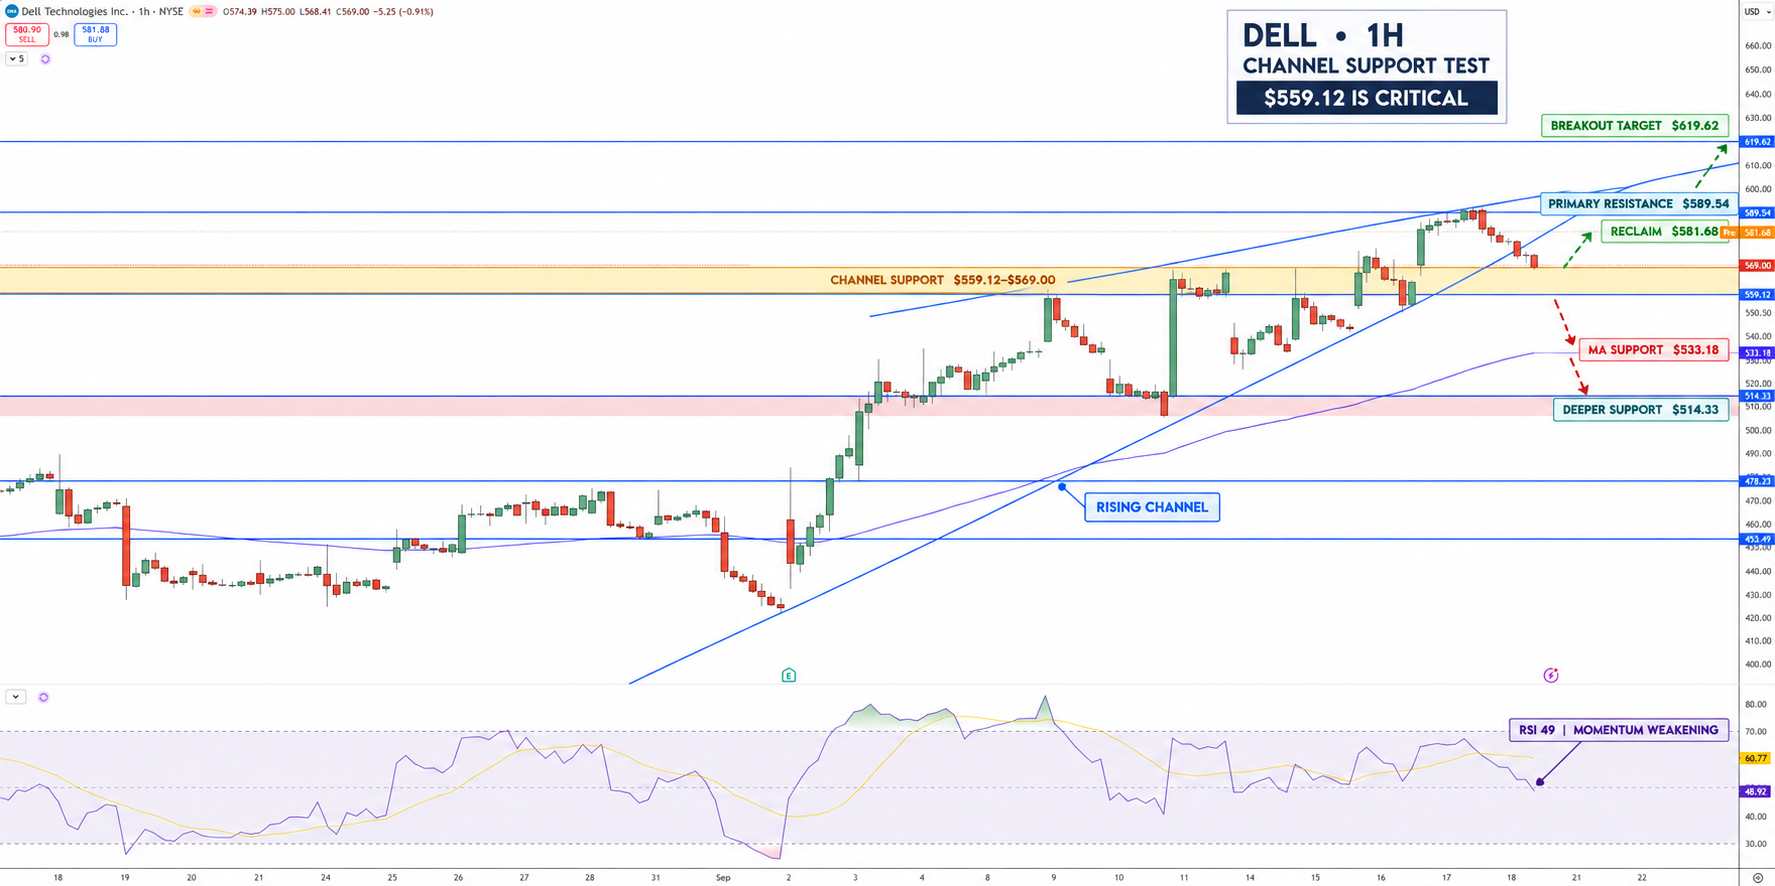
Dell Price Chart - Source: Tradingview
Price recently dropped to the rising support channel, making $559.12 to $569.00 crucial support. Currently, the RSI is at 49, with the signal line at 61.
A break below the rising support channel and $559.12 would possibly take Dell to the moving average at $533.18. The $514.33 level would be the next major support level.
Bulls would first want to see price rise above $581.68 and $589.54. If price were to break above $589.54 and close there, then the next major level in resistance would come at $619.62. Until $559.12 is broken, my outlook on Dell is bullish.
Key Levels
• Latest close: $568.06
• Important Support Levels: $559.12, $533.18, $514.33
• Important Resistance Levels: $581.68 to $589.54
• RSI: 49 (Neutral)
• Breakout Target: $619.62
Why is Dell stock in focus now?
For one reason or another, Dell has been generating a lot of buzz lately. Reasons may include hitting $47 billion in revenue for Q2, orders worth $60.9 billion for AI systems, $95 billion in backlog, increase in revenue guidance to $192 billion for FY2027, and lastly, gettings a spot on S&P 100.
What level confirms a stronger DELL recovery?
For the bull trend to continue, we can expect support around the $559.12 mark. A break above the trendline and $589.54 would bring a new bullish target around $619.62.
Bottom Line
Dell is looking great from a fundamental perspective. There are many catalysts in place including AI orders, order backlog, ISG growth and PC demand, and positive guidance. The biggest risk may come from margins.
Due to component availability constraints and focus on AI systems, the order backlog may not be fulfilled, therefore, Dell may not realize the expected profits and cash flows.
In a bull scenario, Dell looks pretty good with $559.12 as a strong support level. A possible bear scenario would place Dell at $533.18.
Recommended Articles


