




Taiwan Semiconductor Manufacturing's Foundry Market Share Is a Massive Moat Nobody Talks About
Key Points
TSMC makes chips for nearly every leading big tech firm.
Analysts expect strong growth from the company next year.
- 10 stocks we like better than Taiwan Semiconductor Manufacturing ›
Taiwan Semiconductor Manufacturing (NYSE: TSM) is well known for having a massive market share in the chip manufacturing world. It partners with nearly every artificial intelligence (AI) computing company and also with non-AI computing companies: Apple is historically its largest client (although that could shift this year).
The reality is that TSMC has built an unassailable moat, and that gives it protection against losing its competitive advantage.
Missed AI’s "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our analysts, we’re only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
A moat is one of the investment characteristics that investing legends like Warren Buffett have advised investors to seek. I think TSMC's moat comes from its sheer size, and it has locked several clients into using its services as a result.

Image source: Taiwan Semiconductor Manufacturing Company.
TSMC's moat is wide
The reality is that demand for logic chips, the type of chips TSMC produces, has never been higher. The AI build-out created a brand-new demand wave for chips. During the second quarter, 66% of TSMC's revenue came from its high-powered computing segment, which encompasses AI demand. Prior to the AI build-out, its largest segment was smartphones. This massive increase in AI chips has caused TSMC's business to swell, and it's unlikely to give up any of those gains.
The reality is that no competitor can take TSMC's market share because no competitor has the capacity.
According to industry analyst company TrendForce, global chip foundry revenue was more than $50 billion in the second quarter. TSMC owned about 72.5% of total revenue during the quarter. The second-place company owned 5.9% of the market, so it's pretty obvious that TSMC is the largest player in this space by far.
While TSMC could lose some market share, it's going to be nearly impossible for other companies to steal a lot. The reason is the massive cost required to build enough production capacity to break down the size advantage that TSMC has created for itself.
This makes TSMC a fantastic stock pick, and fortunately for investors, it's still trading at the lower end of its recent valuation ranges.
TSMC's stock looks like a great buy at today's prices
The AI build-out has been going on for a few years, which gives investors some historical data to work with. Near the end of 2024 and 2025, TSMC's stock topped out at about 29 times forward earnings. Now it trades at about 25.4 times forward earnings.
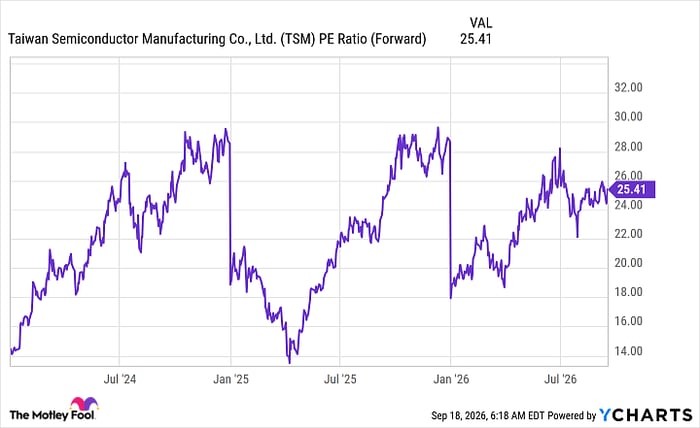
TSM PE Ratio (Forward) data by YCharts
If TSMC could rise to 29 times forward earnings before the year is over, that would provide about 14% upside. That's a great return in a very short time and gives investors a reason to buy the stock right now. Next year should also be a strong year, as Wall Street analysts are forecasting 35% revenue growth.
With TSMC trading at a reasonable price range now and 35% growth possible for next year, it should easily outperform the market from now until the end of 2027. The AI build-out not expected by many analysts to slow until the end of the decade. That leaves several more strong years for TSMC as an investment.
Investing in TSMC is one of the best ways to take advantage of the massive AI build-out, as it isn't a bet on any one computing unit. Instead, it's a bet that we're going to need more advanced chips in greater quantities, which seems highly likely. Given how much production capacity TSMC has right now, it's unlikely that any competitors will be able to steal a meaningful amount of its market share, giving the company an unassailable moat that protects its competitive advantage.
Should you buy stock in Taiwan Semiconductor Manufacturing right now?
Before you buy stock in Taiwan Semiconductor Manufacturing, consider this:
The Motley Fool Stock Advisor analyst team just identified what they believe are the 10 best stocks for investors to buy now… and Taiwan Semiconductor Manufacturing wasn’t one of them. The 10 stocks that made the cut could produce monster returns in the coming years.
Consider when Netflix made this list on December 17, 2004... if you invested $1,000 at the time of our recommendation, you’d have $387,158!* Or when Nvidia made this list on April 15, 2005... if you invested $1,000 at the time of our recommendation, you’d have $1,365,749!*
Now, it’s worth noting Stock Advisor’s total average return is 932% — a market-crushing outperformance compared to 211% for the S&P 500. Don't miss the latest top 10 list, available with Stock Advisor, and join an investing community built by individual investors for individual investors.
See the 10 stocks »
*Stock Advisor returns as of September 20, 2026.
Keithen Drury has positions in Taiwan Semiconductor Manufacturing. The Motley Fool has positions in and recommends Apple and Taiwan Semiconductor Manufacturing. The Motley Fool has a disclosure policy.
Recommended Articles


