


A Once-in-a-Decade Opportunity: 1 Super Growth Stock Down 58% to Buy and Hold for a Decade
Key Points
Dutch Bros is reporting high growth, but its outlook disappointed investors in the third quarter.
It's planning to open 250 stores next year to reach its goal of 2,029 stores by 2029.
Dutch Bros stock carries a premium price tag, making it susceptible to a drop if there's a misstep.
- 10 stocks we like better than Dutch Bros ›
Artificial intelligence (AI) stocks were rising again as investors take in the results of the election, sending the S&P 500 higher.
But that good news didn't extend across the board. Coffee shop chain Dutch Bros (NYSE: BROS) released its third-quarter earnings on Wednesday, and its stock plummeted. It's now a crushing 58% off its high.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
However, things could change rapidly for this growth stock, and if you buy it today and hold it for a decade, I have a high conviction that you'll be well-rewarded. Here's why.
Making coffee fun again
Dutch Bros has a casual, down-to-earth vibe with fun, exclusive beverages that differentiate it from other chains. In fact, many of its drinks don't have coffee at all. About 90% of what it sells is cold, and it offers energy drinks and many flavor combinations.
The other parts of the model include a mostly drive-thru store portfolio, a robust digital membership program, and a new food menu.
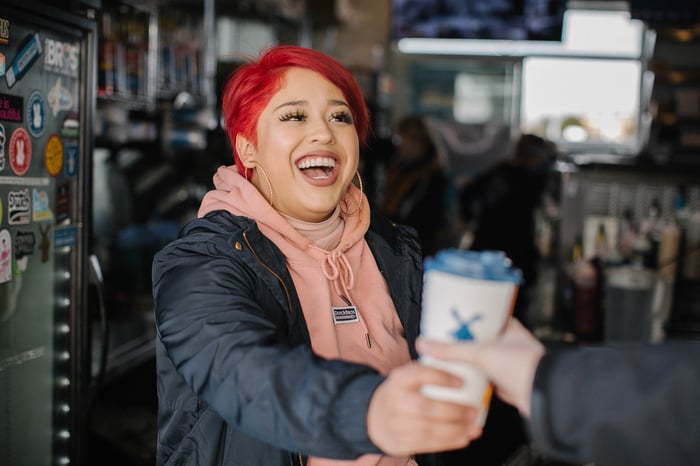
Image source: Dutch Bros.
It's attracting loyal fans wherever it has already opened, which is in 28 states. It opened 48 new shops in the quarter to reach 1,273, and it has 1328 locations as of today.
In Q3, revenue increased 30% year over year, and same-shop sales increased 4.4%. The company has a franchise model, but it has switched to opening only company-owned stores. It has rigorous standardization across its fleet, and company-owned stores increased 5.5%. Net income increased from $27.3 million to $37.2 million.
There were several reasons why the market didn't like the report. First, it's a slowdown from previous quarters. And worse, the company lowered its full-year outlook across metrics. Here are the prior and new numbers for the outlook:
| Metric | Prior | New |
|---|---|---|
| Sales | $2.13 billion | $2.1 billion |
| Same-shop sales growth | 5% to 6% | At least 5% |
| Adjusted EBITDA | $385 million to $390 million | $380 million |
| Capital expenditures (capex) | $350 million to $350 million | $370 to $390 million |
Data source: Dutch Bros quarterly reports.
A major expansion opportunity
The company also provided an update that it will meet its goal of opening 185 new stores this year despite a previous bid for a 65-store chain falling through, and it plans to accelerate openings to 250 stores next year.
That wasn't a good enough update to prevent the stock from plunging, but Dutch Bros has serious expansion plans. It expects to have 2,029 stores by 2029, and it reaffirmed that target. It plans to have 7,000 stores over several years, and in a decade from now, that goal is likely to be even bigger.
New stores are leading to scale as the company enters new markets, grows its brand, and gains new customers. Third-party research shows it outperforming industry standards across various guest experience metrics, and it gets the highest customer service ratings.
Dutch Bros has a deliberate real estate strategy, part of which involves opening several stores in one area to build density. That bolsters its presence and brand, and having several stores within customers' reach helps it become part of their everyday routine. That can, however, lead to lower same-store sales growth, since new stores take share from old stores.
Priced for perfection
Dutch Bros stock trades at a premium, which is why it's been falling. When it's priced for perfection, it can't handle any missteps even if its results were strong. At the current price, Dutch Bros stock trades at 28 times next year's earnings, which I still wouldn't call a bargain.
However, it's an attractive price for a stock with as much potential as Dutch Bros. There could be lots of volatility over the next decade, which is the nature of growth stocks. This looks like a great entry point for risk-tolerant investors who can ignore the noise and hold for many years.
Should you buy stock in Dutch Bros right now?
Before you buy stock in Dutch Bros, consider this:
The Motley Fool Stock Advisor analyst team just identified what they believe are the 10 best stocks for investors to buy now… and Dutch Bros wasn’t one of them. The 10 stocks that made the cut could produce monster returns in the coming years.
Consider when Netflix made this list on December 17, 2004... if you invested $1,000 at the time of our recommendation, you’d have $341,966!* Or when Nvidia made this list on April 15, 2005... if you invested $1,000 at the time of our recommendation, you’d have $1,146,819!*
Now, it’s worth noting Stock Advisor’s total average return is 852% — a market-crushing outperformance compared to 203% for the S&P 500. Don't miss the latest top 10 list, available with Stock Advisor, and join an investing community built by individual investors for individual investors.
See the 10 stocks »
*Stock Advisor returns as of November 8, 2026.
Jennifer Saibil has positions in Dutch Bros. The Motley Fool has positions in and recommends Dutch Bros. The Motley Fool has a disclosure policy.
Recommended Articles


