


Microsoft and Oracle Can't Cool AI Data Centers Without This Growth Stock. Here's Why It Could Soar.
Key Points
Vertiv sells critical data center equipment, including cooling systems, which explains why the company's growth rate is picking up.
Vertiv's order inflow is increasing at a healthy pace, which should ensure that its impressive growth continues over the long run.
Vertiv stock could nearly double from current levels, driven by its solid earnings growth and attractive valuation.
- 10 stocks we like better than Vertiv ›
The aggressive artificial intelligence (AI) data center build-out isn't slowing down, and that's not surprising, as major hyperscalers and cloud infrastructure providers have sizable contractual backlogs to fulfill.
As a result, it is easy to see why Microsoft (NASDAQ: MSFT) and Oracle (NYSE: ORCL) have been accelerating the build-out of data centers. We will take a closer look at the latest earnings reports of these tech giants before analyzing the financial performance and prospects of another key player in the AI infrastructure ecosystem that could win big from their massive investments.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Image source: Getty Images.
Microsoft and Oracle have sizable contractual backlogs, creating the need for more data center capacity
Microsoft reported a whopping $677 billion in commercial remaining performance obligation (RPO) in the first quarter of fiscal 2027, up by 73% from the year-ago period. Not surprisingly, Microsoft will accelerate capital spending to build more data center capacity. The company estimates more than $50 billion in capital expenditure in the current quarter, up from $45.2 billion in the previous one.
Similarly, Oracle has a massive RPO of $664 billion, with the figure increasing by $209 billion from the year-ago period. As a result, Oracle plans to increase its capital spending from $55.7 billion in fiscal 2026 to a range of $90-$95 billion in the current one. Several semiconductor companies will benefit from these data center investments.
However, cooling systems are one of the most critical aspects in AI data centers, apart from chips. That's because AI clusters powered by graphics processing units (GPUs) reportedly pack 8-10x more power than traditional data center racks. As a result, the demand for cooling systems in AI data centers is much higher.
Not surprisingly, the size of the global data center cooling market is expected to increase from $18 billion last year to $141 billion in 2036. Vertiv Holdings (NYSE: VRT) is already capitalizing on this lucrative growth opportunity, as evident from the company's latest results. Let's see why this AI stock can make investors significantly richer over the long run.
Vertiv's mission-critical data center products have led to solid growth acceleration
Vertiv provides multiple data center-related solutions, including power systems, thermal management and liquid cooling systems, and also builds server racks. The company sells multiple cooling systems for server racks and server rooms, as well as outdoor cooling systems.
The key data center products that Vertiv sells explain why the company's revenue in the third quarter of 2026 shot up 61% year over year to $4.3 billion. What's more, non-GAAP earnings per share increased by 78% year over year to $2.21. More importantly, Vertiv's organic orders increased by 100% from the year-ago period, which explains why it has increased its 2026 revenue guidance by $650 million to $14.65 billion. That implies a 43% increase over last year.
Vertiv expects its 2026 adjusted earnings per share to jump by 70% to $7.15, suggesting that the stronger mix of AI data center products is proving accretive to its margins. What's worth noting is that Vertiv is on track to double the production capacity of its chilled water cooling systems by the end of the year, suggesting that it will be in a better position to capture the fast-growing data center cooling space.
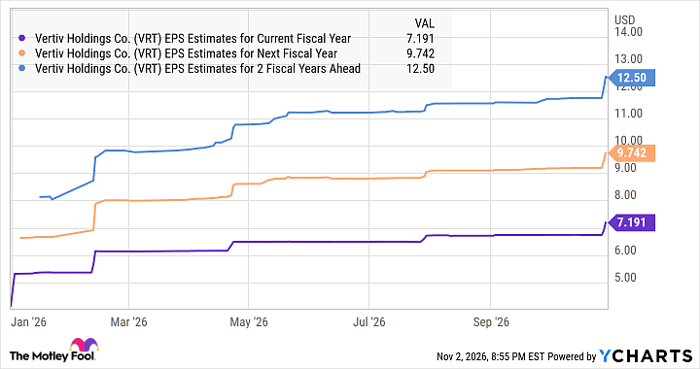
As such, Vertiv should be able to sustain the healthy earnings growth it has been clocking over the long run, and that's precisely what analysts expect.
Data by YCharts
What's more, Vertiv is trading at just 25 times forward earnings even after clocking such terrific earnings growth. The tech-focused Nasdaq Composite index, for comparison, has a price-to-earnings (P/E) ratio of almost 40. Vertiv should ideally command a premium valuation owing to its strong earnings growth and sunny prospects.
Assuming it trades at even 35 times earnings at the end of 2028 and its earnings per share reach $12.50, as seen in the previous chart, its stock price could hit $437. That implies 95% upside in just over two years, though I won't be surprised to see bigger gains in Vertiv stock, as it is capable of clocking stronger earnings growth, which could lead the market to reward it with a premium multiple.
Should you buy stock in Vertiv right now?
Before you buy stock in Vertiv, consider this:
The Motley Fool Stock Advisor analyst team just identified what they believe are the 10 best stocks for investors to buy now… and Vertiv wasn’t one of them. The 10 stocks that made the cut could produce monster returns in the coming years.
Consider when Netflix made this list on December 17, 2004... if you invested $1,000 at the time of our recommendation, you’d have $336,195!* Or when Nvidia made this list on April 15, 2005... if you invested $1,000 at the time of our recommendation, you’d have $1,241,567!*
Now, it’s worth noting Stock Advisor’s total average return is 875% — a market-crushing outperformance compared to 208% for the S&P 500. Don't miss the latest top 10 list, available with Stock Advisor, and join an investing community built by individual investors for individual investors.
See the 10 stocks »
*Stock Advisor returns as of November 3, 2026.
Harsh Chauhan has no position in any of the stocks mentioned. The Motley Fool has positions in and recommends Microsoft, Oracle, and Vertiv. The Motley Fool has a disclosure policy.
Recommended Articles


