


Apple Stock Price Forecast: Maintains Uptrend Ahead of Earnings, Better-Than-Expected Results Could Hit Record $350
TradingKey - Apple (AAPL) will report its fiscal fourth-quarter 2026 financial results after the U.S. market close on November 2. Ahead of the earnings release, the company's stock was trading at $344.63, just about 1.6% shy of its all-time high of $350. Despite notable volatility during the latest trading session, the stock remains above its 20-day and 60-day moving averages, leaving its medium-term upward trend intact.
The market expects Apple's fourth-quarter revenue to reach approximately $113.4 billion, up about 10.7% year-over-year, with earnings per share projected at $1.99, an increase of 7.6% year-over-year. The company has beaten market expectations for earnings per share in each of the past eight quarters. Therefore, investors are focusing not only on whether it can deliver another earnings beat, but also on whether revenue growth, product demand, and holiday shopping season guidance can support its current valuation.
The iPhone remains the core business driving earnings performance. Analysts estimate fourth-quarter iPhone revenue at around $56.6 billion, up roughly 15% year-over-year. Although growth in the global smartphone market has slowed, Apple has maintained a stable market share in the premium segment, with user upgrade demand continuing to support sales. However, the delayed launch of the base model iPhone 18 led to weaker shipment performance in September, which could limit further upside for hardware revenue beyond expectations.
The Services segment is a crucial source of profit growth for Apple. The market expects quarterly revenue for this division to reach approximately $31.7 billion, with a gross margin exceeding 75%, significantly higher than that of the hardware business. If the App Store, cloud services, subscriptions, and payment services continue to maintain double-digit growth, it will help cushion hardware sales volatility and support the company's overall profit margins.
Investors will also keep a close eye on supply chain and cost pressures. Apple previously projected total fourth-quarter revenue growth of 9% to 11%, but warned that supply constraints on advanced node chips could affect shipments of the iPhone, Mac, and iPad. Rising memory chip prices present another potential risk; if DRAM and NAND costs continue to climb, the company may need to adjust its product mix or raise selling prices to maintain profit margins.
Source: TradingView
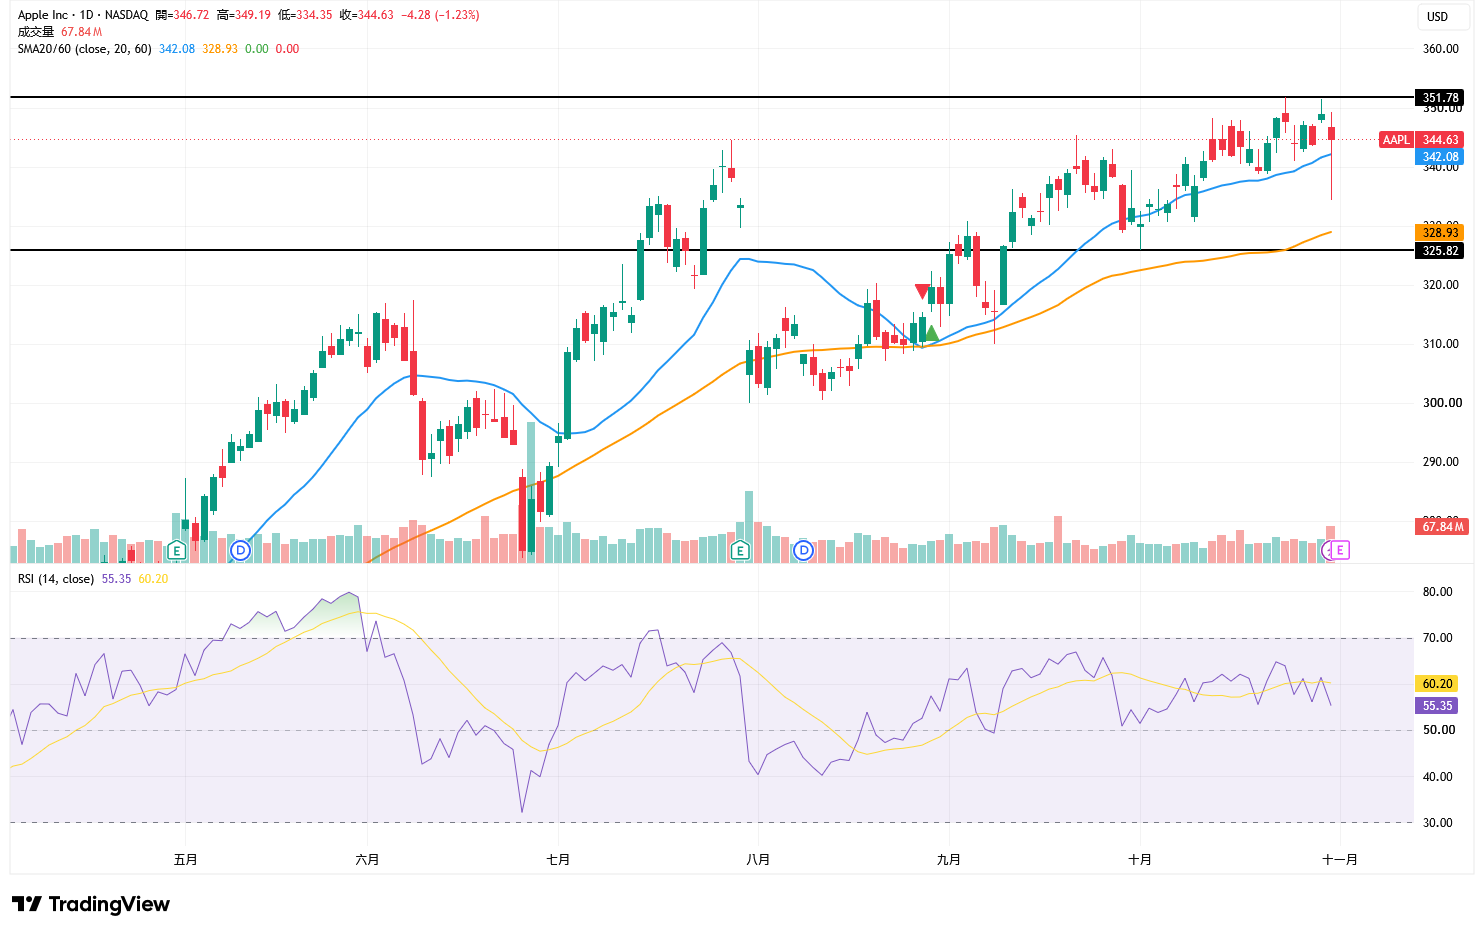
From a technical perspective, Apple's stock price currently stands at $344.63, remaining above its 20-day moving average of $342.08 and 60-day moving average of $328.93. Both moving averages continue to trend upward, indicating that the medium-term bullish structure remains intact. The 20-day moving average is the most critical short-term support level ahead of earnings; as long as the stock stays above $342, conditions remain favorable for another test of $350.
The 14-day RSI is around 55.35, remaining in neutral-to-bullish territory, but has fallen below its smoothed signal line of 60.20, pointing to a cooling in short-term upward momentum. Following the earnings announcement, if the stock breaks through $350 on heavy volume and holds above that level at the daily close, it would signal a continuation of the uptrend and open up new price potential. Moving from $344.63 to $350 requires a gain of only about 1.6%, which is lower than the ~4.25% earnings volatility implied by the options market. Therefore, if both results and guidance exceed expectations, reaching new record highs is viable.
Conversely, if earnings fail to meet high expectations or if holiday-quarter guidance comes in weak, Apple's stock price could first fall below $342 and retest near $335. Only if selling pressure causes a breakdown below the 60-day moving average of $328.93 would the medium-term bullish structure weaken significantly.
Recommended Articles


