


If Alphabet Does This on Oct. 28, the Stock Could Skyrocket
Key Points
Google Cloud's growth rate has jumped each quarter for the past year.
Alphabet's stock is reasonably valued heading into earnings.
- Motley Fool Issues Rare "Total Conviction" Buy Alert ›
Like many big tech companies, Alphabet (NASDAQ: GOOG) (NASDAQ: GOOGL) has had a lackluster year. It's only up about 7% for the year, but that figure was over 25% at the start of May. Alphabet has slowly sold off and is now losing to the S&P 500 (SNPINDEX: ^GSPC). However, I think that could be coming to an end.
Alphabet reports third-quarter results on Oct. 28, and there could be one piece of information in that report that causes its stock to skyrocket: Google Cloud revenue growth. Google Cloud is the fastest-growing of the three major cloud computing providers by far, and it has a big catalyst that could send its growth rate even higher in the coming months.
Missed AI’s "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our analysts, we’re only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
Image source: The Motley Fool.
Google Cloud has multiple factors in its favor
During the second quarter, Google Cloud's revenue growth reached 82%. Considering it was 63% in the first quarter and 48% in fourth-quarter 2025, this marks major acceleration for the platform. It's also helping the company to pull away from its peers, as Microsoft Azure reported 43% growth during its latest quarter and Amazon Web Services reported 37%. Google Cloud has long been the third-place competitor in terms of market share in the cloud computing industry, but if it keeps up that growth rate, it won't stay in third for much longer.
Cloud computing platforms are seeing impressive growth due to massive demand from major AI clients. AI workloads cannot be run without the help of cloud computing providers. With each workload being run costing some amount of money, as AI usage rises, so will the revenue of these platforms. That's why Alphabet made the decision to spend between $195 billion and $205 billion on capital expenditures this year, mostly going toward data centers. Prior-year investments appear to be paying off, which is why Google Cloud's revenue growth rate is accelerating.
However, generally, workload growth isn't the only way Alphabet is expanding Google Cloud's revenue.
One of the differentiating factors between Google Cloud and the competition is its custom-designed Tensor Processing Units (TPUs). TPUs are an alternative to graphics processing units (GPUs). When the workload is properly optimized, they can provide better performance from a cost standpoint than GPUs.
Originally, the only way to gain access to these impressive devices was via Google Cloud. However, Alphabet is starting to sell these computing units to certain clients as another way to generate revenue growth. While there are some sales affecting current results, Alphabet expects the bulk of this revenue to come in 2027, which could boost its cloud revenue growth even further.
We'll see what the quarter brings, but if previous trends are any indication, Google Cloud could report triple-digit revenue growth. That could send the market into a buying frenzy.
Alphabet's stock isn't expensively priced
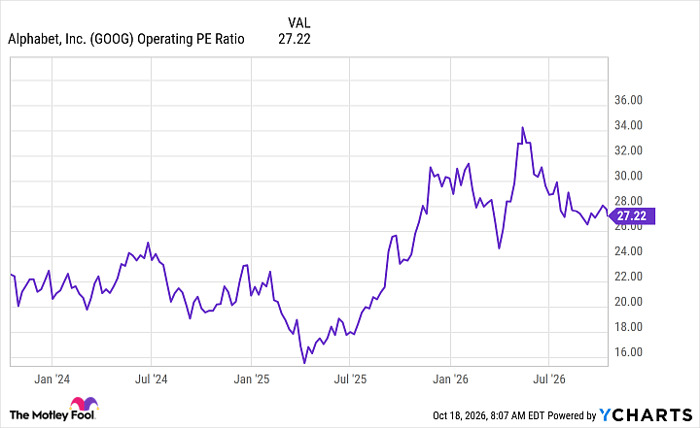
Alphabet's price-to-earnings (P/E) ratio is currently skewed by one-time effects from gains on investments. So I'll value the stock using operating earnings. From a historical standpoint, Alphabet's stock looks a bit pricey.
GOOG Operating PE Ratio data by YCharts.
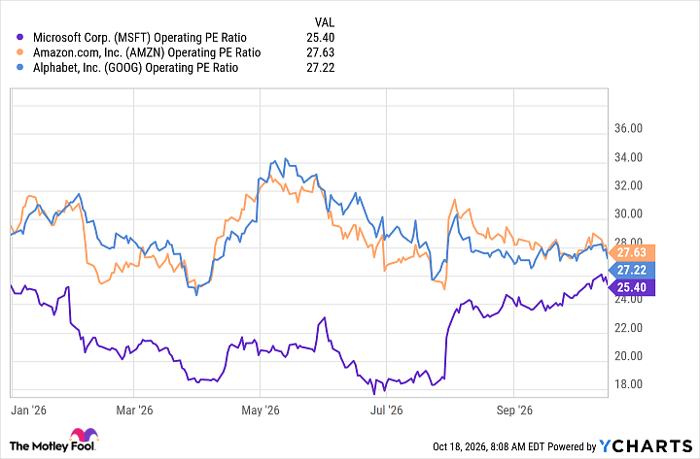
However, the market repriced the stock in 2025 as Alphabet emerged as an AI leader, rather than an AI laggard. Still, 27 times operating income is about where its peers also trade.
MSFT Operating PE Ratio data by YCharts.
Right now, Alphabet isn't an expensive stock, but I wouldn't consider it cheap either. It's fairly valued, which means that company results will drive stock price growth.
I think that Alphabet is well-positioned to deliver strong earnings in its report on Oct. 28, with particular strength stemming from Google Cloud. If Google Cloud can grow at a triple-digit rate (which I think it will), the stock price could skyrocket, making Alphabet a phenomenal stock to buy now.
Should you buy stock in Alphabet right now?
Before you buy stock in Alphabet, consider this:
The Motley Fool Stock Advisor analyst team just identified what they believe are the 10 best stocks for investors to buy now… and Alphabet wasn’t one of them. The 10 stocks that made the cut could produce monster returns in the coming years.
Consider when Netflix made this list on December 17, 2004... if you invested $1,000 at the time of our recommendation, you’d have $376,696!* Or when Nvidia made this list on April 15, 2005... if you invested $1,000 at the time of our recommendation, you’d have $1,333,920!*
Now, it’s worth noting Stock Advisor’s total average return is 925% — a market-crushing outperformance compared to 212% for the S&P 500. Don't miss the latest top 10 list, available with Stock Advisor, and join an investing community built by individual investors for individual investors.
See the 10 stocks »
*Stock Advisor returns as of October 21, 2026.
Keithen Drury has positions in Alphabet, Amazon, and Microsoft. The Motley Fool has positions in and recommends Alphabet, Amazon, and Microsoft. The Motley Fool has a disclosure policy.
Recommended Articles


