


Meta Platforms Is Up Nearly 25% in September. Does It Have Room to Rise Further?
Key Points
The launch of Muse was a huge reason for Meta Platforms' stock price gains.
Meta's stock still isn't terribly expensive on a forward price-to-earnings basis.
- 10 stocks we like better than Meta Platforms ›
Meta Platforms (NASDAQ: META) has had an incredible September. At its peak, it rose more than 30%, although it sold off in the last few days of the month. Still, those are impressive results for Meta, especially given how poor its performance earlier in 2026 was.
It took that strong month for Meta to finally sit in positive year-to-date territory, but was this rally deserved? Let's take a look at what propelled it, and if those tailwinds are enough to maintain its momentum.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Image source: The Motley Fool.
Meta's new product launch had the market buzzing
During September, Meta released a very important product: Muse -- a personal AI agent that can do all sorts of tasks for users. Muse can be tasked with multiple tasks and work in the background with user oversight before taking an action. This is the sort of thing the market has been waiting for Meta to release for a long time, and now that it's here, it's living up to expectations, judging by the market's reaction.
However, what investors will be curious about is how well Muse will do as an actual revenue source for the company. There have long been questions about how Meta will monetize its AI products, and as Muse is free to use, it doesn't address this problem.
However, there is a usage limit. If users find Muse a valuable enough tool that they want to make greater use of it than those limits allow, they'll need to upgrade to a paid subscription. Depending on how low Meta sets the usage limits and how useful the tool is, those subscriptions could become a massive new part of Meta's business, although it will be several quarters, at a minimum, before we can really gauge how it's being received and adopted.
Meta will likely make Muse a central talking point during its upcoming Q3 earnings report, which is expected in late October. After that, market sentiment may shift further regarding Meta stock. However, even after its major run-up, the stock isn't all that expensive.
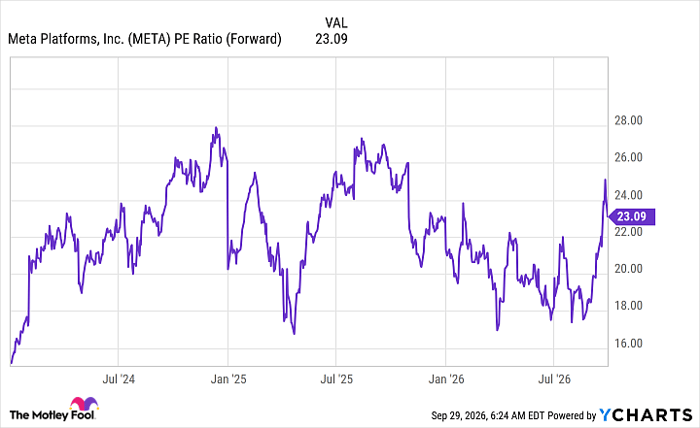
META PE Ratio (Forward) data by YCharts.
Entering September, Meta was trading at a pretty cheap 18 times forward earnings. Now, at 23 times forward earnings, it has reached a level most investors would expect a company of its caliber to trade at. However, it could still go higher, as it has in years past.
The market will need to know more about how Muse is adopted by consumers. If it continues to go well, it could help lift Meta's stock to new heights. If it doesn't, the market may send Meta back toward its recent valuation lows.
Should you buy stock in Meta Platforms right now?
Before you buy stock in Meta Platforms, consider this:
The Motley Fool Stock Advisor analyst team just identified what they believe are the 10 best stocks for investors to buy now… and Meta Platforms wasn’t one of them. The 10 stocks that made the cut could produce monster returns in the coming years.
Consider when Netflix made this list on December 17, 2004... if you invested $1,000 at the time of our recommendation, you’d have $373,352!* Or when Nvidia made this list on April 15, 2005... if you invested $1,000 at the time of our recommendation, you’d have $1,406,241!*
Now, it’s worth noting Stock Advisor’s total average return is 933% — a market-crushing outperformance compared to 212% for the S&P 500. Don't miss the latest top 10 list, available with Stock Advisor, and join an investing community built by individual investors for individual investors.
See the 10 stocks »
*Stock Advisor returns as of September 30, 2026.
Keithen Drury has positions in Meta Platforms. The Motley Fool has positions in and recommends Meta Platforms. The Motley Fool has a disclosure policy.
Recommended Articles


