


Prediction: Taiwan Semiconductor Manufacturing Will Hit a $3 Trillion Market Cap Before 2027 Is Over
Key Points
Taiwan Semiconductor's market cap would need to rise by about 30% to put it into the $3 trillion club.
Management is bullish on its prospects.
Taiwan Semiconductor trades at about 27 times forward earnings, a level typical for big tech stocks.
- 10 stocks we like better than Taiwan Semiconductor Manufacturing ›
Taiwan Semiconductor Manufacturing (NYSE: TSM) is a $2.3 trillion company today, but I think it's destined for a $3 trillion market cap by the end of next year. To meet that target would require the stock to rise by about 30% over the next 15 months. Given that the stock market has averaged annual returns of about 10% over the long term, that would be a solid outperformance, so if I'm right, that would make the stock well worth buying now.
How would Taiwan Semiconductor get there? Simple: It just needs to do exactly what it has told investors it will do.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »

Image source: Taiwan Semiconductor Manufacturing Company.
The road to $3 trillion is clear
Few companies are set to benefit more from the AI infrastructure build-out than Taiwan Semiconductor. It's a chip fabrication company that builds the chips that its customers design. Its clients include nearly every company that makes AI computing chips: Nvidia, Broadcom, and AMD headline the list. Furthermore, companies like Apple and Qualcomm utilize Taiwan Semiconductor to fabricate the chips that they design for smartphones and other devices.
Demand for AI chips is still off the charts, and Taiwan Semiconductor management believes that elevated demand will last through at least 2029 to 2030. As a result, it decided to invest another $100 billion in expanding its U.S. production facilities.
Next year, Wall Street analysts expect TSMC's revenue to grow by 35%. As long as Taiwan Semiconductor can convert that revenue growth into relatively proportional earnings growth, as it has in the past, its returns should be highly correlated to its growth rate, as its stock is reasonably valued.
Taiwan Semiconductor now trades at about 27 times forward earnings, a level typical for big tech stocks. So, it should be able to easily convert earnings growth directly into stock price growth.
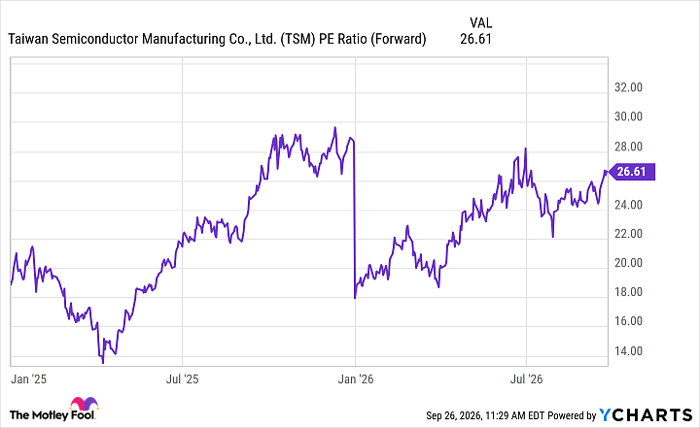
TSM PE Ratio (Forward) data by YCharts.
So while other AI stocks may have greater upside potential, Taiwan Semiconductor is a fairly safe bet to grow at a market-beating pace throughout 2027. It doesn't really matter which computing unit providers are gaining market share in 2027 and beyond. There's a high chance those winners will be contracting for foundry services with TSMC, which makes it a pretty universal AI investment.
Should you buy stock in Taiwan Semiconductor Manufacturing right now?
Before you buy stock in Taiwan Semiconductor Manufacturing, consider this:
The Motley Fool Stock Advisor analyst team just identified what they believe are the 10 best stocks for investors to buy now… and Taiwan Semiconductor Manufacturing wasn’t one of them. The 10 stocks that made the cut could produce monster returns in the coming years.
Consider when Netflix made this list on December 17, 2004... if you invested $1,000 at the time of our recommendation, you’d have $373,352!* Or when Nvidia made this list on April 15, 2005... if you invested $1,000 at the time of our recommendation, you’d have $1,406,241!*
Now, it’s worth noting Stock Advisor’s total average return is 933% — a market-crushing outperformance compared to 212% for the S&P 500. Don't miss the latest top 10 list, available with Stock Advisor, and join an investing community built by individual investors for individual investors.
See the 10 stocks »
*Stock Advisor returns as of September 29, 2026.
Keithen Drury has positions in Broadcom, Nvidia, and Taiwan Semiconductor Manufacturing. The Motley Fool has positions in and recommends Advanced Micro Devices, Apple, Broadcom, Nvidia, Qualcomm, and Taiwan Semiconductor Manufacturing. The Motley Fool has a disclosure policy.
Recommended Articles


