


TradingKey Wall Street Weekly Report:S&P 500 and Nasdaq Close Higher, AI Chip Stocks Lead, Treasury Yields Near 5.2% High, Oil Falls Below $98
Previous Week’s Market Review & Analysis
TradingKey - Macroeconomic Landscape: During the week from September 21, 2026 to September 27, 2026, the U.S. macroeconomic environment was driven by hawkish Federal Reserve monetary policy, volatile Treasury yields, and shifting energy dynamics. The Federal Reserve maintained a firm tightening bias following its federal funds rate increase to a target range of 3.75% to 4.00%, with officials signaling potential further rate hikes before year-end to restore price stability. The benchmark 10-year U.S. Treasury yield experienced elevated volatility, briefly reaching 5.225% before easing to close around 5.17%, while 2-year Treasury yields rose to 4.81%. Meanwhile, energy prices saw a temporary reprieve as West Texas Intermediate crude fell toward $92.70 per barrel and Brent crude dropped below $98 per barrel, easing immediate cost pressures. Geopolitical developments were anchored by high-level diplomatic talks, including the Trump-Xi summit, where the United States and China agreed to extend their trade truce by two months through January 10, avoiding an immediate escalation in bilateral tariffs.
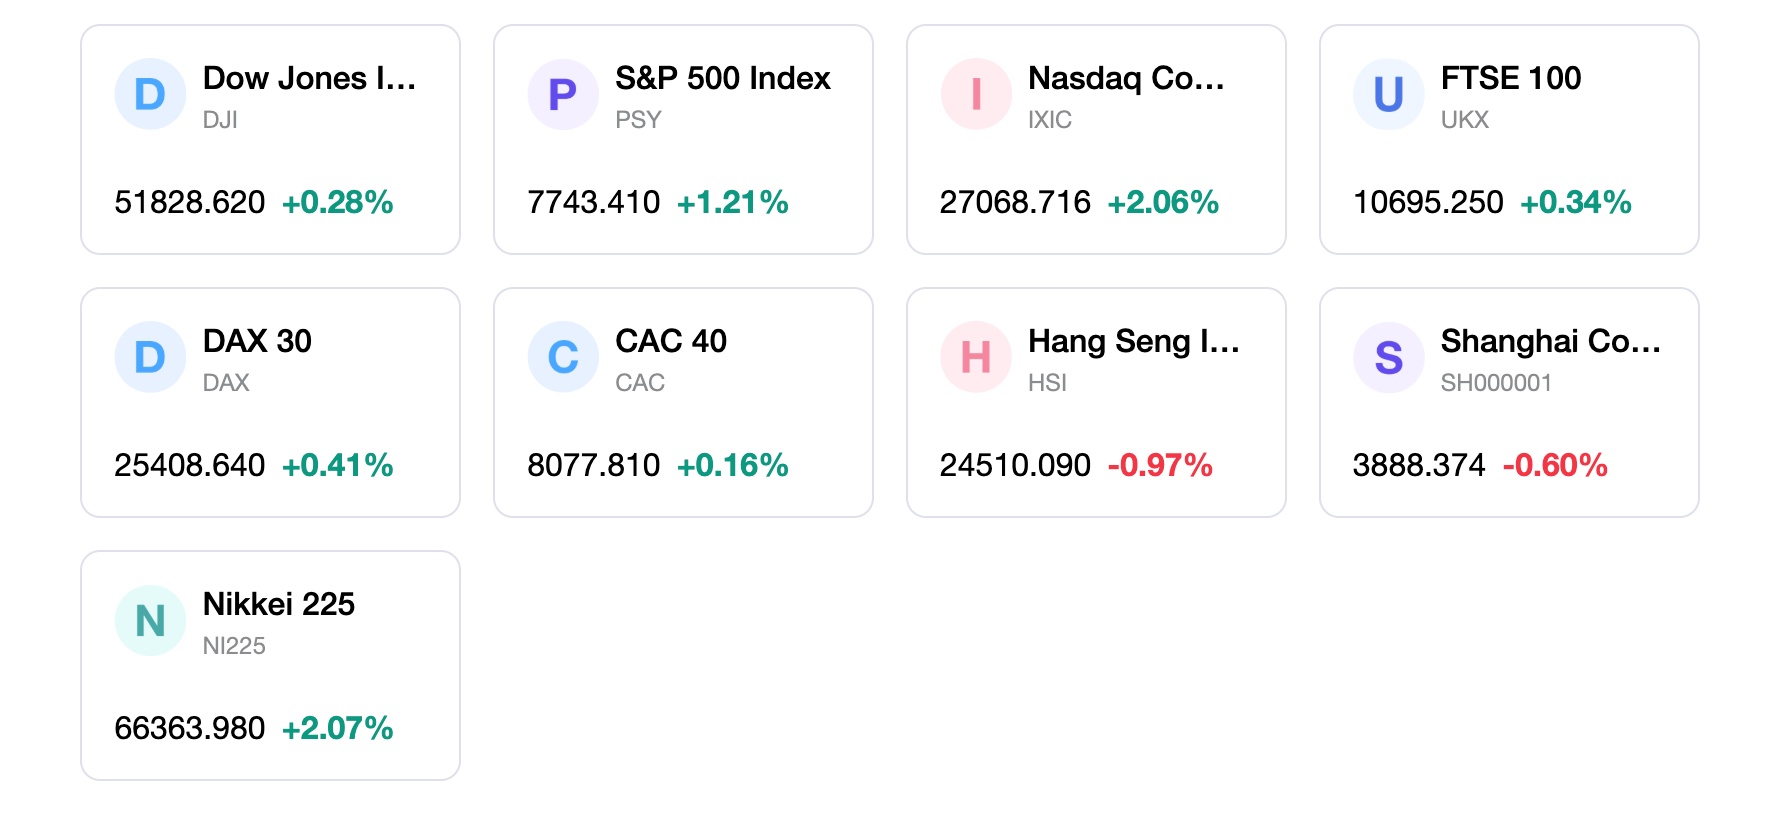
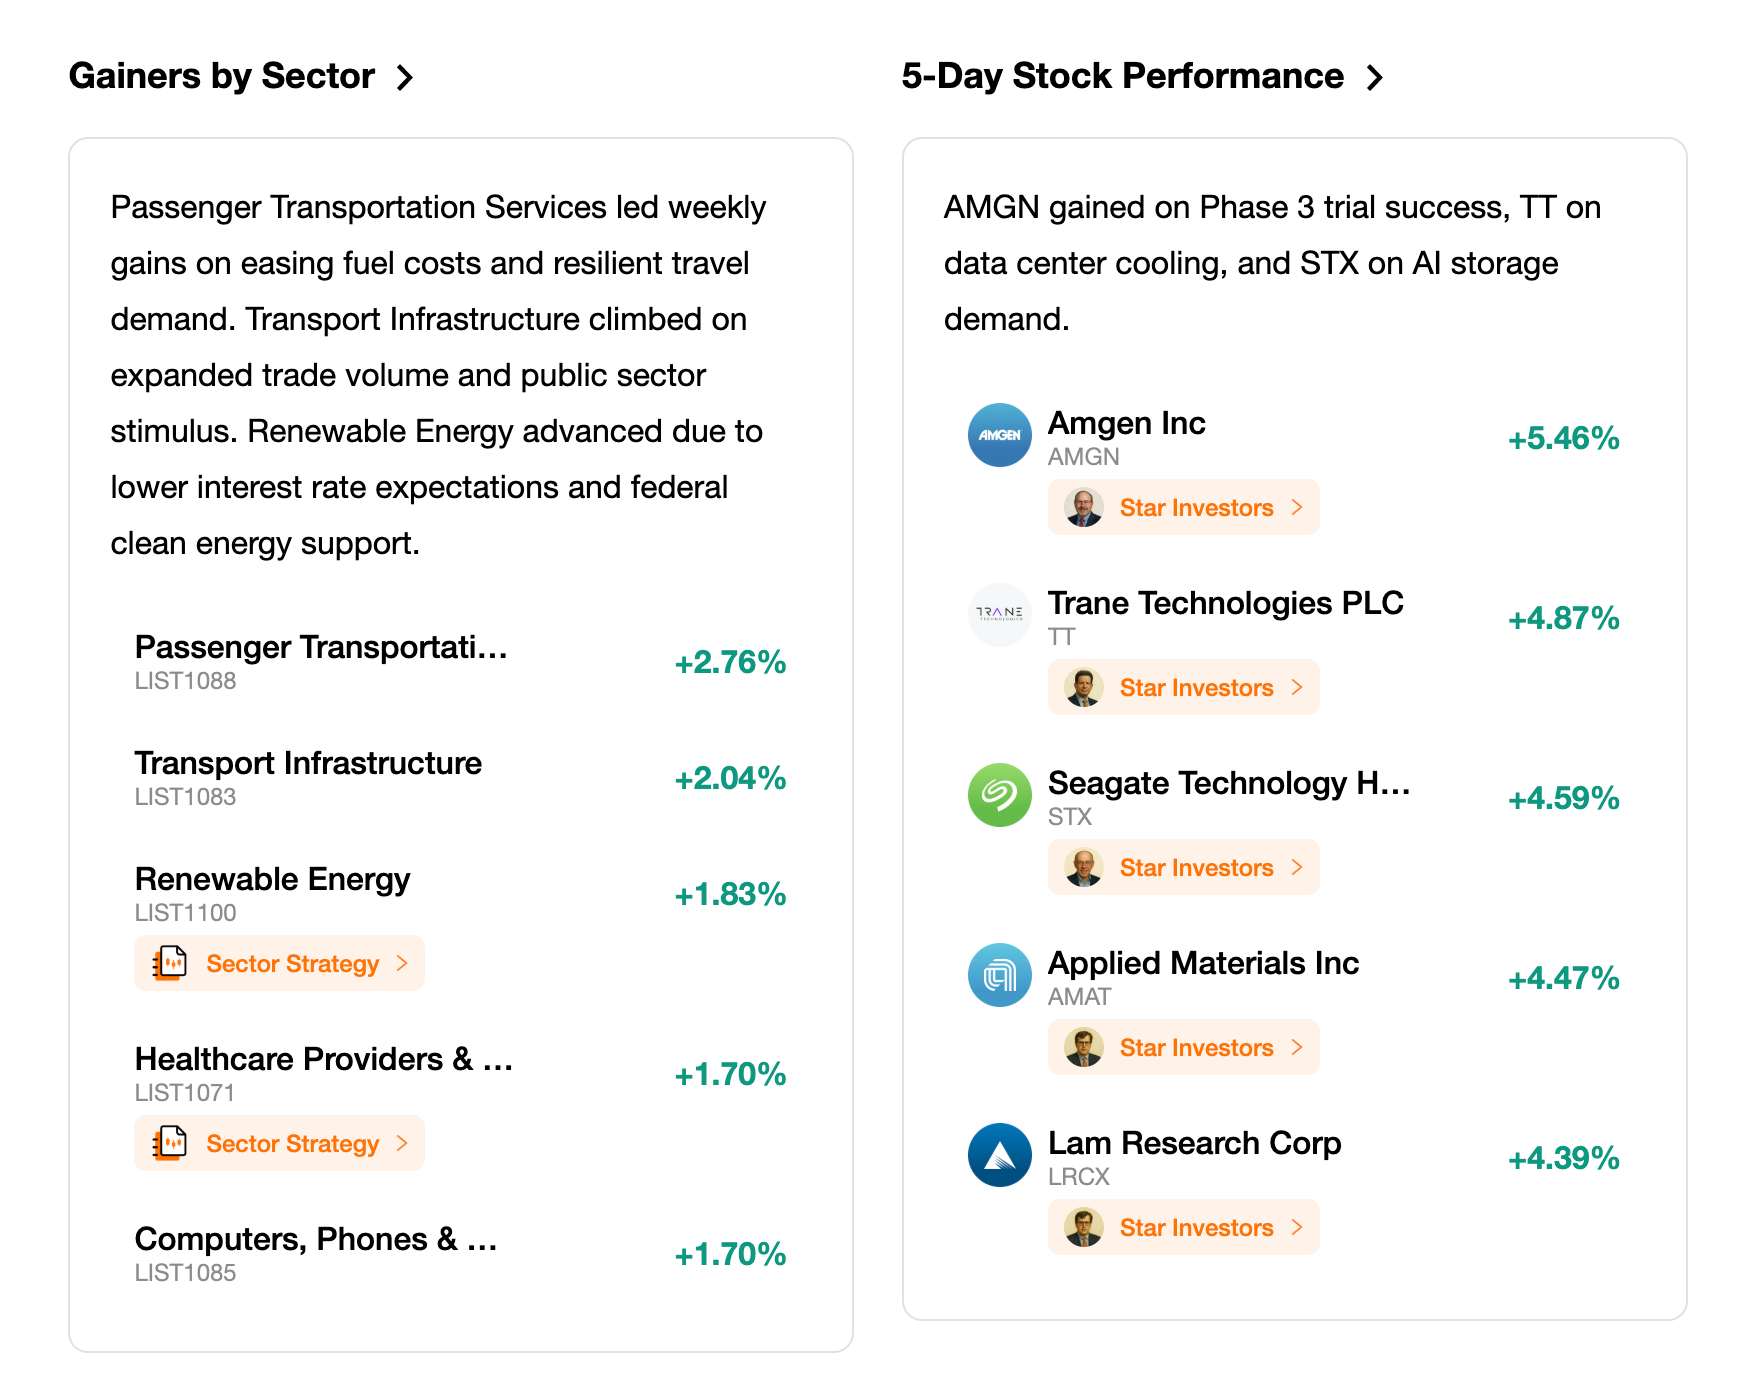
Market Performance Overview: Based on weekly K-line data for the trading week ending September 25, 2026, major U.S. equity indexes finished broadly higher, recovering from mid-week bond market pressure. The S&P 500 rose 1.21% for the week, while the tech-heavy Nasdaq Composite led gains with a 2.06% increase. The Dow Jones Industrial Average added 0.3%, recovering late in the week, whereas small-cap equities underperformed as the Russell 2000 fell 0.8%. Sector rotation reflected a sharp divergence between high-margin growth and rate-sensitive value; the technology sector jumped 3.1% and healthcare gained 1.57%, lifted by strong artificial intelligence momentum. In contrast, energy fell 3.07% as crude oil cooled, and utilities declined 3.04% under the weight of elevated long-term Treasury yields. Overall, growth stocks posted a strong 2.33% gain for the week, significantly outperforming value stocks, which slipped 0.35%.
Key Events Analysis: Market dynamics during the week were shaped by major corporate announcements and key economic releases. At Meta Connect 2026, Meta CEO Mark Zuckerberg unveiled new hardware and personal AI capabilities centered on its Muse AI agent, propelling Meta stock up nearly 13% for the week and driving renewed buying across the broader technology supply chain. In macroeconomic data releases, initial jobless claims remained tight at 197,000 for the week ending Sept. 19, demonstrating continued labor market stability despite elevated borrowing costs. The University of Michigan consumer sentiment index for September ticked down, while one-year inflation expectations rose to 4.6%, underscoring the delicate balance between resilient consumer demand and lingering inflation expectations. Furthermore, corporate earnings highlights included solid results in consumer staples and dollar store retail, reflecting budget-conscious consumer behavior amidst elevated living costs
Flows & Sentiment: Market sentiment showed notable dispersion during the week, navigating a tug-of-war between strong earnings execution in mega-cap technology and rising cost-of-capital constraints. The CBOE Volatility Index eased to close around 14.81 as Friday's pullback in energy prices and Treasury yields prompted short-covering and dip-buying. However, single-stock implied volatility and dispersion metrics across technology names remained elevated, reflecting increased options pricing for AI-related names and divergence among index components. Equity fund flows remained concentrated in large-cap growth and semiconductor funds, while outflows persisted in rate-sensitive utility and real estate funds. Investors maintained a selective stance, balancing the high risk-free rate offered by 5% Treasury yields against robust secular earnings momentum in artificial intelligence.
Overall Assessment: The current phase of the market cycle demonstrates structural divergence, where robust enterprise investments in artificial intelligence and corporate earnings growth are buffering equities against a bear-steepening yield curve and restrictive monetary policy. The market logic is centered on fundamental differentiation: cash-generative technology leaders with expanding profit margins continue to attract capital, whereas leveraged, rate-sensitive, and capital-intensive sectors face ongoing valuation compression from elevated Treasury yields. Broad market behavior reflects late-cycle resilience supported by private sector investment, though overall equity multiple expansion remains constrained by tight financial conditions.
Next Week’s key market drivers and Investment Outlook
Upcoming Events: Looking ahead to the week of September 28, 2026, financial markets face a critical slate of macroeconomic data releases and corporate events marking the close of the third quarter. Key economic indicators include the August Personal Income and Outlays report featuring the PCE price index, the third estimate of second-quarter real GDP, August JOLTS job openings, the ADP employment report, Chicago PMI, and the September Nonfarm Payrolls and unemployment rate report. Additional market-moving catalysts include OpenAI Developer Day on Tuesday, September 29, 2026, full disclosure of the US-China tariff reduction agreement details on September 28th, and upcoming quarterly corporate earnings reports.
Market Logic Projection: Macro conditions in the coming week are expected to be guided by how upcoming labor and PCE inflation data align with the Federal Reserve's hawkish policy path. If PCE inflation metrics confirm stabilizing price pressures alongside moderate payroll growth, Treasury yields may consolidate, providing a supportive backdrop for broader equity participation. Conversely, any upside surprises in core inflation could reignite fears of further Fed rate hikes, pushing Treasury yields back toward multi-year highs and triggering multiple compression across growth equities. On a micro fundamental level, capital spending announcements and developer updates surrounding AI infrastructure are projected to remain the primary driver of earnings revisions and sector dispersion.
Strategy & Allocation Recommendations: Portfolio strategy should maintain a disciplined approach, prioritizing quality growth and high-margin balance sheets that can withstand elevated cost of capital. Investors are advised to maintain an overweight allocation in technology, communication services, and healthcare sectors, where strong organic revenue growth and expanding operating margins provide fundamental insulation. Neutral positioning is recommended for financials and industrial cyclicals, while an underweight posture remains prudent for high-leverage small caps, utilities, and real estate. Representative equity ideas focus on dominant semiconductor enablers, cloud software hyperscalers, and cash-flow-generative consumer tech platforms capitalizing on AI monetization.
Risk Alerts: Investors should closely monitor several key market risks in the near term. A potential resurgence in crude oil and refined fuel prices stemming from persistent geopolitical disruptions in the Middle East poses a threat to headline inflation and consumer confidence. A sharp re-acceleration in long-term U.S. Treasury yields above 5.2% represents a significant risk to equity valuations, potentially triggering broader asset liquidations across risk assets. Additionally, potential friction surrounding the implementation of US-China trade agreements and unexpected weakness in upcoming labor market indicators could introduce downside volatility to global equity markets.
Markets Weekly
5-Day Index Performance
Recommended Articles


