


Arm Holdings Stock Surges 8.6% as AGI CPU Demand Puts $270.39 Breakout in Focus
ARM enters September 18 with a September 17 close of $264.90, up 8.57% from the close on the 16th. It peaked at $267.00 during the session. The move was due to positive comments on visibility of Arm’s AGI data center CPU sales by Arm’s CEO, Rene Haas, on the 16th. Management has become more confident it can secure enough supply to meet roughly $2 billion of customer demand as ARM’s CPU supply becomes available. ARM’s stock also broke out of the $251.63 to $253.42 area and is currently facing resistance at $269.66 to $270.39.
AGI CPU Is Changing Arm’s Business Model
AGI is artificial general intelligence. In Arm’s case, it is a major shift in Arm’s business model and focuses on the design and creation of CPUs. Historically, Arm made the majority of its revenue from licensing CPU designs to customers and chip makers and charging a royalty for each unit sold. With the introduction of AGI CPUs, Arm is shifting to producing chips for end customers and collecting revenue for each AI chip sold.
Customer interest in Arm’s AGI CPU has been strong and is projected to be in the billions of dollars. Initial product has already been delivered to multiple customers, with customer demand spanning fiscal 2027 and fiscal 2028. In July 2026, Arm disclosed that it had secured enough manufacturing capacity to support the $1 billion opportunity across fiscal 2027 and fiscal 2028. Recent comments suggest Arm is targeting the larger $2 billion opportunity. It is worth noting that publicly disclosed comments do not mean that revenue has been recognized.
Core Royalty Business Is Still Growing Strongly
In the first quarter of Arm's fiscal year 2027, revenue grew 22% to a record high of $1.29 billion. Of which, royalty revenue and licensing revenue, respectively, increased by 22% to $715 million and by 23% to $574 million. Consequently, Arm reported a non-GAAP operating income of $531 million and an adjusted operating margin of 41.2%.
The growth of the Arm business outside of data center service is impressive. However, growth within the data center services business is also noteworthy. According to Arm, data center-related royalties more than doubled in the first quarter. As a result, Arm is likely to continue to have a positive business outlook.
As Arm states, its technology is increasingly used to build data center and AI infrastructure. For example, Arm-based CPUs are used in Nvidia's Vera and cloud infrastructure AI and data center systems based on AWS Graviton.
Neoverse CSS N4 Expands Arm’s Value Per System
Arm announced the Neoverse CSS N4 on September 8. CSS stands for compute subsystem. CSS allows Arm to integrate more of the CPU into a single product and, hence, command a higher royalty fee per chip.
The trade-off for CSS is that the customer does not have the design flexibility that they get with a block-based design. A block based design gives the customer the flexibility to add as many cores as they want, though at the cost of longer time to market.
Arm's recent strategy has been to integrate more of the value chain and enmesh their customers more tightly. They have accomplished this by adding more layers to their monetization strategy. Neoverse allows Arm to charge more for a complete design and integration, while individual IP licensing allows customers to choose from different licensing models based on their needs.
Smartphones Remain the Main Near-Term Soft Spot
TradingKey - The smartphone business remains a large source of Arm’s royalty revenue. Arm expects smartphone royalty earnings to decline in Q2, as memory shortages and higher component costs continue to pressure handset production and market demand. Even with these shortages and component cost increases, Arm expects handset production to be low.
Arm's recent design innovations and Compute Subsystems enable Arm to increase royalty earnings per unit sold even if total unit sales remain low.
Q2 Guidance Remains Strong
For Q2 of 2027, Arm expects revenue of $1.38 billion, plus or minus $50 million, and adjusted EPS of $0.47, plus or minus $0.04. Although these numbers were ahead of analysts’ expectations and were an increase from the previous quarter, they remain guidance rather than reported results.
The results from the tentatively scheduled Nov. 4th report will probably determine Arm's stock price. The focus of the report will probably be data center growth, smartphone and other device royalty earnings, and how many of AGI's CPU orders are fulfilled.
Valuation Is the Main Risk
Although Arm Holdings’ business is strong, the stock currently reflects a large measure of success. The market is pricing Arm’s future achievements.
As of the time of writing, Arm is valued at $283 billion, at an approximate price of $264.90 per share. By this valuation, the market anticipates Arm’s future revenue and earnings. Arm trades at approximately 100 times forward earnings.
Arm needs to continually execute. There are a number of risks that are beyond Arm’s control. Some of these risks could negatively impact Arm’s earnings and revenue. A slowdown in Arm’s licensing business could cause investors to revise their expectations for Arm’s stock. This could also occur in the event that Arm experiences a supply constraint.
However, there are numerous positive factors that could impact Arm’s business in a meaningful way. Arm is in a better position than in the past to capture value because of the positive impact of Arm’s data center business and Arm’s CPU business.
Arm Holdings Technical Analysis: $270.39 Is the Breakout Trigger
ARM finished September 17th at $264.90, up significantly from the prior day’s $243.98 close. ARM recovered to and above the $251.63 to $253.42 zone, which now provides support. For the time being, the bullish bias in ARM is intact.
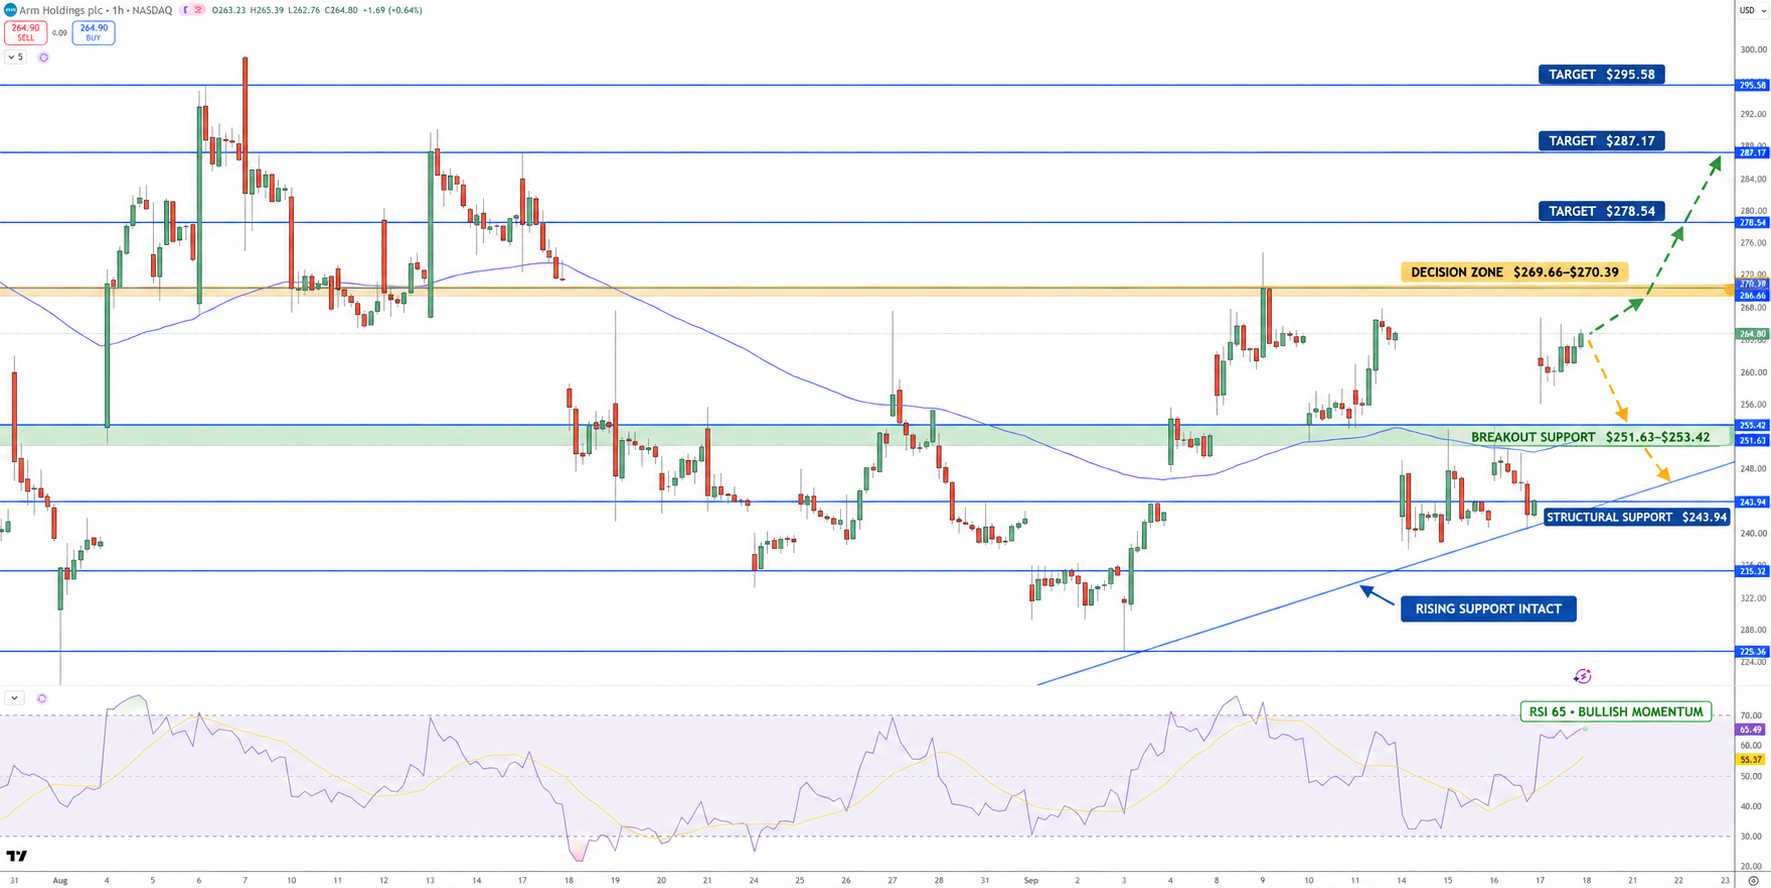
Arm Holdings Stock Price Chart - Source: Tradingview
Arm’s RSI of 65 does not yet indicate an overbought condition, but is supported by its signal line at 55, and therefore, remains constructive.
Should the recent uptrend continue, higher prices should be taken toward the $278.54 area. Further, the $287.17 and $295.58 levels may also be tested in the longer-term outlook.
If theARM uptrend is to remain in effect, support at the $251.63 to $253.42 zone must hold. If ARM breaks below this zone, support would shift to the $243.94 area.
· Current Support: $251.63 to $253.42
· Current Resistance: $269.66 to $270.39
· First Resistance: $278.54
· Second Resistance: $287.17
· Third Resistance: $295.58
· RSI: 65
Why is Arm Holdings stock in focus now?
ARM is currently in focus because on September 16th, CEO Rene Haas told CNBC’s Jim Cramer that ARM was in a strong position to meet roughly $2 billion in customer demand for its AGI CPU across fiscal 2027 and fiscal 2028.
What level confirms further ARM upside?
Arm’s stock will likely test the upside when it closes above 270.39. Upward movements may test the resistance at 278.54, and 287.17 and 295.58 may also be tested if 278.54 is broken. Breaking below 251.63 would mean that the recent bullish trend is invalid.
Bottom Line
Arm’s fundamentals and technologies, as well as the recent momentum in the arm’s ecosystem, support a bullish case for Arm. The main wall street concern is the current valuation for Arm. Arm’s securities trade at a multiple of over 100 times future earnings. I also see a bullish case for Arm given that it is currently trading above 251.63 and 253.42. I see 270.39 as the level that will confirm a further uptrend that will take Arm to 278.54 and 287.17.
Recommended Articles


