


The Japanese Yen sits still while Tokyo calls it undervalued
- USD/JPY sits still just above 157.00 as Tokyo calls the Yen undervalued.
- Japan spent a record ¥15.4 trillion on its last round of Yen buying.
- BoJ decides on October 30, two days after the Fed.
Finance Minister Katayama said on Tuesday that an undervalued Yen is generally a problem, and that she and US Treasury Secretary Bessent agreed on a September 25 call to strengthen their cooperation. She added that Japan will stay in close contact with the US Treasury to maintain orderly currency markets. USD/JPY closed just above 157.00, inside Monday's range.
Japan's last round of Yen buying began on July 30, with the Yen near its weakest in about four decades, and the Ministry of Finance (MoF) spent a record ¥15.4 trillion on it. USD/JPY is about six Yen lower than where that buying started, and Finance Minister Katayama now calls the Yen undervalued anyway.
Not reflationary, which leaves the BoJ room to hike
Finance Minister Katayama also said Prime Minister Takaichi's government is not reflationary. Vice Finance Minister for International Affairs Mimura said on Monday that markets should take the message from Tokyo and Washington seriously, and MUFG analysts read the comments since Monday as encouraging bets that the Bank of Japan (BoJ) will raise rates faster under US pressure.
The BoJ raised its policy rate to 1.25% on September 18, its highest in 31 years, while the Fed's range sits at 3.75%-4.00%. An intervention buys time. Only a narrower rate gap would make it less attractive to borrow in Yen and buy higher-yielding US assets, the trade that keeps USD/JPY high. It would take ten more quarter-point BoJ hikes to reach the bottom of the Fed's range.
The BoJ's next decision comes two days after the Fed's
August retail sales are due first, at 23:50 GMT on Tuesday, forecast up 3.3% YoY after 4%. The MoF publishes its intervention figures for August 27 to September 28 on Wednesday, which will show whether the rate check reported on September 18 turned into actual Yen buying. Japan's quarterly Tankan survey follows at 23:50 GMT on Wednesday, with the large manufacturers' index forecast at 25 from 22. The BoJ's summary of opinions from its September meeting is due at the same minute.
A large figure from the MoF would show that the September warnings came with money behind them, and that would make the next run toward the year's highs costlier for Dollar buyers. A small one would mean Tokyo has been talking rather than buying since late August.
Tokyo's September consumer prices come out on Thursday at 23:30 GMT, with inflation excluding fresh food forecast at 2.4% YoY from 1.8%, alongside a jobless rate forecast at 2.4%. Across the Pacific, the Fed's preferred inflation measure lands on Wednesday and payrolls on Friday, both feeding a decision on October 28 that comes two days before the BoJ's.
Technical levels
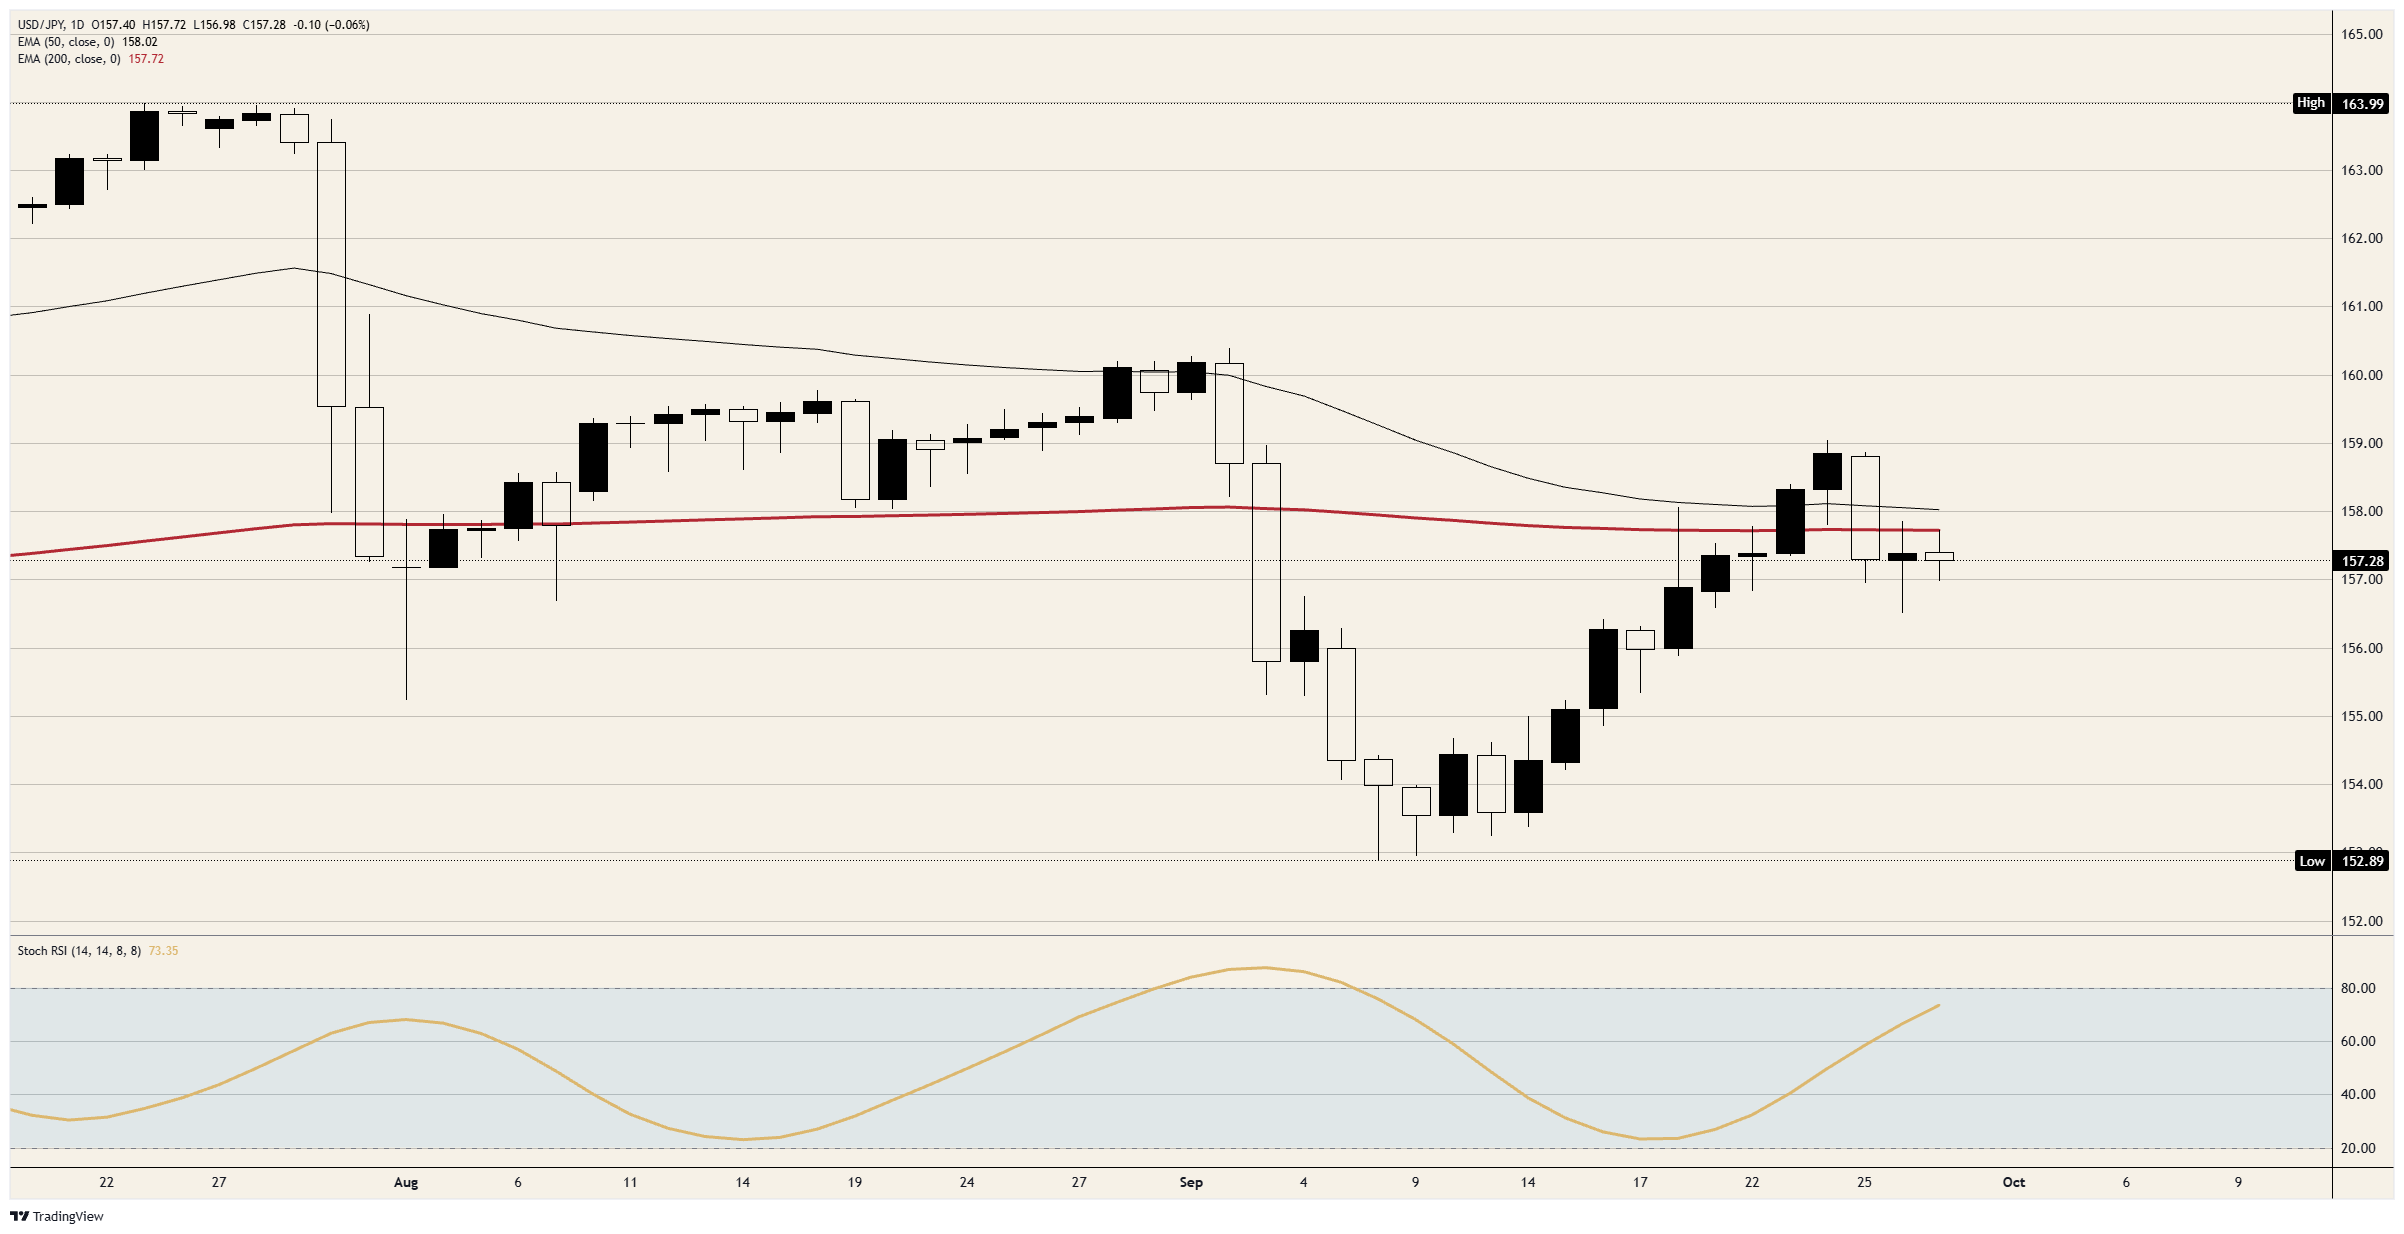
Resistance: Tuesday's high stopped at the 200-day Exponential Moving Average (EMA), just under 158.00, and Monday's high also fell short of 158.00. Above it, Thursday's high near 159.00 is where Friday's drop began.
Support: 157.00 held Friday's and Tuesday's lows. Below it, Monday's dip ended near 156.50, and the September 18 low just under 156.00 is the floor after that.
Bias: Short below 158.00, looking for 156.50 first and 156.00 after that. Momentum hasn't turned yet: the daily Stochastic Relative Strength Index (Stoch RSI) has climbed to 73 and is still rising, so a push toward 158.00 could come before the drop. A daily close above 158.50 ends it.
USD/JPY daily chart
Japanese Yen FAQs
The Japanese Yen (JPY) is one of the world’s most traded currencies. Its value is broadly determined by the performance of the Japanese economy, but more specifically by the Bank of Japan’s policy, the differential between Japanese and US bond yields, or risk sentiment among traders, among other factors.
One of the Bank of Japan’s mandates is currency control, so its moves are key for the Yen. The BoJ has directly intervened in currency markets sometimes, generally to lower the value of the Yen, although it refrains from doing it often due to political concerns of its main trading partners. The BoJ ultra-loose monetary policy between 2013 and 2024 caused the Yen to depreciate against its main currency peers due to an increasing policy divergence between the Bank of Japan and other main central banks. More recently, the gradually unwinding of this ultra-loose policy has given some support to the Yen.
Over the last decade, the BoJ’s stance of sticking to ultra-loose monetary policy has led to a widening policy divergence with other central banks, particularly with the US Federal Reserve. This supported a widening of the differential between the 10-year US and Japanese bonds, which favored the US Dollar against the Japanese Yen. The BoJ decision in 2024 to gradually abandon the ultra-loose policy, coupled with interest-rate cuts in other major central banks, is narrowing this differential.
The Japanese Yen is often seen as a safe-haven investment. This means that in times of market stress, investors are more likely to put their money in the Japanese currency due to its supposed reliability and stability. Turbulent times are likely to strengthen the Yen’s value against other currencies seen as more risky to invest in.
Recommended Articles


