




Broadcom vs. Micron: Which Semiconductor Stock Is the Better AI Buy over the Next 3 Years?
Key Points
Micron and Broadcom are key players in the AI infrastructure ecosystem.
Micron's latest results suggest that the company's red-hot growth is sustainable.
Broadcom sees a major improvement in AI revenue over the next couple of years, setting the stock up for a major rally.
- 10 stocks we like better than Micron Technology ›
Broadcom (NASDAQ: AVGO) and Micron Technology (NASDAQ: MU) are among the most important players in the artificial intelligence (AI) semiconductor ecosystem, as both companies are witnessing phenomenal demand for their products that handle AI workloads in data centers.
Broadcom designs custom AI processors and networking components, used by major hyperscalers, enterprises, and AI labs to lower operating costs in AI data centers. Micron, meanwhile, makes compute and storage memory, which helps store and rapidly transport large data sets in AI chip clusters and feeds data quickly to AI accelerators, including Broadcom's custom chips.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
We will take a closer look at the prospects of both semiconductor stocks in this article and determine which one could be the bigger winner over the next three years.
Image source: Getty Images.
Micron Technology's phenomenal growth isn't stopping any time soon
Micron released fiscal 2026 fourth-quarter results (for the three months ended Sept. 3) on Sept. 30. The company's revenue increased 379% year over year to $54.23 billion, while adjusted earnings rose by 11x to $33.42 per share. Wall Street would have settled for $31.61 in earnings per share (EPS) on revenue of $51.07 billion.
However, the AI-fueled demand for memory and the accompanying supply shortage helped Micron crush consensus expectations. The company's operating income increased to 82.3% last quarter from 35% in the year-ago period. What's more, Micron management expects fiscal 2027 to be "even better," with "memory and storage supply demand conditions to be much tighter in fiscal 2027 and 2028 than they were in 2026."
Not surprisingly, Micron's guidance for the current quarter is well above Wall Street's expectations. The company expects $61.5 billion in revenue in the current quarter, implying a 4.5x increase over the prior year. Additionally, the earnings per share guidance of $38.15 implies an increase of nearly 8x from the same quarter last year.
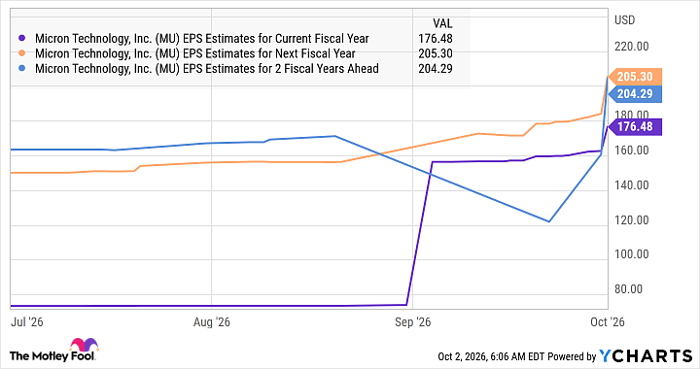
Analysts were expecting $35.40 in adjusted earnings per share on $57 billion in revenue. Clearly, the favorable memory market conditions that Micron management spoke of during the latest earnings call will ensure its red-hot growth continues. This also explains why analysts have significantly increased their bottom-line growth expectations for Micron for the next three years.
Data by YCharts
What's worth noting is that analysts expect Micron's earnings to drop in fiscal 2029. However, that may not be the case amid strong memory demand and the tightening supply conditions. So, don't be surprised to see analysts increasing their fiscal 2029 EPS estimate as the year progresses, paving the way for more upside in Micron stock over the next three years following a 284% surge in 2026.
Broadcom's AI business is poised to grow at an incredible pace
Though Broadcom stock has underperformed this year with a flat performance on the market, investors shouldn't underestimate the company's rapidly growing AI semiconductor business that could change its fortunes. The chip designer has built a solid client base, including Alphabet's Google, OpenAI, Anthropic, Meta Platforms, and others.
These customers have been ramping up the deployment of Broadcom's AI chips. This explains why the company's AI revenue in fiscal 2026 (which ends early next month) is on track to jump by 186% over last year to $58 billion. Looking ahead, Broadcom expects AI revenue to increase to $115 billion in fiscal 2027 and $230 billion in fiscal 2028.
This phenomenal growth in AI revenue will supercharge Broadcom's bottom line, with the company expecting its EPS to exceed $30.00 in fiscal 2028. This forecast points to a substantial jump in Broadcom's earnings over the next couple of years.
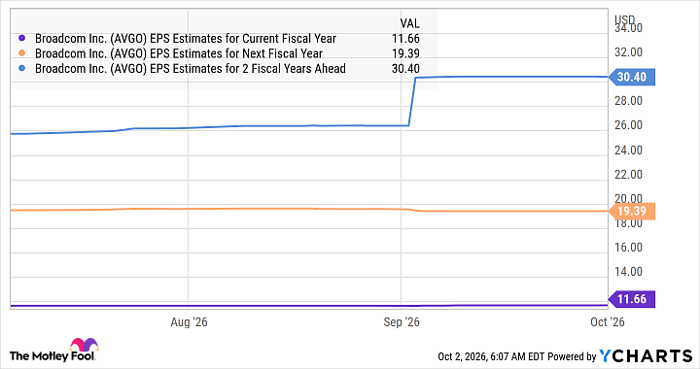
Data by YCharts
There is a strong chance of Broadcom sustaining its robust earnings growth beyond fiscal 2028, as the custom AI processor market is expected to clock annual growth of 24% through 2035, according to Globe Market Research. As such, Broadcom seems in a solid position to maintain robust bottom-line growth over the next three years.
The verdict
Both these AI stocks are on track to deliver impressive earnings growth over the next three years. However, if you can buy just one of these two stocks right now, Micron could be the one for you. That's because Micron trades at a significantly cheaper valuation than Broadcom.
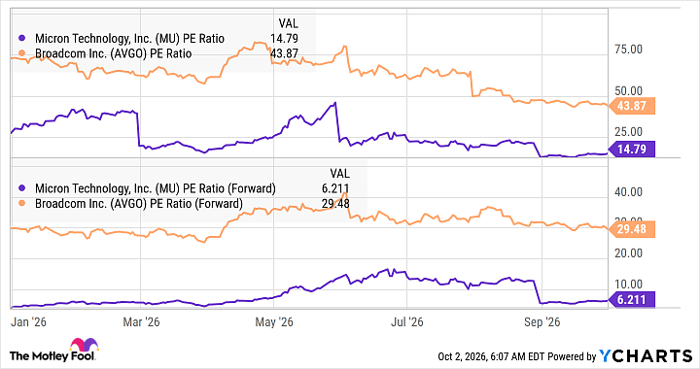
Data by YCharts
Also, Micron has a higher growth rate than Broadcom.
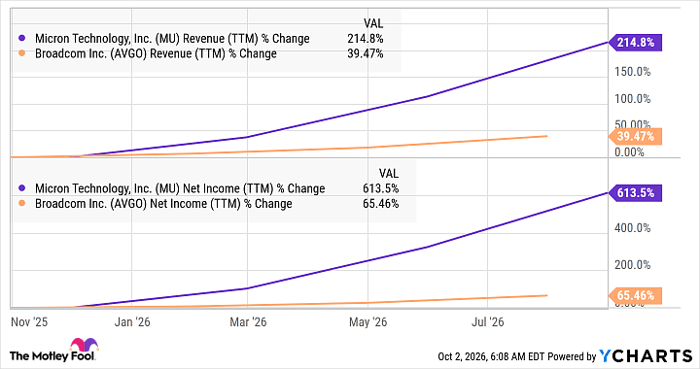
Data by YCharts
Of course, even Broadcom could prove a solid long-term investment, given its strong position in the custom AI processor market. However, Micron looks like the better choice for investors seeking a mix of value and growth, especially given its potential to become a multibagger investment by the end of the decade, driven by its cheap valuation and terrific growth prospects.
Should you buy stock in Micron Technology right now?
Before you buy stock in Micron Technology, consider this:
The Motley Fool Stock Advisor analyst team just identified what they believe are the 10 best stocks for investors to buy now… and Micron Technology wasn’t one of them. The 10 stocks that made the cut could produce monster returns in the coming years.
Consider when Netflix made this list on December 17, 2004... if you invested $1,000 at the time of our recommendation, you’d have $361,650!* Or when Nvidia made this list on April 15, 2005... if you invested $1,000 at the time of our recommendation, you’d have $1,437,517!*
Now, it’s worth noting Stock Advisor’s total average return is 936% — a market-crushing outperformance compared to 211% for the S&P 500. Don't miss the latest top 10 list, available with Stock Advisor, and join an investing community built by individual investors for individual investors.
See the 10 stocks »
*Stock Advisor returns as of October 4, 2026.
Harsh Chauhan has no position in any of the stocks mentioned. The Motley Fool has positions in and recommends Alphabet, Broadcom, Meta Platforms, and Micron Technology. The Motley Fool has a disclosure policy.
Recommended Articles


