




This AI Infrastructure Stock Is Up 177% in 2026, and It Is Significantly Cheaper Than Nebius
Key Points
DigitalOcean's revenue pipeline is growing at an incredible pace.
The company's full-stack AI platform is encouraging customers to spend more money on its solutions.
DigitalOcean's cheap valuation indicates that it isn't too late for investors to buy this high-flying stock.
- 10 stocks we like better than DigitalOcean ›
Neocloud infrastructure provider Nebius Group has been growing at an incredible pace, which isn't surprising as it provides specialized artificial intelligence (AI) data center infrastructure to AI labs, hyperscalers, and enterprises.
Nebius is sitting on a massive backlog, which should ensure healthy long-term growth. What's worth noting is that Nebius' incredible growth and sizable backlog have been handsomely rewarded on the stock market this year. Nebius stock has gained 182% in 2026, as of this writing.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Nebius can continue to fly higher, especially given that it has been taking smart steps to reduce capital outlay while scaling up AI data center capacity. However, what's worth noting is that this AI cloud stock has been outperformed by a company that's growing at a significantly slower pace -- DigitalOcean (NYSE:DOCN).
Let's see why that has been the case.

Image source: Getty Images.
DigitalOcean's AI pivot is paying off
DigitalOcean stock has soared an incredible 177% in 2026. This phenomenal rally has been fueled by the company's shift toward offering AI-focused solutions.
DigitalOcean made its name by offering on-demand cloud computing infrastructure to small businesses, developers, and start-ups. It positioned itself as a cheaper alternative to larger cloud computing companies, offering greater flexibility, lower complexity, and more competitive pricing. However, it is the company's shift toward offering AI-focused cloud infrastructure that has sparked investor interest in the stock.
DigitalOcean now offers an AI-native cloud infrastructure platform that includes both hardware and software solutions. DigitalOcean customers can rent dedicated AI hardware, such as graphics processing units (GPUs), develop and deploy AI agents, store data, access popular large language models (LLMs), and run inference applications using its full-stack AI infrastructure platform.
DigitalOcean's shift toward offering AI tools and services is paying off nicely for the company. It reported a 29% year-over-year increase in revenue in the second quarter to $281 million. However, the more important metric to note was the 12x year-over-year jump in DigitalOcean's remaining performance obligation (RPO) to $894 million.
RPO is the total value of a company's contracts yet to be fulfilled at the end of a quarter. The exponential growth in this metric suggests that DigitalOcean is building a solid revenue pipeline that should boost its growth in the future.
An increase in customer spending is driving an impressive increase in DigitalOcean's RPO. The company notes that the annual run-rate revenue (ARR) of customers spending $1 million or more on its cloud platform increased by 214% year over year in Q2 to $259 million. This was higher than the 160% increase in ARR for customers spending $500,000 or more, suggesting that DigitalOcean is now landing larger contracts.
The company also noted that the ARR of AI-focused customers increased by 212% year over year to $234 million. DigitalOcean calculates its ARR by multiplying revenue in the most recent quarter by four. Inference solutions, specifically, are driving terrific growth in DigitalOcean's ARR. The company points out that adoption of its inference services increased by 800% year over year last quarter.
The growing adoption of inference-based services should be a tailwind for DigitalOcean's bottom line in the long run, which explains why analysts are anticipating a big spike in its earnings growth rate in 2028.
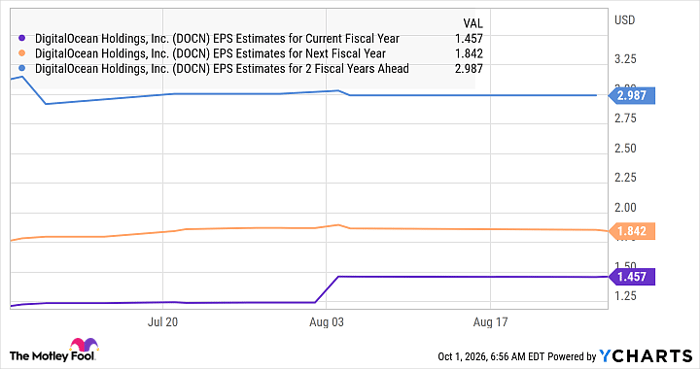
DOCN EPS Estimates for Current Fiscal Year data by YCharts
DigitalOcean's cheap valuation and growth potential will pave the way for more gains
DigitalOcean is a smaller company than Nebius. It has a market cap of $15.7 billion, lower than Nebius' $64 billion. More importantly, it is significantly cheaper than its bigger rival despite its stunning rally this year.
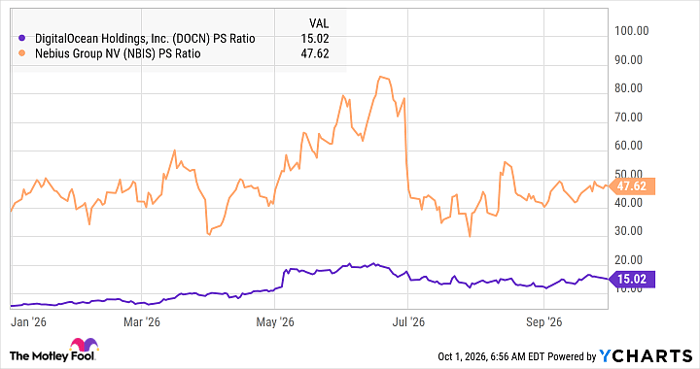
DOCN PS Ratio data by YCharts
DigitalOcean's trailing price-to-sales ratio of 16 is a third of Nebius' multiple. Moreover, DigitalOcean remains cheaper when the forward price-to-sales ratio is considered. Of course, Nebius is growing at a significantly faster pace, but investors seeking a mix of value and growth may consider buying DigitalOcean stock instead.
Moreover, the exponential spike in DigitalOcean's RPO suggests its revenue growth rate could accelerate impressively. In fact, management expects DigitalOcean's revenue to increase by at least 50% in 2027, well above the projected 2026 growth of 30.5%. Analysts are confident that the company will maintain its robust growth in 2028 as well.
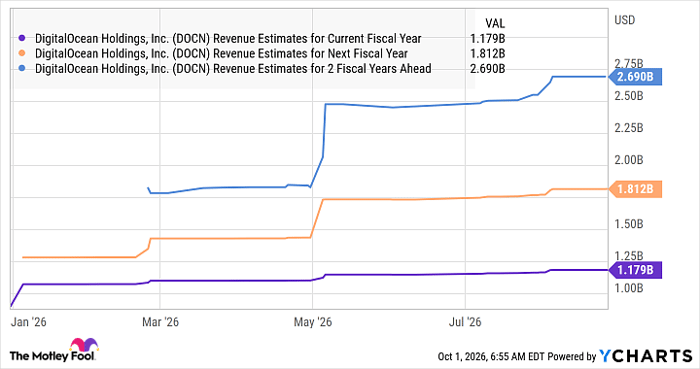
DOCN Revenue Estimates for Current Fiscal Year data by YCharts
Assuming DigitalOcean's top line jumps to $2.7 billion in 2028, and it trades at even 10 times sales at that time, its market cap could increase to $27 billion. That implies potential upside of 72%, though I won't be surprised to see bigger gains from this AI stock, as it can grow faster than consensus expectations and command a higher sales multiple as a result.
So, investors looking for an affordable way to profit from the AI infrastructure boom can consider buying DigitalOcean before it soars even higher.
Should you buy stock in DigitalOcean right now?
Before you buy stock in DigitalOcean, consider this:
The Motley Fool Stock Advisor analyst team just identified what they believe are the 10 best stocks for investors to buy now… and DigitalOcean wasn’t one of them. The 10 stocks that made the cut could produce monster returns in the coming years.
Consider when Netflix made this list on December 17, 2004... if you invested $1,000 at the time of our recommendation, you’d have $365,910!* Or when Nvidia made this list on April 15, 2005... if you invested $1,000 at the time of our recommendation, you’d have $1,418,530!*
Now, it’s worth noting Stock Advisor’s total average return is 930% — a market-crushing outperformance compared to 211% for the S&P 500. Don't miss the latest top 10 list, available with Stock Advisor, and join an investing community built by individual investors for individual investors.
See the 10 stocks »
*Stock Advisor returns as of October 2, 2026.
Harsh Chauhan has no position in any of the stocks mentioned. The Motley Fool has positions in and recommends DigitalOcean. The Motley Fool has a disclosure policy.
Recommended Articles


